


Transcosmos (TSE:9715) Stock Cools As Q2 Earnings Reveal Profit Squeeze
Transcosmos just reported Q2 2027 earnings and the headline is clear. Revenue reached ¥102,155 million while basic earnings per share came in at ¥55.21, keeping profitability in focus for a business built on people heavy outsourcing services. The twist sits in the share price. The stock closed at ¥3,675 on the day of the release after a slightly weaker 7 day run, which suggests investors leaned into caution even as the latest quarter pointed to revenue holding firm but net income experiencing a tighter profit squeeze.
Like the stability of transcosmos revenue but concerned about the tighter profit squeeze hinted at in the latest earnings per share figure? Check out list of solid balance sheet and fundamentals stocks (22 results).
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥102,155 million vs. ¥97,672 million (steady top line with single digit growth)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥2,069 million vs. ¥3,122 million (meaningful decline in quarterly profit)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥55.21 vs. ¥83.31 (earnings per share compressed sharply)
- Trailing 12M Net Profit Margin (latest year vs. prior year): 2.8% vs. 3.6% (profitability thinned even as revenue held up)
Ask Charlie what makes transcosmos look undervalued now.
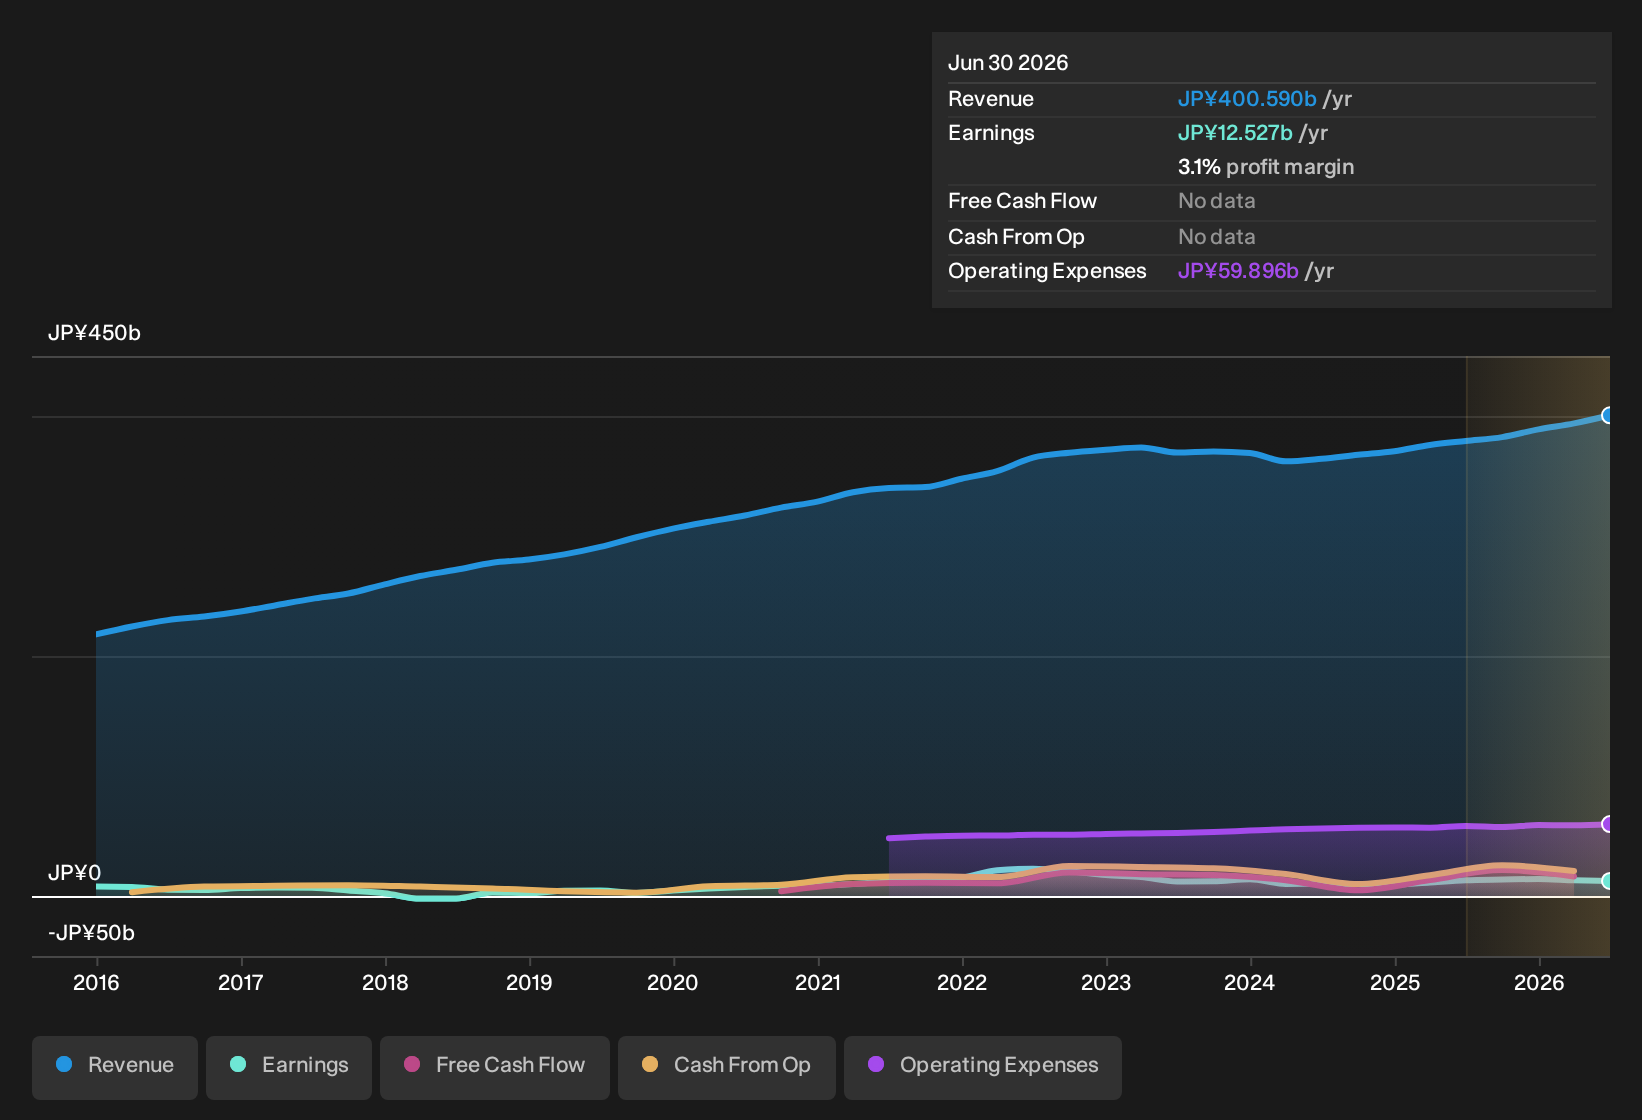
Transcosmos revenue resilience against cautious optimism
Bulls who see Transcosmos as a steady outsourcing and digital commerce partner get partial support from these figures. Revenue of ¥102,155 million compared with ¥97,672 million points to a top line that is holding up. That fits a story of diversified services and long client ties providing some cushion. Recent product news in AI assisted supply demand planning and cross border digital content also lines up with the idea that the group is plugged into e commerce and data heavy work, even if that has not yet translated into stronger profitability.
Profit squeeze keeps the bearish case alive
Bearish arguments around low margins and wage heavy operations find backing in this quarter. Net income excluding extra items moved from ¥3,122 million to ¥2,069 million and basic EPS compressed from ¥83.31 to ¥55.21. Trailing net margin slipped from 3.6% to 2.8%. Those shifts point to pressure on earnings capacity even as revenue stays firm. A 7 day share price fall of about 3% around the 30 October close shows investors already reacting to that squeeze, while the modest positive 30 and 90 day moves suggest no clear breakdown in confidence yet.
After a quarter where revenue held firm but net income compressed and the dividend record looks unstable, it is worth asking whether transcosmos has deeper structural weak spots. Review the full risk analysis for transcosmos which shows 1 important warning signHunt Balance Sheets Under Pressure
transcosmos just showed how steady revenue can coexist with a tightening profit picture. The real opportunity is in hunting for stocks that could be low debt before the market closes the gap.
- Company 1 - 35% below our estimate - focuses on AI driven hiring tools and local services platforms that convert job and consumer traffic.
- Company 2 - 18% below our estimate - expands a maintenance focused elevator service network by hiring more salespeople to win contracts and deepen route density.
- Company 3 - 45% below our estimate - pushes an AI first security platform and subscription model that tie protection budgets to recurring software contracts.
Those are three of them. See the full list of 22 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com