


3 European Bank Stocks For Higher Rates Including BBVA Stock
Markets have shifted from asking if central banks will hike again to wondering how long higher rates might stick, and that change puts interest-sensitive stocks in the spotlight. Prolonged tighter policy can reshape winners and laggards, which creates both opportunity and risk for anyone with idle cash on the sidelines. This article walks through three European bank stocks exposed to the latest rate headlines and what that could mean for a diversified portfolio.
The three banks covered below are just a starting sample, since the full screen surfaced 24 more European lenders with equally detailed stories that are not unpacked in this article. To see the wider field and identify your own candidates, go straight to the European Bank Stocks Benefiting from Higher Interest Rates screener to filter, analyze, and focus on the highest conviction plays.
Arbuthnot Banking Group (AIM:ARBB)
Overview: Arbuthnot Banking Group is a UK private and commercial bank that offers tailored lending, deposit, wealth management and specialist finance services.
Operations: Arbuthnot Banking Group generates most revenue from £99 million in core banking, with additional contributions from AAG (£17 million), RAF (£16 million), ACABL (£15 million), wealth management (£19 million) and smaller other divisions.
Market Cap: £134 million
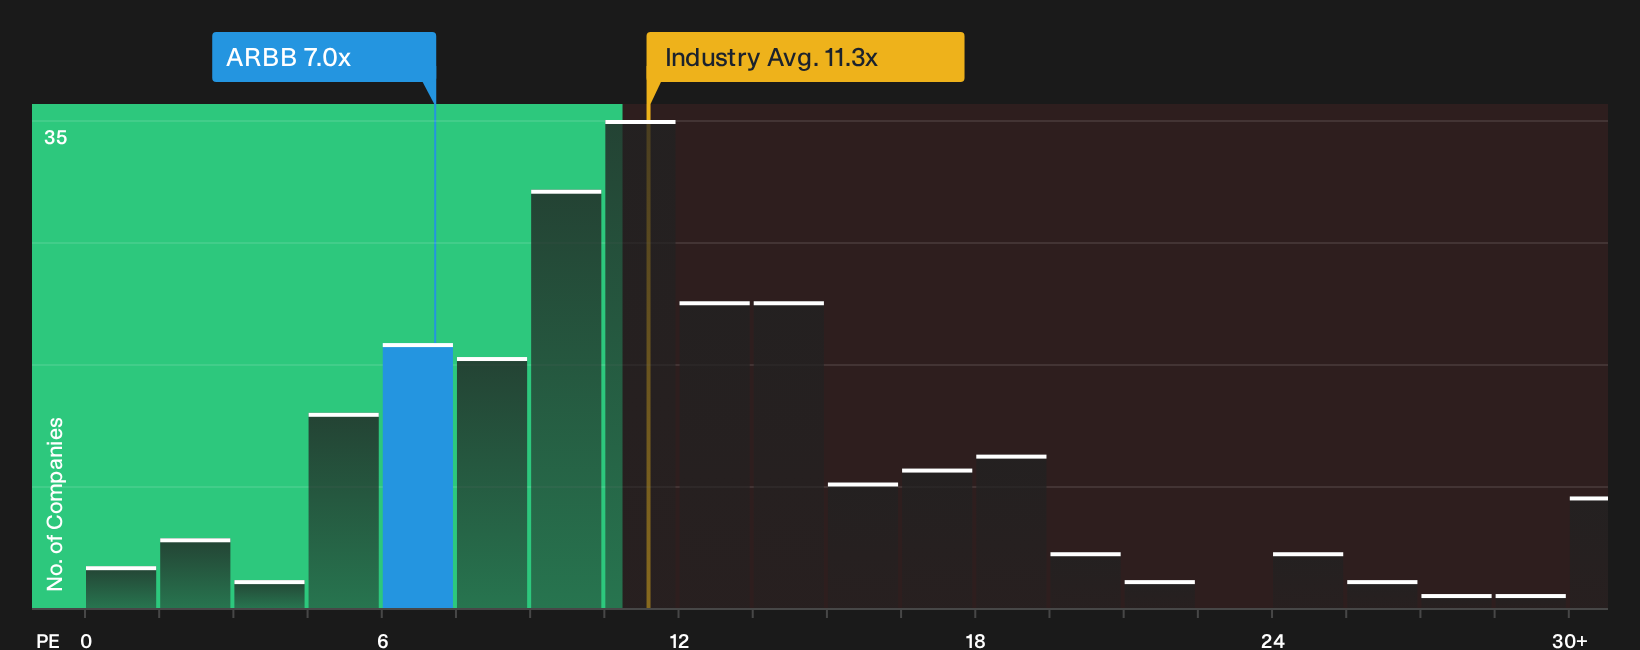
Arbuthnot Banking Group gives you a UK focused lender whose profitability is closely tied to Bank of England rate moves. It is trading on a 7x P/E, with earnings and revenue forecasts that point to solid potential if higher rates persist. However, future margins and credit costs still depend on how one unseen pressure develops.
That unknown pressure is exactly what makes Arbuthnot Banking Group interesting. Weigh up the 3 key rewards and 3 important warning signs to see what could shift sentiment next.
Banco Bilbao Vizcaya Argentaria (BME:BBVA)
Overview: Banco Bilbao Vizcaya Argentaria is a large Eurozone bank that provides retail, corporate, investment and digital banking across Spain, Mexico, Turkey and multiple global markets, with earnings closely tied to interest rate cycles.
Operations: BBVA generates most income from Mexico at €12.98b and Spain at €9.18b, with further material contributions from South America and Turkey.
Market Cap: €114.87b
For anyone focused on European banks that are closely linked to the interest rate environment, Banco Bilbao Vizcaya Argentaria offers a direct line into how higher policy rates can feed through to net interest income, loan demand and dividend capacity across several major economies.
"The order from Spain’s National Court for BBVA and its former chairman to stand trial on one count of bribery and 52 counts of unlawful discovery and disclosure of secrets in the Villarejo case, with prosecutors seeking significant prison terms, introduces the possibility of higher legal expenses, potential penalties and reputational effects that could pressure costs, funding spreads and ultimately net income."
One key question is what happens if a single pressure point quietly changes how much room BBVA has to keep turning higher rates into durable profitability.
That pressure point is only half the story, and the full narrative for Banco Bilbao Vizcaya Argentaria shows how BBVA’s legal overhang could interact with rates, capital plans and market expectations.

KBC Group (ENXTBR:KBC)
Overview: KBC Group is a Brussels based banking and insurance group providing loans, deposits, protection and investment products across several Central European markets.
Operations: KBC Group generates most revenue from the Belgium Business at €7.37b and Czech Republic Business at €2.65b, supported by Hungary, Bulgaria and Slovakia.
Market Cap: €45.26b
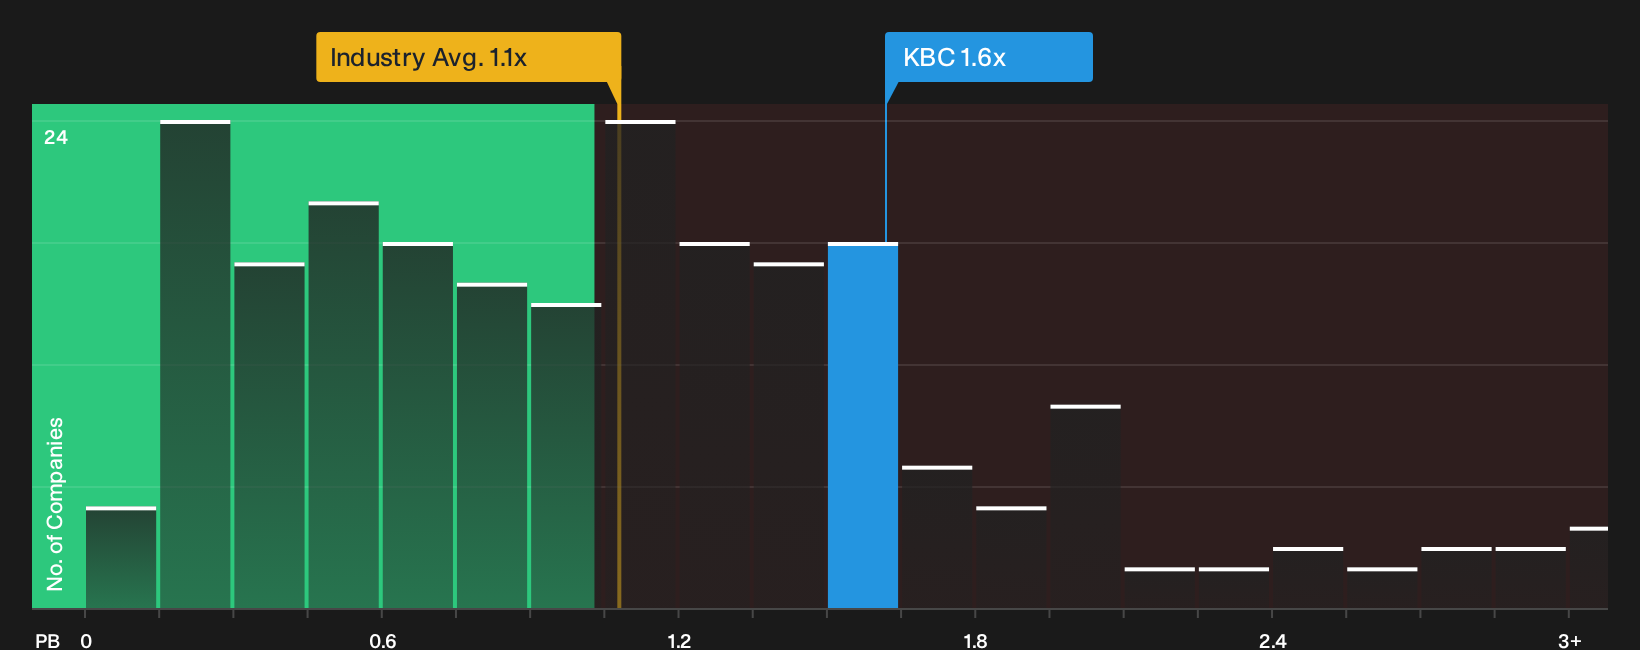
KBC Group sits closely aligned with higher ECB linked rates, since its mix of retail banking and insurance turns every move in Eurozone policy into a direct question about loan spreads, deposit costs and how much income it can keep returning to shareholders.
"If KBC’s equity beta normalizes toward 1.0 (pushing Cost of Equity to ~8.15%), both model outputs drop significantly below the bottom of their sensitivity ranges."
The key issue now is whether a quiet shift in how markets price that risk changes the room KBC Group has to keep monetising higher rates.
If that repricing risk matters to you, read the full narrative for KBC Group to see how KBC Group’s rate sensitivity could be masking upside or amplifying volatility.
Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout stories gain momentum while hesitation gets caught flat footed and entry windows keep dropping out of reach. Scan under the radar for now and get in early.
- Spot income workhorses that aim to keep portfolios flying through thick and thin by checking the 5 dividend fortresses while that yield edge still matters.
- Hunt for future market leaders quietly building strength inside the 5 high quality undiscovered gems before attention spikes and pricing power shifts away from patient buyers.
- Target resilient operators where balance sheets do the heavy lifting and use the list of solid balance sheet and fundamentals (10 results) to keep risk in check while momentum is on your side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com