


What Indorama Ventures Holders Bought Into
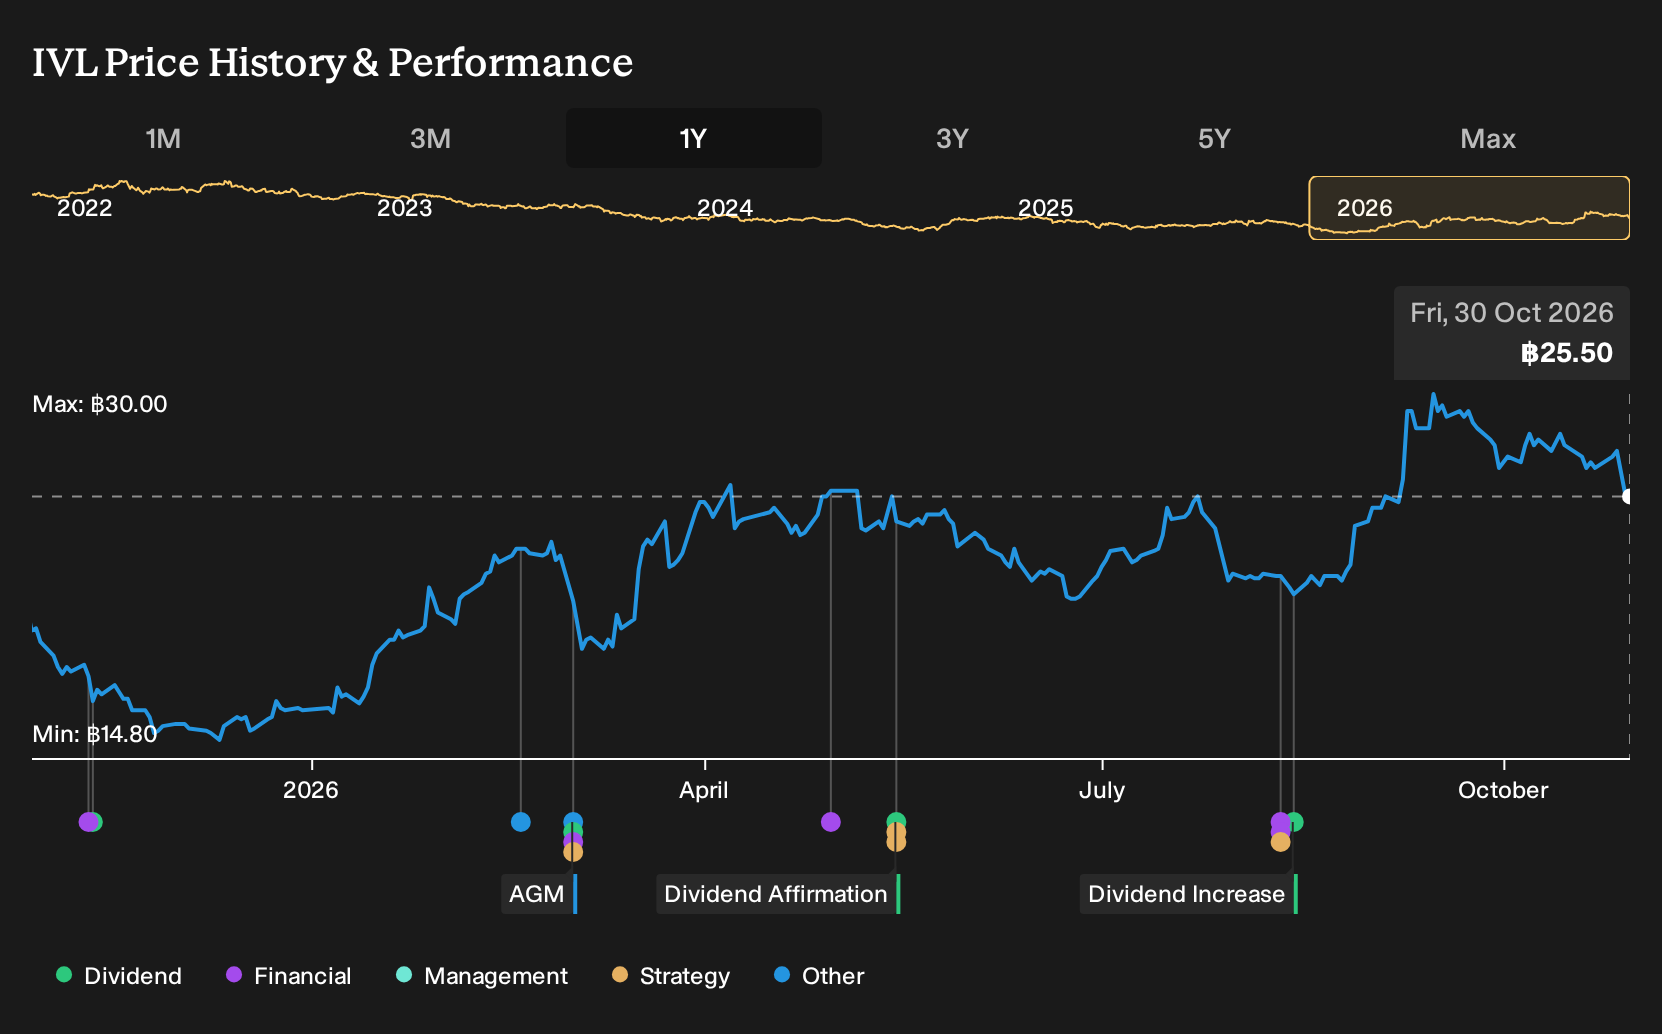
Recycling moved from slide decks to hard numbers when Indorama Ventures reported Q2 2026 revenue of THB118,745.174 million and net income, excluding extra items, of THB5,733.261 million, with net margin improving to 4.2%. Investors who held Indorama Ventures over the past year are up 38.1%, including dividends. If you were deciding on 30 October 2025, what had to be believed about that recycling push and margin repair for this outcome to feel plausible?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Indorama Ventures has already moved. See which of 203 high quality undervalued stocks still trade below our estimates.
The Two Indorama Ventures Stories Investors Had To Weigh
The shares cost THB19.7 at the start, and Indorama Ventures sat between two very different stories about plastics, recycling, and regulation.
On the optimistic side, the bull narrative put Fair Value at THB24.79 and assumed recycling and sustainable packaging investments would support higher net margins and premium pricing as demand for recycled PET rose.
The bear camp saw Fair Value at THB18 and focused on tightening rules on plastics, with concern that persistent global PET oversupply would keep pressure on product margins.
What The Results Changed For The Indorama Ventures Case
The clearest data point for Indorama Ventures is the swing from a loss of THB749.135 million in Q2 2025 to net income, excluding extra items, of THB5,733.261 million in Q2 2026. Net margin moved from -0.6% to 4.2%. That shift in profitability supported the optimistic recycling and margin repair thesis more than the cautious case, even though it did not fully resolve long-term questions about PET oversupply.
The lesson is simple. When an investment thesis depends on margin recovery, treat net margin as the primary checkpoint and compare it across matching quarters, rather than looking only at revenue or share price moves.
What Indorama Ventures' Price Already Assumes
Indorama Ventures trades at THB25.5 today after a 38.1% gain over the past year. This Narrative’s Fair Value sits below the current price, so it treats the stock as pricing in a demanding execution story rather than deep value.
The selected Narrative focuses on whether margin repair, cash generation and the IVL 2.0 plan can all endure at once. For today’s price to make sense, a buyer has to judge that management can deliver cost cuts, portfolio reshaping and deleveraging without PET spreads or working capital gains slipping backwards.
"Although Indorama Ventures is reporting broad based margin recovery and very strong combined PET EBITDA in 1H26, management acknowledges that roughly one third of the 2Q26 uplift stems from cyclical and inventory effects that may unwind as crude linked pricing and MTBE seasonality fade. This could pull back EBITDA and cash flow from current levels."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Where Indorama Ventures’ Theme Connects
Recycling at Indorama Ventures points to a wider question. What happens when critical materials also need a closed loop?
Alongside plastics, clean energy and electronics depend on rare earth magnets that are difficult to replace and challenging to source responsibly.
One specialist miner is shifting from simply digging ore to refining, magnet making and building its own recycling capability.
That move aims to keep more value in house while navigating policy pressure, technical complexity and concentrated customers.
If recycling and domestic supply both matter to you, this parallel story is worth a closer look.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 79% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com