


Nippon Shinyaku (TSE:4516) Looks Fairly Valued As Tanabe Lymphoma Drug Deal Lands
Nippon Shinyaku (TSE:4516) has signed an exclusive sublicense agreement with Tanabe Pharma to market loncastuximab tesirine (MT-2111) for relapsed or refractory diffuse large B-cell lymphoma in Japan.
Set against this agreement, Nippon Shinyaku’s share price has drifted lower over 2026, with the year-to-date share price return down 37.91% and the 1-year total shareholder return up 9.86%, hinting at weak recent momentum but some support from dividends or past gains.
Scan Nippon Shinyaku alongside other potential turnaround stories by reviewing our curated list of 69 high quality undiscovered gems with fundamentals that may not yet be fully reflected in their share prices.
Nippon Shinyaku now holds rights to a first in class lymphoma therapy, while the share price has already fallen hard this year. Is most of the repricing done, or does the valuation still leave meaningful upside on the table?
Preferred P/E of 7.3x: Is it justified for Nippon Shinyaku?
Nippon Shinyaku trades on a P/E of 7.3x and is flagged as good value compared both to the wider Japanese market and to pharmaceutical peers, which suggests the current ¥3,436 share price bakes in muted expectations.
The P/E multiple compares what investors pay today for each unit of current earnings. For a drug maker with established products, a lower P/E can indicate the market is cautious about future profit trends or is applying a discount to a business seen as ex growth.
Here, the discount is clear. Nippon Shinyaku's 7.3x P/E sits below the JP market at 13.4x, and also below the JP Pharmaceuticals industry on 14.1x. It is also slightly below an estimated fair P/E of 7.8x, which points to a level the market could potentially gravitate towards if sentiment or earnings expectations change.
Explore the SWS fair ratio for Nippon Shinyaku.
Result: Price-to-Earnings of 7.3x (UNDERVALUED)
Still, the sharp 58.3% share price decline over five years and the 39.5% annual fall in net income growth highlight that investor patience with Nippon Shinyaku can quickly wear thin.
Find out about the key risks to this Nippon Shinyaku narrative.
Another View on Nippon Shinyaku’s Value
The SWS DCF model paints a very different picture for Nippon Shinyaku. On this cash flow view, the estimated future cash flow value is ¥2,181.87 per share, which is well below the current ¥3,436 price and points to an overvalued result instead of a discount. Which signal do you treat as more important: current earnings or long term cash flows?
Look into how the SWS DCF model arrives at its fair value.
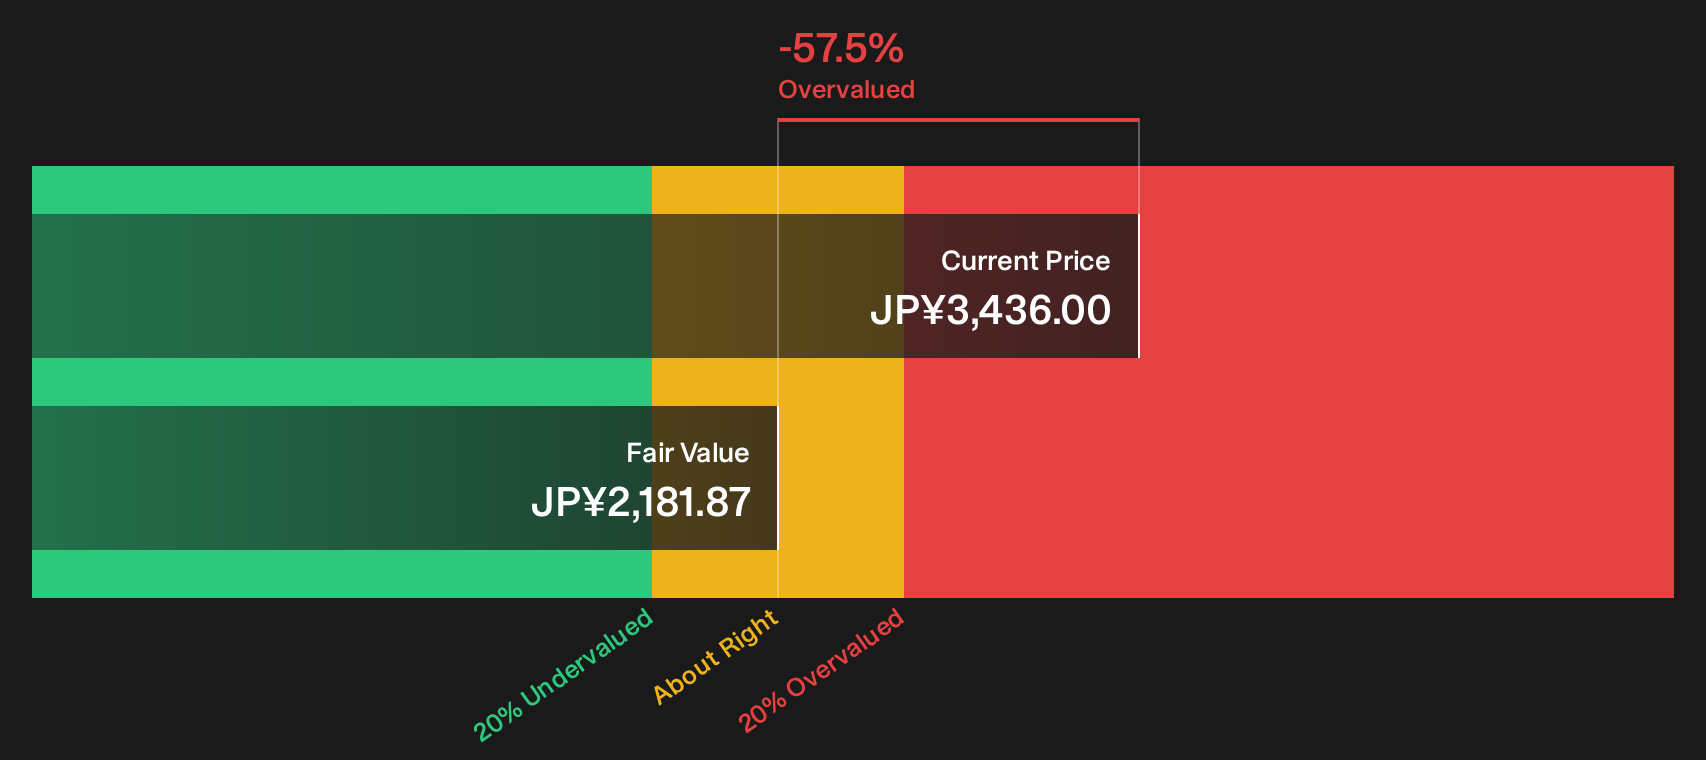
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nippon Shinyaku for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or early opportunity? You need to see the full picture yourself and act on your own judgement. Weigh both sides of Nippon Shinyaku’s story by checking the 4 key rewards and 1 important warning sign
Looking for more Nippon Shinyaku style investment ideas?
If Nippon Shinyaku has your attention, it makes sense to scan other opportunities with solid fundamentals and different risk profiles using the Simply Wall St screener.
- Spot potential turnarounds early by checking companies that screen as 69 high quality undiscovered gems before the broader market pays attention.
- Prioritise resilience by filtering for 23 resilient stocks with low risk scores that may suit a steadier approach when you do not want big swings.
- Focus on financial strength by reviewing a list of solid balance sheet and fundamentals (21 results) so you are not caught off guard by weak funding or stretched leverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com