


BJ's Restaurants (BJRI) Gets A Fresh Bullish Call With Valuation Still In Focus
Mizuho Securities recently highlighted BJ's Restaurants (BJRI) as one of its preferred U.S. restaurant stocks ahead of third quarter earnings, citing expectations for stronger sales trends supported by menu tweaks and promotional activity.
That optimism is landing on a stock that has already had a strong run. BJ's Restaurants’ share price return is up 52.18% year to date, and the 1-year total shareholder return of 84.13% suggests momentum has been building, even with a recent 1-day share price decline of 1.19% and a 90-day share price return that is down 8.43% as investors reassess expectations around menu initiatives and recent promotions.
Capitalize on the momentum around BJ's Restaurants and see how it compares to other hand-picked consumer stocks with strong fundamentals in our 19 high quality undiscovered gems.BJ's Restaurants has surged ahead of many peers, yet the shares still trade below the average analyst target while some models flag a premium to intrinsic value. Where does a reasonable fair value line up between those two markers?
Most Popular Narrative: 17% Undervalued
On the most followed view of BJ's Restaurants, the current share price of $62.53 sits below an estimated fair value of about $75, which hinges on traffic, margins and cash generation all pulling together.
The main condition for success is that BJ's Restaurants converts its traffic-led recovery, menu renovation program, and technology-supported operations into sustainably higher restaurant-level margins and cash generation as it resumes unit growth.
The current numbers and recent share price gains imply the market is already pricing BJ's Restaurants above some intrinsic value estimates, even though this narrative presents the stock as undervalued and bullish.
See why 1 investors see BJ's Restaurants as 17% undervalued.
Result: Fair Value of $75 (UNDERVALUED)
Still, the bullish BJ's Restaurants narrative depends on cost pressures remaining manageable and on digital and off premise execution not falling further behind faster moving rivals.
Find out about the key risks to this BJ's Restaurants narrative.
Another Angle on BJ's Restaurants Valuation
The first narrative leans on future earnings to suggest BJ's Restaurants is trading below a fair value of about $75. A different lens, the SWS DCF model, prices the future cash flows at roughly $54 per share, which points to the current $62.53 level as expensive instead.
That gap matters. If the market leans toward the DCF view, investors are paying up today for cash flows that model values lower, which tightens the margin for error if traffic, margins or unit growth underwhelm.
Understanding how this cash flow view is built can help you decide which story feels more realistic for BJ's Restaurants over the long run and which assumptions you are comfortable backing with your own capital, Look into how the SWS DCF model arrives at its fair value..
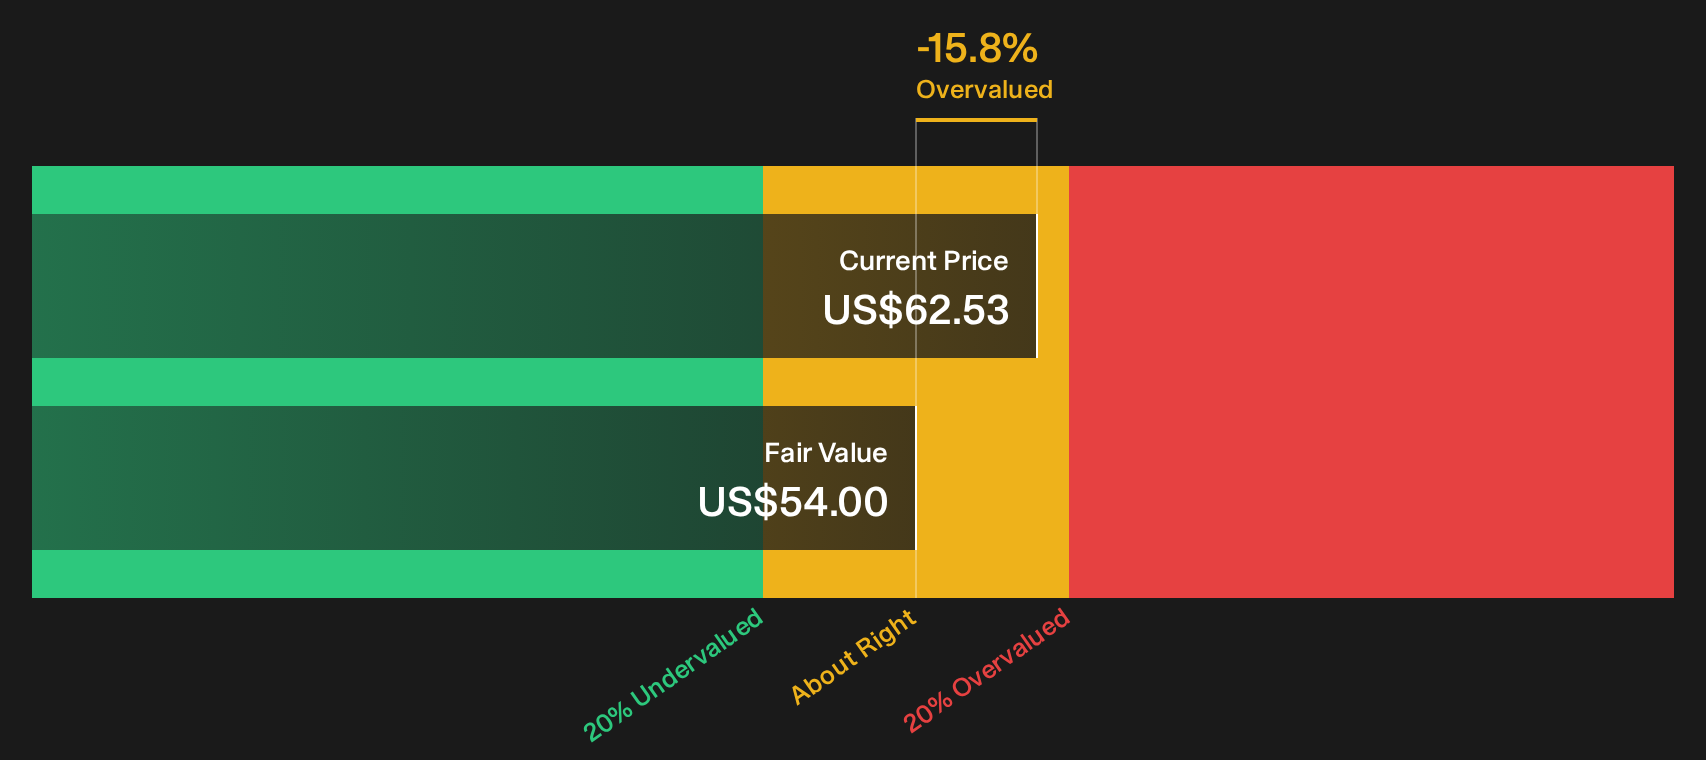
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BJ's Restaurants for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around BJ's Restaurants can feel confusing, especially with both risks and potential rewards in play, so move quickly, pull up the detailed breakdown, and weigh the 2 key rewards and 1 important warning sign.
Looking for more BJ's Restaurants style investment ideas?
If BJ's Restaurants has sharpened your interest, do not stop here. The real edge comes from lining up a watchlist of other high quality candidates.
- Target resilient returns by scanning a curated 29 resilient stocks with low risk scores that filters for businesses with more defensive profiles when markets turn choppy.
- Build long term income potential by reviewing the 5 dividend fortresses and focus on companies aiming to combine yield with staying power.
- Get ahead of the crowd by checking the 19 high quality undiscovered gems and hunt for quality businesses that many investors have not focused on yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com