


COSCO SHIPPING Energy Transportation (SEHK:1138) After Strong Earnings The Valuation Question Remains
COSCO SHIPPING Energy Transportation (SEHK:1138) just released nine month results to 30 September 2026, reporting revenue of CNY 25,243.45 million and net income of CNY 7,389.11 million, both significantly higher than last year’s figures.
The latest nine month earnings announcement has arrived after a strong run for COSCO SHIPPING Energy Transportation, with the share price up 26.02% over the past 90 days and an 81.28% year to date share price return. The 5 year total shareholder return of about 7x signals that longer term holders have already seen very large gains, even as the 1 month share price return is down 4.16%, hinting that momentum has cooled slightly into the results.
Capitalize on COSCO SHIPPING Energy Transportation's earnings momentum by scanning a hand picked set of 204 high quality undervalued stocks that pair strong fundamentals with potential mispricing.COSCO SHIPPING Energy Transportation has already delivered very large gains, yet the latest earnings surge and recent pullback leave a different puzzle. Is most of the upside already captured, or does the valuation still point to room ahead?
Preferred P/E of 9.3x for COSCO SHIPPING Energy Transportation: Is it justified?
On traditional metrics, COSCO SHIPPING Energy Transportation trades on a P/E of 9.3x, which sits above its closest peer group average of 8.3x yet below the broader Asian Oil and Gas industry average of 10.8x. The share price at the last close was HK$17.53, so the question for you is whether that earnings multiple reflects the recent surge in profitability or stretches too far ahead of itself.
The P/E ratio compares what investors pay today for each unit of current earnings. For an oil and LNG shipping operator like COSCO SHIPPING Energy Transportation, this metric often becomes a shorthand for how the market views the durability of freight rates, utilisation levels, and future earnings cycles, because profits can swing with shipping demand and contract terms.
Earnings growth over the past year was 163.7%, with current net profit margins of 27.2% compared with 14.4% a year earlier. That pace also exceeded the Oil and Gas industry figure of 7.1%. Against this backdrop, a 9.3x P/E can appear less aggressive than the peer premium alone might suggest, particularly when compared with an estimated fair P/E of 10.1x.
Compared with the Asian Oil and Gas industry average of 10.8x, the current 9.3x multiple places COSCO SHIPPING Energy Transportation at a discount to the wider regional group while still at a premium to its nearer peer set at 8.3x. That split suggests the market is pricing the shares as higher quality than direct peers yet still more conservatively than the broader sector, with the estimated fair P/E of 10.1x serving as a reference point.
Explore the SWS fair ratio for COSCO SHIPPING Energy Transportation.
Result: Price-to-earnings of 9.3x (ABOUT RIGHT)
Still, the story for COSCO SHIPPING Energy Transportation can shift quickly if freight cycles weaken or large vessel deliveries pressure utilisation and rates.
Find out about the key risks to this COSCO SHIPPING Energy Transportation narrative.
Another view on COSCO SHIPPING Energy Transportation’s value
The P/E story tilts slightly supportive for COSCO SHIPPING Energy Transportation, yet the SWS DCF model points the other way. On that measure, the share price of HK$17.53 sits well above an estimated future cash flow value of HK$6.81, which flags a material valuation gap that investors need to weigh.
This kind of disagreement between earnings based and cash flow based yardsticks raises a simple question. Which signal do you trust more when earnings are strong, but long term cash flows are priced far richer?
Look into how the SWS DCF model arrives at its fair value.
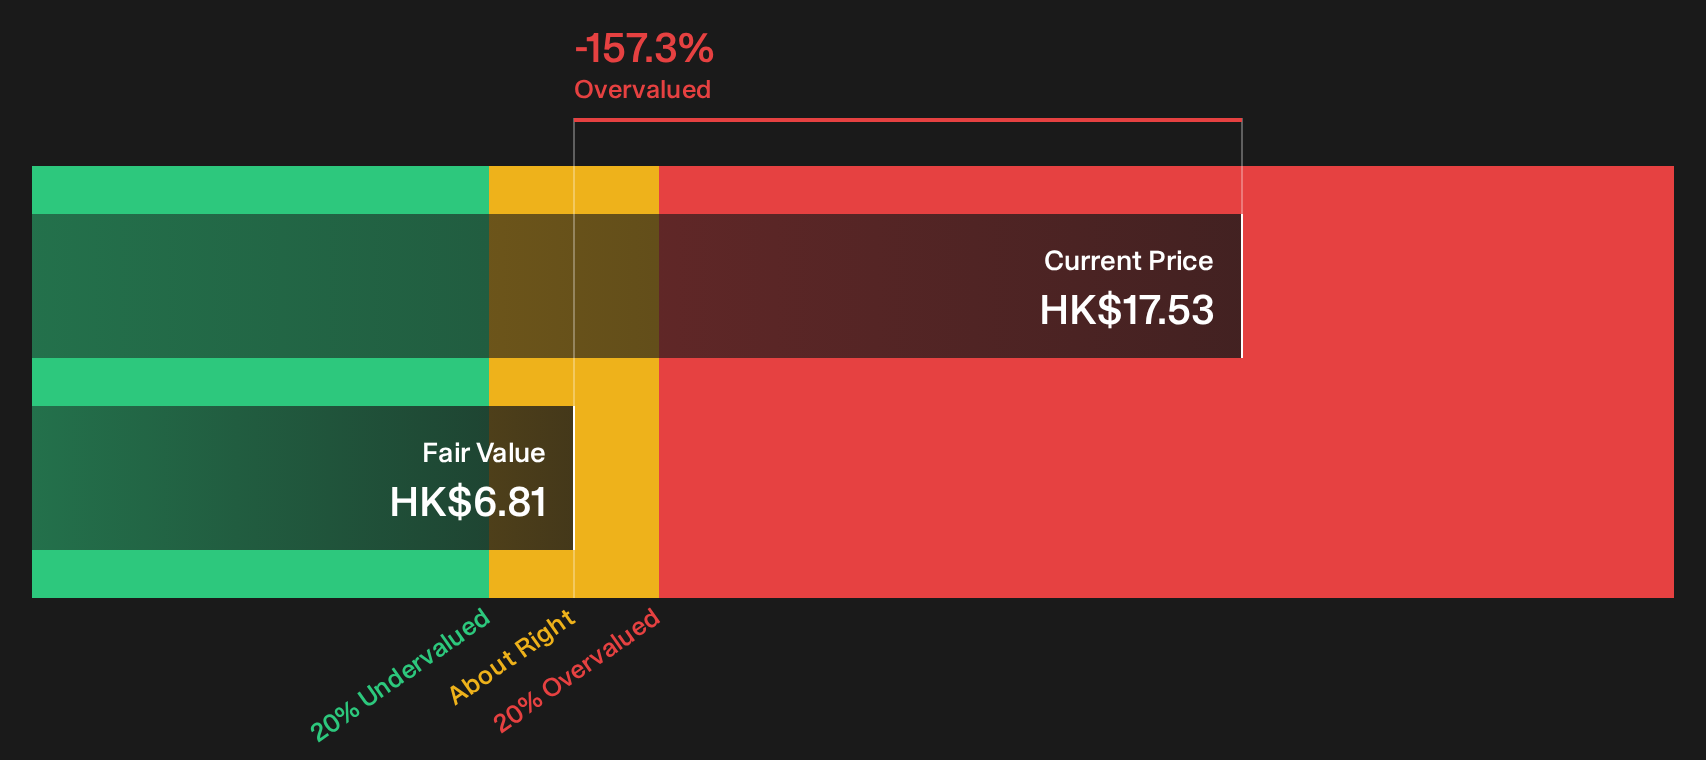
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out COSCO SHIPPING Energy Transportation for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on COSCO SHIPPING Energy Transportation’s value case are clear, so treat this as a prompt to examine the numbers yourself and consider acting before the market forms a consensus. To weigh both optimism and concern in one place, review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond COSCO SHIPPING Energy Transportation?
If COSCO SHIPPING Energy Transportation has your attention, do not stop at one ticker. Broaden your watchlist now so you are not late to the next move.
- Target potential mispricing by scanning a hand picked set of fundamentally strong opportunities through the 204 high quality undervalued stocks.
- Lock in income focused candidates by reviewing a curated pool of reliable payers via the 221 dividend fortresses.
- Shield your portfolio from fragile balance sheets by zeroing in on financially robust businesses with the list of solid balance sheet and fundamentals (199 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com