


Keyence (TSE:6861) Looks Fully Priced As Earnings, Dividend, And Split Draw Focus
Why Keyence’s latest board decisions matter now
Keyence (TSE:6861) has thrown several big headlines at investors at once, including a stock split tied to changes in its Articles of Incorporation and a richer interim dividend.
Those governance moves arrive alongside half year figures that show higher sales, net income, and earnings per share compared with the same period a year earlier.
Keyence’s governance and dividend moves are landing while the share price sits at ¥78,000, after a 2.15% 1-day share price return but a 30-day share price return that is down 3.94%. This hints that enthusiasm has cooled even as the year-to-date share price return of 36.41% and 1-year total shareholder return of 37.18% keep longer term momentum intact.
Scan how other automation and robotics players stack up against Keyence today by reviewing the hand picked 95 robotics and automation stocks that echo similar earnings strength and shareholder friendly moves.
Keyence has just paired rapid profit expansion with a richer dividend and a stock split at a trailing P/E of 34.8x. Is most of the rerating already in the price, or is it not yet reflected?
Price-to-Earnings of 34.8x: Is it justified?
Keyence is trading at a P/E of 34.8x, which is rich compared with both its sector and peer group, even after the recent share price cooling to ¥78,000.
The P/E ratio compares the current share price to earnings per share and helps you see how much investors are paying for each unit of profit. For a profitable automation specialist like Keyence, this metric often reflects how much faith the market has in future cash generation and the durability of its earnings profile.
On that score, there is a tension. Earnings grew 33% over the past year and have risen 10.3% per year over five years, and recent profit margins are reported at 40%. At the same time, forecasts point to earnings growth of 8.8% per year and revenue growth of 10.3% per year, which are not flagged as especially high, while the estimated fair P/E ratio is 23.2x. That suggests investors are currently paying a much steeper multiple than the level the market could move towards if expectations ease.
Compared with the JP Electronic industry average P/E of 15x, Keyence trades at more than double that level, and it also sits well above the peer average of 20.3x. The stock has also outpaced the broader JP market over the past year, while underperforming the Electronic industry, which adds further context to how much optimism is already reflected in this 34.8x earnings multiple.
Explore the SWS fair ratio for Keyence.
Result: Price-to-Earnings of 34.8x (OVERVALUED)
Still, the Keyence story could be tested if revenue growth near 10% softens, or if the stock’s P/E premium compresses toward industry levels.
Find out about the key risks to this Keyence narrative.
Another view on Keyence’s value
The P/E screen presents Keyence as expensive, and the SWS DCF model is even more conservative. At ¥78,000, the stock trades well above an estimated future cash flow value of ¥25,803.26. That indicates a wide gap between the market price and the modelled cash flows. Are investors paying significantly more for the narrative than the cash flows might support?
Look into how the SWS DCF model arrives at its fair value.
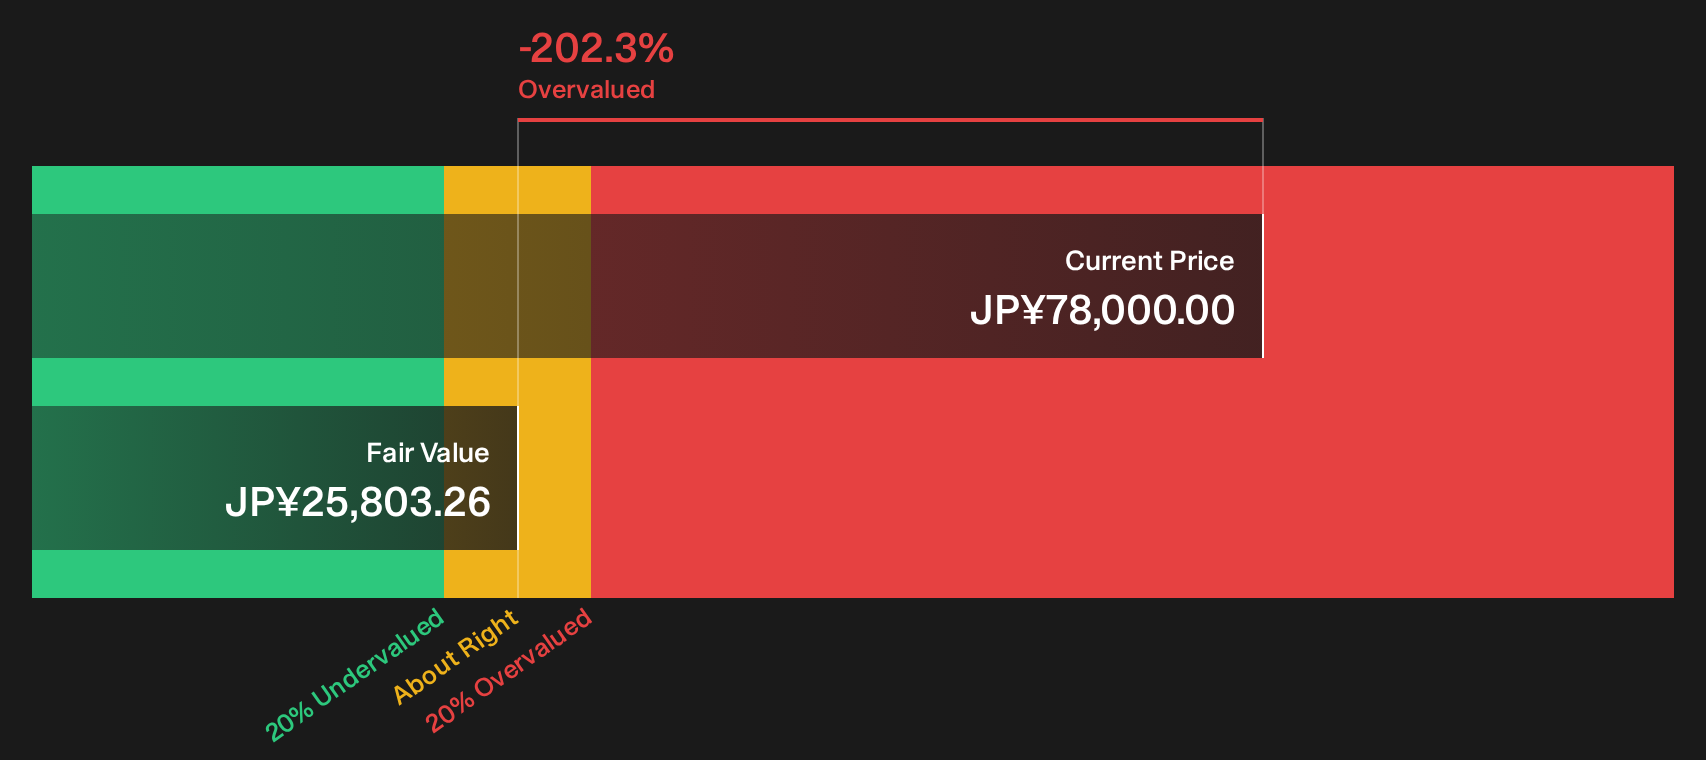
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Keyence for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the Keyence story feels finely balanced to you, that is the signal to move quickly, test the assumptions, and rely on your own judgement. To see why some investors still view the setup positively, review the 3 key rewards
Want more ideas beyond Keyence?
If Keyence has sharpened your focus on quality, do not stop here. The next decision you make on capital allocation could matter far more than this one.
- Upgrade the quality of your watchlist by scanning a curated 16 high quality undervalued stocks with strong fundamentals that the market may not be fully pricing in yet.
- Strengthen your income stream by checking a focused 28 dividend fortresses that highlights companies combining higher yields with resilient payout profiles.
- Calm the risk side of your portfolio by reviewing a targeted 23 resilient stocks with low risk scores built around resilient balance sheets and lower volatility profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com