


How Profit Miss At Lennox International (LII) Has Changed Its Investment Story
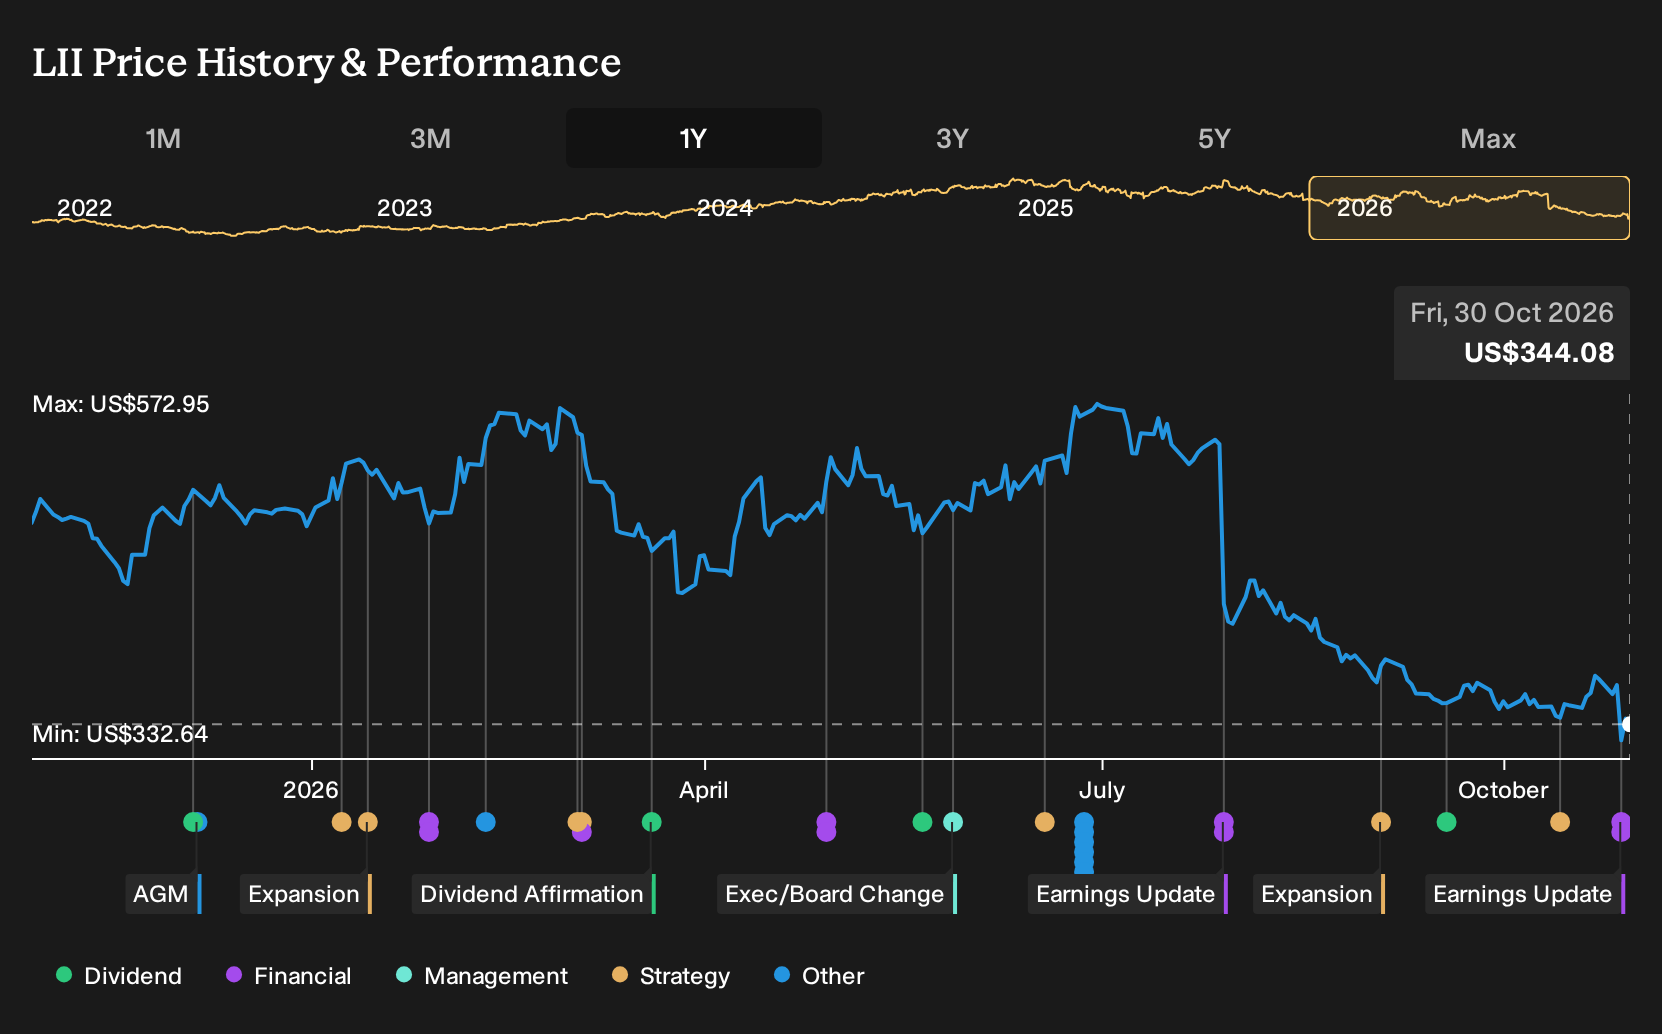
- Lennox International reported third quarter 2026 results with sales of US$1,572.5 million and net income of US$221.2 million, below the prior year despite higher revenue, and updated full year guidance to target about 6% revenue growth including a 5% contribution from acquisitions.
- The mix of stronger top line and softer earnings, driven by inflation, tariffs and margin pressure as Lennox International used more flexible pricing to protect residential share, highlights the trade off between defending volume and preserving profitability.
- The next area of focus is how Lennox International's softer earnings per share influences the existing investment narrative around margin expansion.
Compare Lennox International's margin pressures with peers by examining other industrials facing similar trade offs on pricing and profitability through the 29 resilient stocks with low risk scores
Lennox International Investment Narrative Recap
Lennox International appeals to investors who believe the HVAC market still supports steady equipment replacement, higher efficiency upgrades and an expanding parts and services ecosystem. That story relies on the mix tilting toward commercial systems, heat pumps and recurring revenue, while residential demand and factory utilization gradually become less of a drag.
The Q3 update, with revenue higher but earnings per share softer, keeps the near term focus on margins. The key short term catalyst is evidence that pricing tools and mix can rebuild profitability without losing share. The biggest risk is that weak homeowner demand and factory under absorption keep earnings under pressure for longer.
The most relevant update here is management’s revised guidance that points to about 6% full year 2026 revenue growth, with roughly 5% coming from completed acquisitions. That signals transactions are doing most of the work on the top line while the underlying operation deals with inflation, tariffs and softer homeowner activity.
For you as a shareholder, the question is how effectively Lennox International turns that acquired revenue into durable profit. Integration, pricing execution and cost control become central catalysts. If margins stay under strain despite the higher sales base, the existing risk around residential exposure and factory absorption does not ease and may stay in focus.
Lennox International's current earnings of US$788.5 million are projected by analysts to reach US$1.1b by 2029, implying an earnings increase of about US$311.5 million. They expect that result to line up with forecast revenues of US$6.6b in 2029, which would reflect an assumed 7.5% yearly revenue growth rate over the next few years.
Uncover how Lennox International's fair value indicates a 27% potential difference from its current price before investors re-rate Lennox International and close that gap.
Exploring Other Perspectives
One alternative view treats Lennox International’s long term margin target as the real lever. The most optimistic analysts were modelling revenue of about US$7.2b and earnings near US$1.2b by 2029 before this Q3 report, assuming higher segment profitability. You can now ask whether this earnings miss changes that story, or simply delays it.
Explore 3 other Lennox International fair value estimates, including one that suggests as much as 92% upside from the current price.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Lennox International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lennox International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lennox International's overall financial health at a glance.
Looking for more investment ideas beyond Lennox International?
If this Lennox International update has sharpened your view on risk, return and quality, use the Simply Wall St Screener to widen your watchlist with companies that better match your own tolerance for volatility, income needs and balance sheet strength.
- For investors who want potential upside without stretching on quality, consider companies flagged in our 19 high quality undiscovered gems. These pair solid fundamentals with quieter market attention.
- If capital preservation and steadier profiles matter most to you, focus on businesses highlighted in the 29 resilient stocks with low risk scores to see which stocks score well on resilience.
- Income focused readers who care about reliable cash returns can review the 5 dividend fortresses to spot higher yielding payers that still clear key financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com