


Is Raised Earnings Guidance Altering The Investment Case For Essex Property Trust (ESS)?
- Essex Property Trust reported third quarter 2026 revenue of US$492.69 million and net income of US$98.07 million, with earnings per diluted share from continuing operations of US$1.52, while also disclosing a nine month net income of US$266.72 million.
- The REIT raised its full year 2026 net income guidance to a range of US$5.62 to US$5.74 per diluted share and agreed to a US$19.25 million tenant settlement that also cancels US$8.7 million of claimed move out balances, highlighting both operational confidence and legal clean up costs.
- This section now examines how Essex Property Trust's higher full year earnings guidance could reshape the existing investment narrative around the stock.
Compare Essex Property Trust's updated guidance with peers by scanning a curated set of resilient real estate and income-focused stocks in our 29 resilient stocks with low risk scores for potential alternatives or complements.
Essex Property Trust Investment Narrative Recap
For Essex Property Trust, the core belief is that tight West Coast multifamily supply and tech driven demand in Northern California can support solid occupancy and rent levels across the portfolio. The raised 2026 net income guidance points to management seeing enough operational support to absorb softer conditions in Southern California and Seattle for now.
The short term swing factor remains how quickly weaker Los Angeles and broader Southern California performance stabilises relative to stronger Northern California trends. The biggest risk is that regional pressures, legal costs and interest expense keep profit margins under strain, limiting the benefit of any top line resilience reflected in the updated outlook.
The most relevant update here is the higher full year 2026 net income guidance of US$5.62 to US$5.74 per diluted share. That range, set after a period of lower net income year on year, reflects an expectation that underlying operations and cost control can support earnings against a backdrop of softer profit margins.
For you as a shareholder or potential investor, the raised outlook interacts directly with existing catalysts such as limited new supply in core markets and concentrated operations that target higher efficiency. The key question is whether those advantages and any tech driven strength in Northern California are enough to offset regional softness, legal settlement costs and interest coverage pressure.
Essex Property Trust's narrative projects US$2.1b revenue and US$453.3 million earnings by 2029. This implies 2.6% yearly revenue growth and an earnings increase of about US$39.5 million from US$413.8 million today.
Uncover why Essex Property Trust's fair value indicates a 13% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
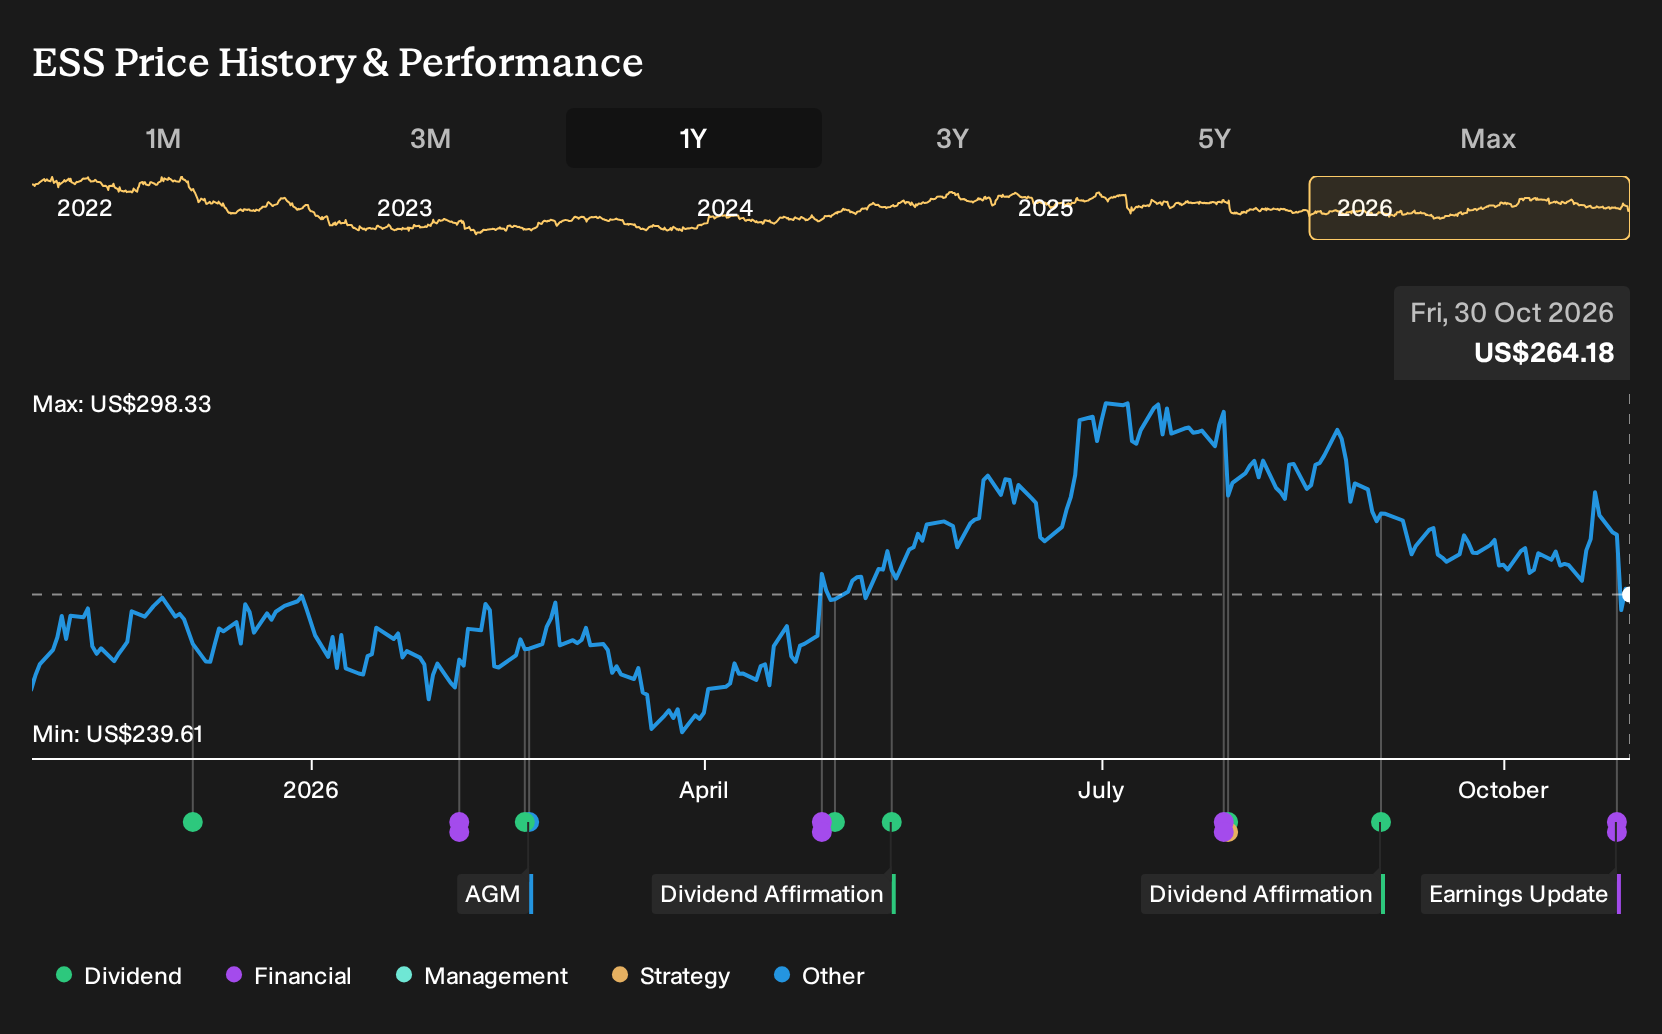
Two fair value estimates from the Simply Wall St Community span roughly US$298 to US$382 per share, which already shows how far apart retail views on Essex Property Trust can be. When you set those opinions against concentration in California and Seattle, softer Southern California conditions and the recent tenant settlement, you can see why investors hold very different expectations for future resilience. Explore several community viewpoints before forming your own stance.
Explore another Essex Property Trust fair value estimate, including one that suggests up to 44% potential upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Essex Property Trust research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Essex Property Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Essex Property Trust's overall financial health at a glance.
Looking For More Investment Ideas Beyond Essex Property Trust?
Once the Essex Property Trust story is clear, it can help to widen the lens and compare it with other opportunities that share some of the qualities you care about most, whether that is valuation support, balance sheet strength, or income potential.
- If valuation discipline is your priority, scan companies trading on what our models flag as attractive prices through the 33 high quality undervalued stocks.
- If balance sheet resilience matters more to you than headline growth, focus on businesses highlighted in the list of solid balance sheet and fundamentals (24 results).
- If reliable income streams are central to your plan, filter for higher yielding opportunities using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com