


How Higher Crude Prices Will Impact EOG Resources Stock
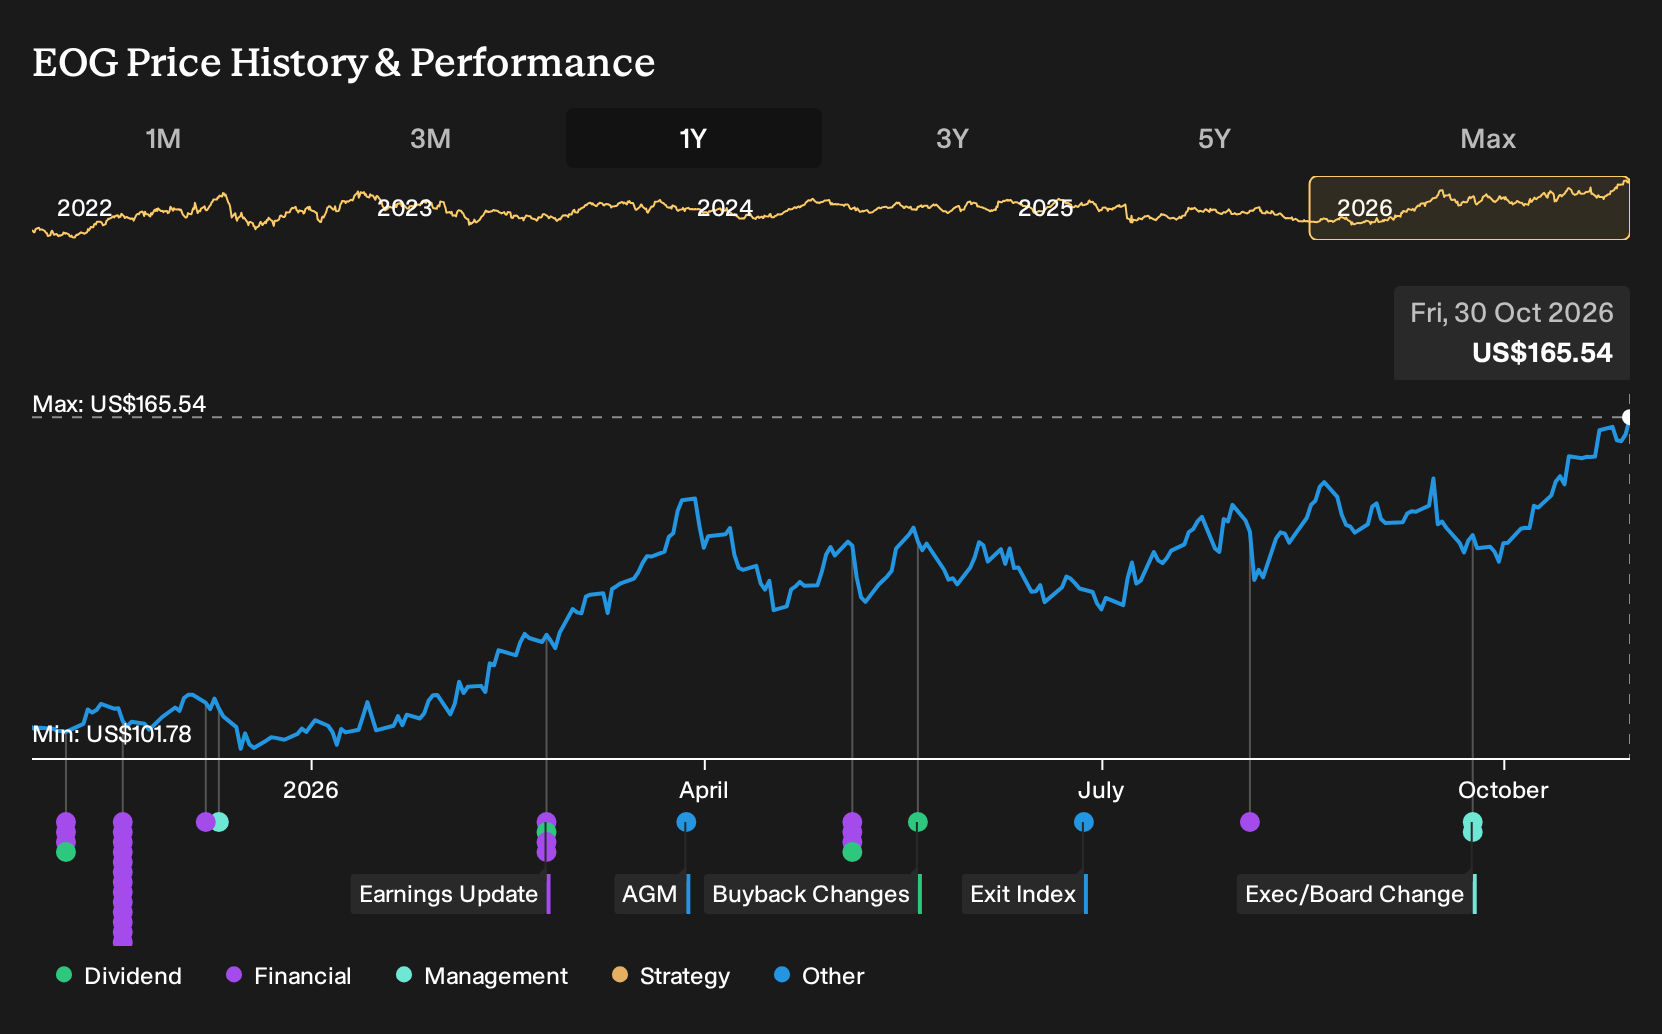
- EOG Resources reported that its third quarter 2026 results, released after the November 5 closing bell, were supported by productive shale assets and low-cost operations in a crude price environment influenced by the Middle East crisis.
- The update underscored how EOG Resources' combination of untapped high quality drilling inventory and a disciplined cost structure can shape earnings sensitivity to stronger commodity pricing.
- We will look at how EOG Resources' investment narrative is affected by third quarter earnings expectations tied to higher crude prices.
EOG Resources Investment Narrative Recap
To own EOG Resources, you need to be comfortable with a simple idea. The business is built around converting a large, low cost shale inventory into cash flow, while leaning on technology and infrastructure to keep unit costs in check when commodity prices move. The latest update around third quarter 2026 points to stronger crude prices as the key short term needle mover for earnings and cash generation.
The flip side is clear. Forecasts calling for revenue and earnings declines over the next three years highlight how dependent EOG Resources remains on pricing rather than pure volume growth. The immediate catalyst is how efficiently it turns this crude price window into cash. The biggest risk is that price support fades before new projects and LNG linked volumes fully prove their value.
One of the most relevant developments around this story is the push into premium gas markets through roughly 1 Bcf per day of LNG linked and other premium offtake contracts. This sits directly beside the current crude led upside and gives EOG Resources another pricing lever as more volumes from areas like Dorado and the Utica get placed into those channels.
These arrangements matter for catalysts and risk management. They can shape realized prices and cash flow per unit produced, especially as the firm builds out supporting infrastructure such as the Verde pipeline and the heavily utilized Janus gas plant. For you as a shareholder, execution on this marketing and infrastructure build is what will decide how much protection EOG Resources has if crude linked earnings momentum cools.
EOG Resources Earnings Expectations And Valuation Setup
Analysts sketch a fairly muted top line path for EOG Resources, with revenue described as remaining flat over roughly the next three years, while expecting profit margins to edge higher from 25.7% today to 27.0% by 2029. The sharper change sits in the bottom line. Consensus calls for earnings to move from US$6.9b today to US$7.2b by 2029, which is about a US$0.3b increase, even though there is a wide spread between the most optimistic and most cautious forecasts.
Valuation work in the latest reports hangs on that 2029 snapshot. To line up with the analyst framework, investors would need to assume that by 2029 EOG Resources produces about US$26.8b of revenue and US$7.2b of earnings, and that the stock trades on a P/E of 13.4x. This compares with roughly 12.0x on current earnings and a sector level closer to 12.5x. The share count is expected to shrink by roughly 3.33% per year over the next three years, so any assessment of per share value needs to factor in both that planned reduction and the discount rate of just over 7% that the research providers apply when pulling those future cash flows back to today.
EOG Resources' current analyst storyline points to forecast revenue of US$26.8b and consensus earnings of US$7.2b by 2029. This setup assumes relatively flat yearly revenue trends and an earnings increase of about US$0.3b from the current US$6.9b level.
Uncover why EOG Resources' fair value is essentially aligned with its current price.
Exploring Other Perspectives
One alternate view around EOG Resources leans heavily on Dorado as a long term gas engine, with bullish analysts penciling in revenue of about US$29.9b and earnings of US$8.6b by 2029 before this crude driven earnings update. You can read that as a much more optimistic story that may shift once the new numbers land. It can be useful to compare several narratives before deciding what makes sense to you.
Explore 3 other EOG Resources fair value estimates, including one that suggests up to 67% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your EOG Resources research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for EOG Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EOG Resources' overall financial health at a glance.
Looking For More Investment Ideas Beyond EOG Resources?
If the EOG Resources story has sharpened your thinking about risk, cash flow, and balance sheet strength, you can use that same lens across the wider market with the Simply Wall St Screener. Apply your preferred filters so you focus on opportunities that fit your approach instead of scrolling through endless tickers.
- If you care most about quality at a sensible entry point, filter for companies with strong fundamentals and reasonable pricing through the 33 high quality undervalued stocks.
- If capital preservation ranks high on your checklist, narrow the field to businesses with sturdier finances and fewer red flags using the 29 resilient stocks with low risk scores.
- If you want to start with financial resilience, scan for companies with cleaner leverage and healthier funding profiles by running the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com