


Why Everus Construction Group Stock Is In Focus Ahead Of Earnings
- Everus Construction Group is set to release its third quarter 2026 results on November 3 after market close, with consensus estimates pointing to earnings per share of $1.28 and revenue of $5.8 billion.
- The key operational story is ongoing demand for data center infrastructure, high tech manufacturing and power transmission work, which continues to shape Everus Construction Group's project mix and capacity allocation.
- This article examines how Everus Construction Group's upcoming earnings release and implied demand strength could influence its broader investment narrative.
See how Everus Construction Group fits into the broader buildout of power lines, factories and server capacity by comparing it with our hand picked 41 power grid technology and infrastructure stocks.
Everus Construction Group Investment Narrative Recap
To own Everus Construction Group, you need to believe large, complex electrical, mechanical and transmission projects tied to data centers, factories and power infrastructure stay busy enough to support its current project mix. The upcoming Q3 print mainly tests how well that story is holding together on the ground, especially across its Electrical & Mechanical and T&D segments.
The most important short term swing factor is how backlog and bid activity stack up against recent revenue levels, given concerns about lumpy awards and execution timing. The key risk is that data center and high tech manufacturing work slows or gets delayed, which would expose Everus Construction Group to margin pressure and less earnings momentum.
The Q3 2026 release on November 3 is the focal point now. Consensus sits at earnings per share of $1.28 on revenue of $5.8b. This provides a clean checkpoint against earlier periods where Everus Construction Group outpaced expectations on both lines. The update should help clarify whether recent demand in power transmission, data centers and industrial builds is holding.
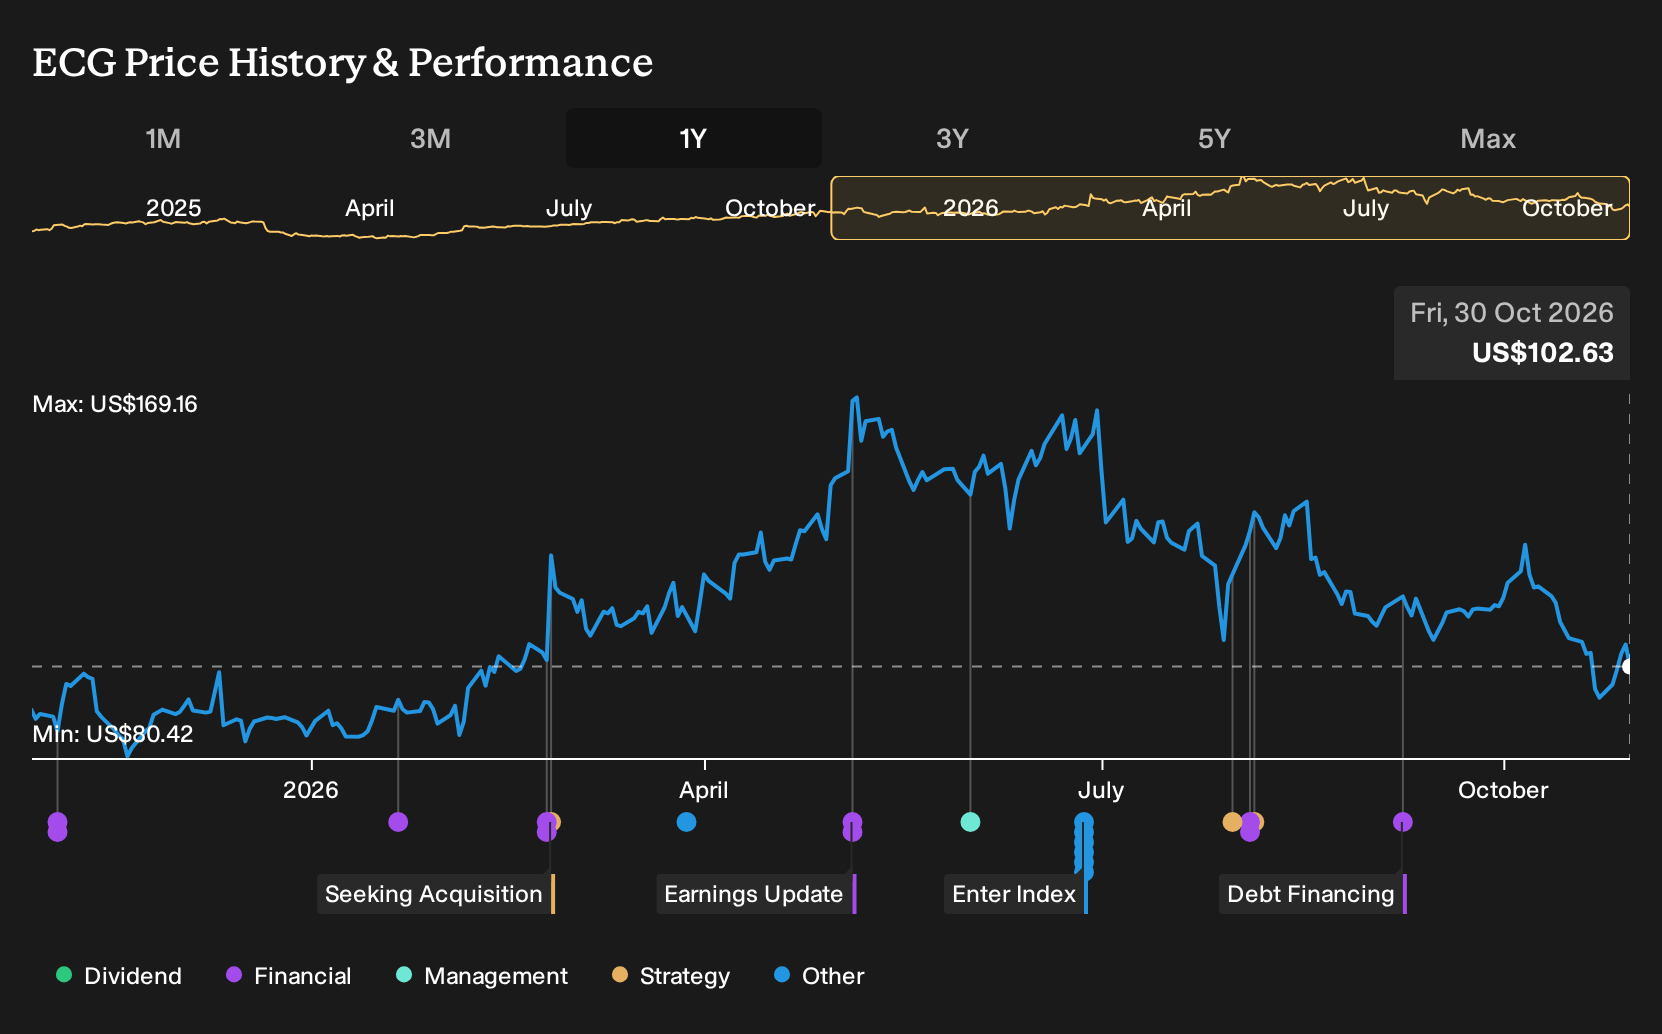
Another data point on investors radar is Argus lowering its target price for Everus Construction Group to $97. That shift does not change how the business executes projects, but it does serve as a reminder that sentiment can reset even when fundamentals such as a 32.9% return on equity and 6% net margin are still in place. For catalysts, the more important questions remain order trends, labor availability and how management is pacing capital toward future projects and potential M&A.
Everus Construction Group Long Term Expectations In Focus
Everus Construction Group's narrative projects $5.8b revenue and $351.1 million earnings by 2029. This implies 10.6% yearly revenue growth and an earnings increase of about $96.6 million from $254.5 million today.
Uncover why Everus Construction Group's fair value indicates a 73% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate angle on Everus Construction Group focuses on its record US$3.23b backlog as a potential upside catalyst. The most optimistic analysts were already penciling in about US$5.9b of revenue and US$337.8 million of earnings by 2029. You can treat Q3 as a reality check and explore whether those assumptions still feel reasonable once the numbers land.
Explore 3 other Everus Construction Group fair value estimates, including one that suggests as much as 95% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Everus Construction Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Everus Construction Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Everus Construction Group's overall financial health at a glance.
Looking For More Ideas Beyond Everus Construction Group?
Once you have a view on Everus Construction Group, it can help to compare that thesis with a few different types of opportunities using the Simply Wall St Screener.
- If you want potential income plus resilience, scan for companies that have a history of paying robust distributions with our 5 dividend fortresses.
- For investors who care most about financial strength and balance sheet quality, start with the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for lesser known opportunities with solid fundamentals, the 19 high quality undiscovered gems can surface ideas that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com