


Earnings Jump Might Change The Case For Investing In AMAG Austria Metall Shares (WBAG:AMAG)
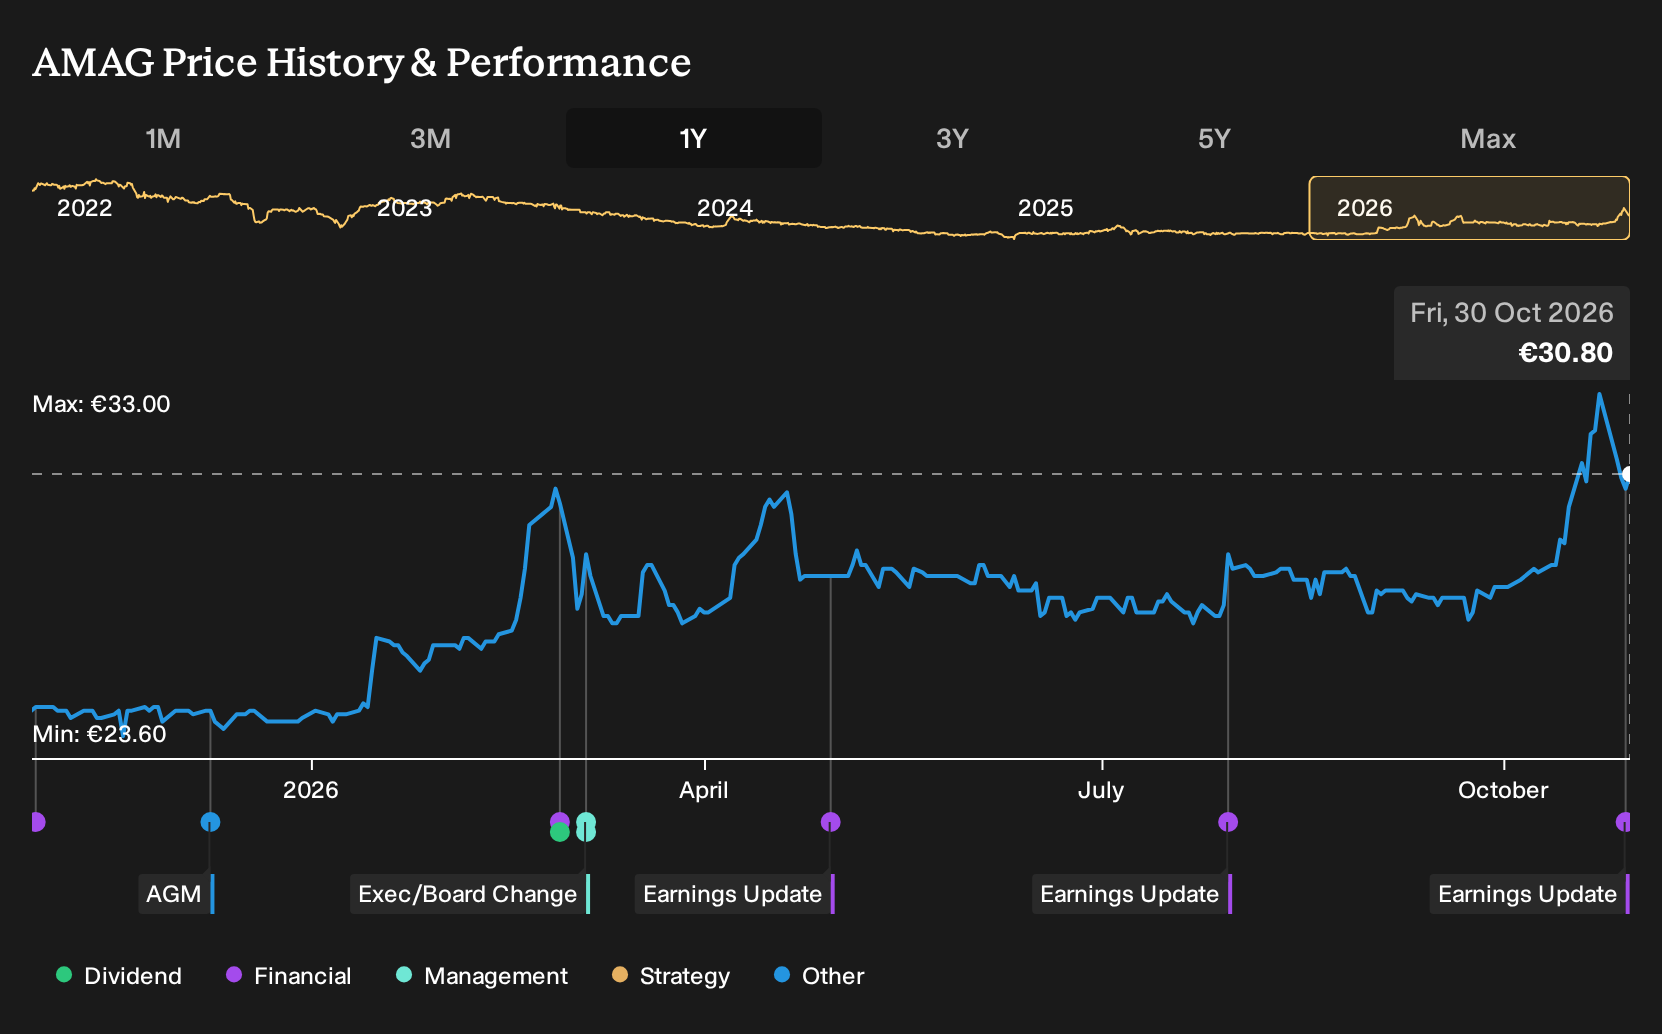
- AMAG Austria Metall reported third quarter 2026 sales of €472.7 million and net income of €41 million, with nine month figures of €1,323.4 million in sales and €81.7 million in net profit, all higher than the same periods in 2025.
- The sharp step up in profitability suggests AMAG Austria Metall converted higher aluminium pricing and product mix into stronger earnings rather than just higher revenue.
- We will now look at how AMAG Austria Metall's investment narrative could be influenced by this jump in quarterly net income.
Scan how AMAG Austria Metall's stronger earnings compare with peers by reviewing our curated 204 high quality undervalued stocks, which also pairs solid cash generation with resilient balance sheets.
AMAG Austria Metall Investment Narrative Recap
For AMAG Austria Metall, a core belief is that aluminium demand in premium segments and the firm’s recycling focus can sustain healthy utilisation and pricing. The latest quarter, with €472.7 million in sales and €41 million in net income, supports that idea on the earnings line. The near term swing factor is whether this earnings power holds as the product mix tilts toward higher margin applications.
The key risk still sits with cash conversion and leverage. Earlier in 2026, strong EBITDA sat alongside weak operating cash flow and rising net debt to EBITDA. The new numbers do not yet resolve that tension. They simply raise the bar for proving that profits can consistently turn into cash without stretching the balance sheet.
The most relevant context for this earnings jump is the earlier 2026 pattern. AMAG Austria Metall booked €850.7 million of revenue and just over €100 million of EBITDA in the first half, yet reported operating cash flow of minus €57 million. Free cash flow was minus €76 million after working capital and valuation effects linked to aluminium prices.
Set that against the strong third quarter, and the near term catalyst becomes clearer. Investors will likely focus on whether the profit uplift now coming through can ease those funding pressures, help stabilise net financial debt that had risen to 2.7x EBITDA by mid 2026, and still support ongoing spend on recycling technology and product development without further strain on cash generation.
AMAG Austria Metall's current earnings of €51.3 million are set against analyst forecasts for €72.6 million in profit by 2029, which implies earnings would need to rise by about €21 million. That profile sits on top of projected 2.8% yearly revenue growth and a revenue path that targets €1.7b in sales by 2029.
Uncover why AMAG Austria Metall's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You just saw AMAG Austria Metall post much stronger earnings, yet the most cautious analysts were sketching a very different story. They were pencilling in revenue of about €1.6b and earnings of €70.4 million by 2029, with only 1.7% annual sales growth. That group focused more on power costs, tougher competition and thinner pricing. Their forecasts came before this result, so some views may shift. Use this contrast as a reminder that opinions span a wide range and explore several angles before you decide what the latest numbers mean for you.
Explore another AMAG Austria Metall fair value estimate, including one that suggests it could be worth just €30.68.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AMAG Austria Metall research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AMAG Austria Metall. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMAG Austria Metall's overall financial health at a glance.
Looking for more investment ideas beyond AMAG Austria Metall?
Once you have formed a view on AMAG Austria Metall, it can help to line it up against other opportunities that match your risk profile and income needs. The Simply Wall St Screener lets you filter the market in a targeted way so you are not just reacting to headlines but comparing like with like.
- If you want potential income plus resilience, start with companies that combine robust payouts with balance sheet strength by scanning the 221 dividend fortresses.
- If capital preservation ranks high on your list, focus on businesses with steadier financial profiles by reviewing the 218 resilient stocks with low risk scores.
- For those hunting less crowded opportunities with solid fundamentals, widen your research set by checking the 614 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com