


T Mobile Stock Gains A Fresh Catalyst After Earnings Beat And T Mix Launch
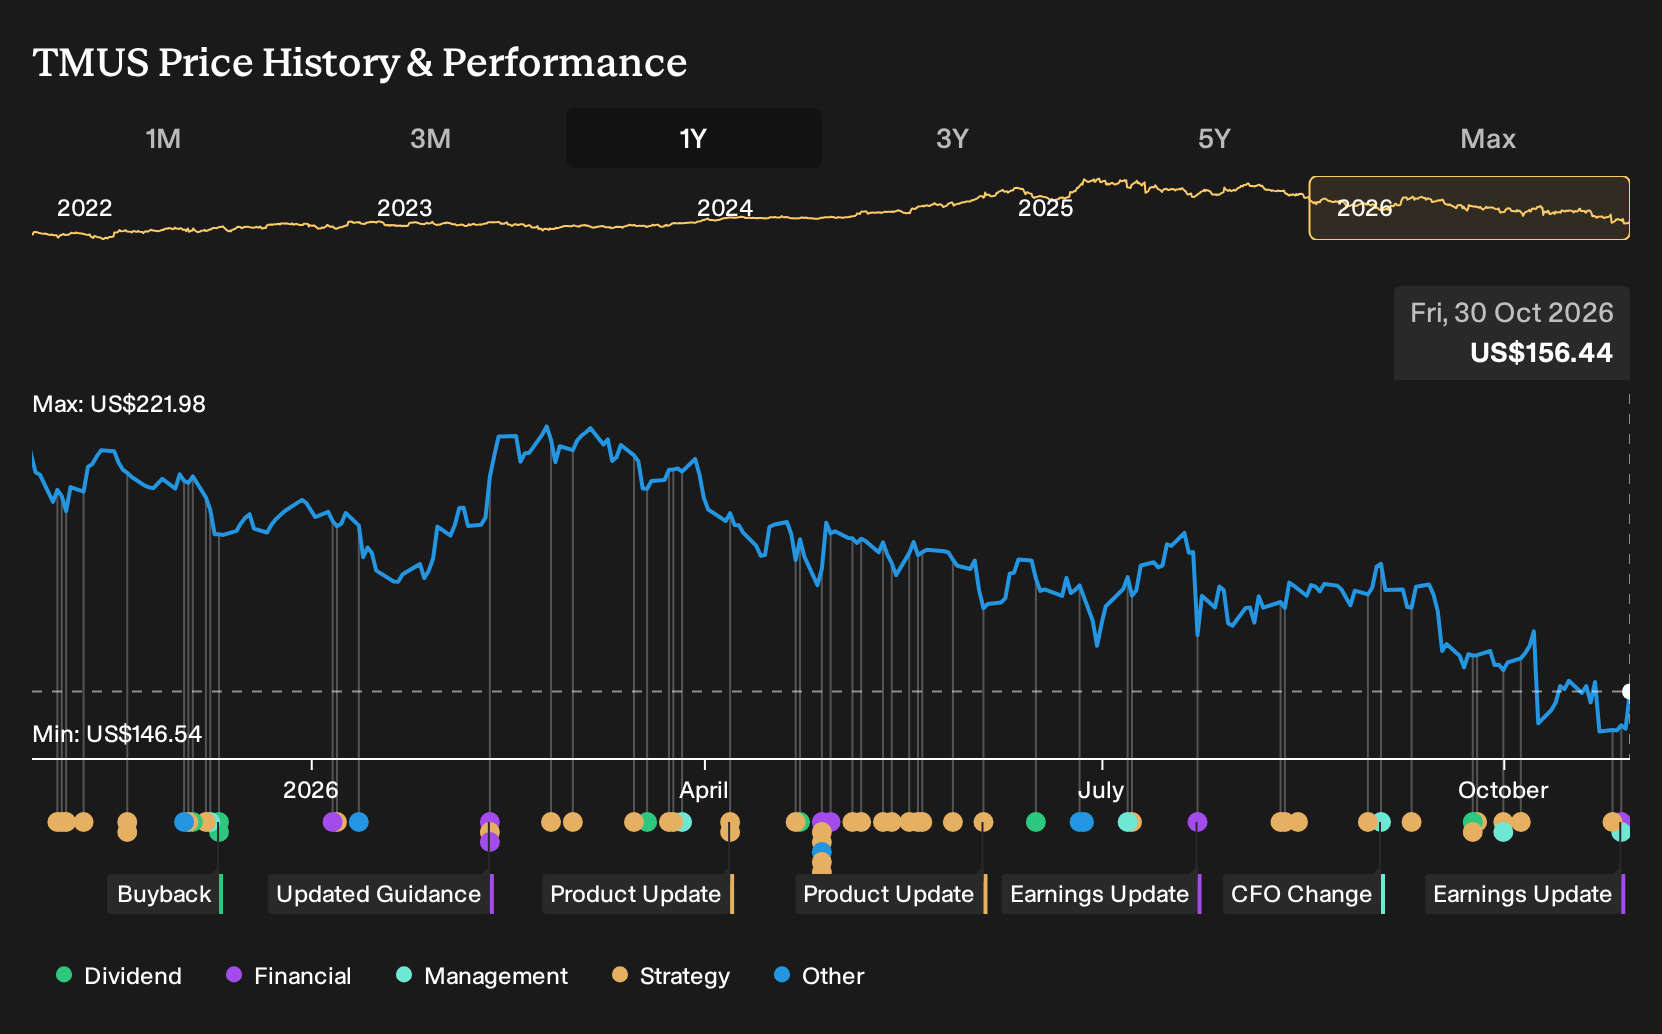
- T-Mobile US reported third quarter 2026 revenue of US$23,584 million and net income of US$3,455 million, while also rolling out its flexible T-Mix wireless plans and continuing sizeable share repurchases under its December 2025 buyback program.
- The T-Mix launch anchors a push toward higher value, more personalized plans at the same time as T-Mobile US is seeing higher postpaid churn and tougher competition from rival carriers and cable operators.
- We will now look at how T-Mobile US's investment narrative could be influenced by strong Q3 execution alongside the new T-Mix plans.
T-Mobile US Investment Narrative Recap
T-Mobile US is still a story about turning network, broadband and AI investments into higher value postpaid and home internet relationships while keeping churn contained. The latest quarter shows revenue of US$23,584 million and net income of US$3,455 million, which gives investors fresh evidence on execution against that thesis.
The short term swing factor is whether pricing and plan changes, including T-Mix, can stabilise postpaid account losses without heavier discounting. Rising churn and tougher competition from carriers and cable operators sit as the biggest risk. The Q3 results help, but do not remove that pressure.
The T-Mix launch is the announcement that sits closest to the current catalyst. It pushes T-Mobile US further toward premium, personalised plans, with Picks and tiered options like Standard, More and Loaded. That ties directly into the goal of lifting average revenue per account while trying to justify higher monthly bills.
For you as a shareholder, the operational question is whether T-Mix and related perks can offset churn linked to legacy plan changes and pricing. If customers embrace the flexibility and perceived value, that supports the existing broadband and 5G thesis. If they push back, competition and promotional intensity could stay elevated.
T-Mobile US' narrative projects US$105.5b revenue and US$18.2b earnings by 2029. This assumes 4.0% yearly revenue growth and an earnings increase of about 61% from US$11.3b today.
Uncover why T-Mobile US' fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle zeroes in on fixed wireless broadband as the real swing factor for T-Mobile US. The most optimistic analysts, who were pencilling in revenue of roughly US$106.4b and earnings of US$21.5b by 2029, saw broadband capacity and spectrum plans as the big upside driver. Those projections came before this Q3 and T-Mix update, so you may want to compare them with your own view and decide whether the latest earnings and churn signals nudge you closer to that bullish story or to something more cautious.
Explore 2 other T-Mobile US fair value estimates, including one that suggests upside of as much as 267% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your T-Mobile US research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T-Mobile US. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T-Mobile US' overall financial health at a glance.
Looking For More Ideas Beyond T-Mobile US?
If this T-Mobile US update has sharpened your view on the wireless space, it can help to set it alongside a wider watchlist of opportunities that match your risk, income, and quality preferences. The Simply Wall St Screener lets you do exactly that in a few clicks.
- If you want a starting point for potentially mispriced quality, you can filter for companies with strong fundamentals and room for sentiment to catch up using the 33 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter most to you, you can narrow your universe to businesses with cleaner finances through the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for less followed opportunities, you can broaden your research with the 19 high quality undiscovered gems that may not yet be heavily covered by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com