


First Busey (BUSE) Could Be 44% Below Fair Value After Third Quarter Results
Why First Busey’s Latest Quarter Caught Investor Attention
First Busey (BUSE) has put fresh numbers on the table after third quarter results and a clear move in credit costs, giving investors new data to weigh the banking stock.
Recent trading shows that enthusiasm around First Busey has cooled in the short term, with the share price down 2.24% on the day and 7.87% over 90 days. Even so, the year-to-date share price return of 20.54% sits against a 1-year total shareholder return of 33.75%. This suggests longer term holders have still seen momentum build, even as the market reassesses higher net charge-offs after the latest quarterly report.
Scan how First Busey stacks up against other banks facing similar credit trends by reviewing the hand-picked 29 resilient stocks with low risk scores. These banks combine resilience with more measured risk profiles.First Busey now trades below both analyst targets and an estimated fair value, even after the jump in net charge-offs. Is that discount mispricing caution, or simply reflecting it?
Preferred Multiple of P/E: Is it justified?
Valuation for First Busey hinges on what you think a fair P/E should be for a regional bank posting steady profit growth and a rising share price over the past year. The stock closed at $28.81, which equates to a P/E of 11.1x based on its current earnings profile.
The P/E ratio compares what the market is willing to pay today for each dollar of earnings. For a lender like First Busey, that matters because profit trends, credit quality, and dividend reliability all feed into what investors see as an acceptable earnings multiple.
Here, the picture is mixed. On one hand, First Busey is described as good value versus its peer average P/E of 16.6x and the broader US Banks industry at 11.3x. That points to the market putting a lower earnings tag on the bank than many rivals, even though earnings grew 117.2% over the past year and have risen 6.6% per year over five years while net profit margins improved from 15.3% to 25.8%.
On the other hand, the SWS fair P/E estimate for the stock sits at 10.8x, which implies the current 11.1x multiple is slightly above what that model suggests. That signals investors may already be baking some of the recent outperformance into the price, and the P/E could still gravitate toward the lower fair level if sentiment cools.
Explore the SWS fair ratio for First Busey.
Result: Price-to-earnings of 11.1x (ABOUT RIGHT)
Still, the recent rise in net charge-offs, along with any sustained cooling in First Busey’s share price, could quickly challenge the case for its current earnings multiple.
Find out about the key risks to this First Busey narrative.
Another View On First Busey’s Value
The picture changes once you look at First Busey through the SWS DCF model. At $28.81, the share price sits well below an estimated future cash flow value of $51.05, which points to the stock trading at a steep discount rather than a slight premium.
For investors, that gap suggests one blunt question. Is the market rightly cautious about slower forecast growth and bank risk, or is it underestimating the cash First Busey could return over time?
Look into how the SWS DCF model arrives at its fair value.
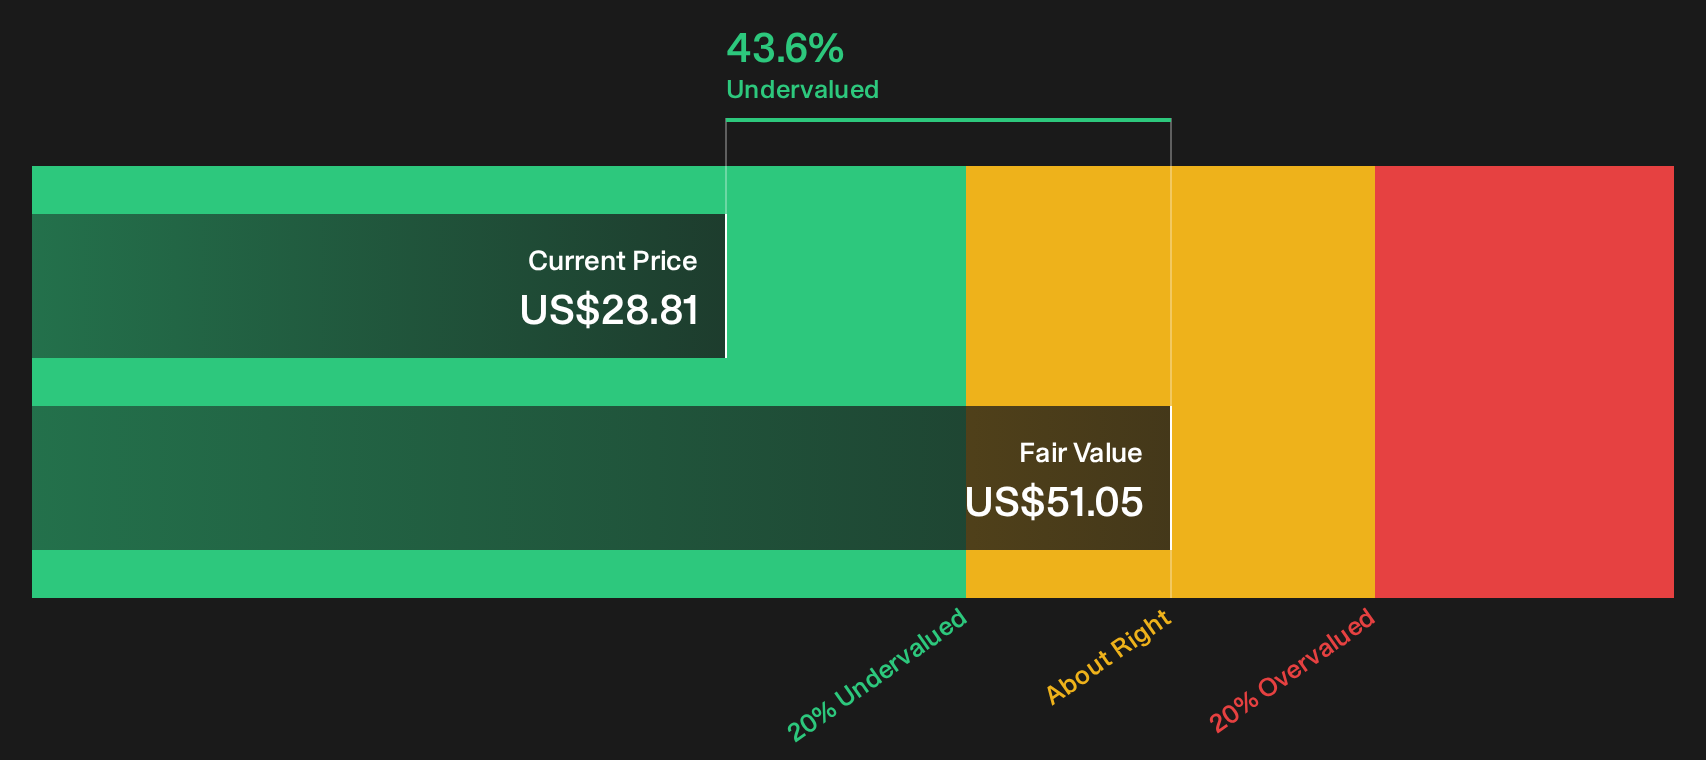
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Busey for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of discount, risk, and potential around First Busey feels finely balanced, treat it as a prompt to inspect the details yourself and move quickly before sentiment shifts. To see how the trade off of risk and reward stacks up in full, start with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond First Busey?
If you want a wider watchlist than First Busey alone, use the Simply Wall St screener to surface fresh ideas before the crowd catches on.
- Target dependable income by scanning companies that feature resilient payouts and higher yields with the 5 dividend fortresses.
- Hunt for quality at a discount by leaning on the 19 high quality undiscovered gems to spot strong fundamentals hiding in plain sight.
- Strengthen your downside protection by filtering for rock solid finances using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com