


Earnings Beat Could Be A Game Changer For Nucor Stock (NUE)
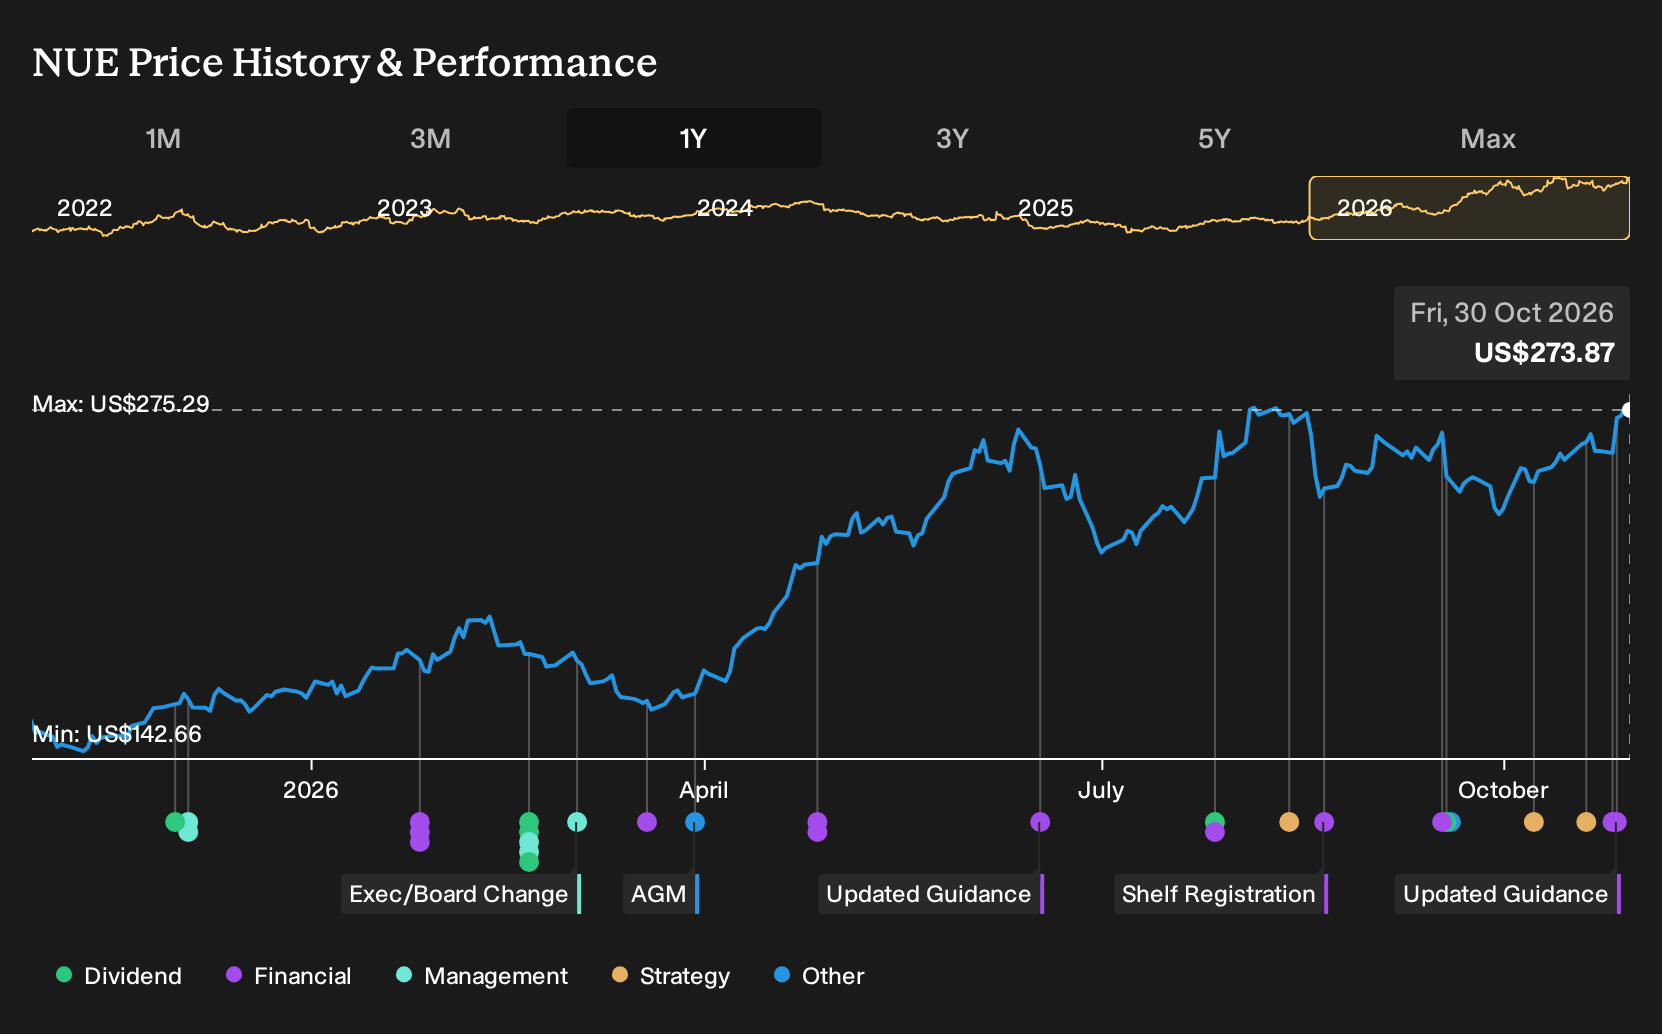
- Nucor reported third quarter 2026 sales of US$11,249 million and net income of US$1,319 million, with management guiding fourth quarter earnings to be in line with or modestly higher than the prior period.
- The producer is pairing this earnings strength with capital deployment on both sides of the balance sheet, including US$60 million for an Alabama utility infrastructure expansion and more than US$1.0 billion of share repurchases under its 2026 buyback plan.
- We will look at how Nucor's investment narrative is affected by strong third quarter earnings and the Trinity utility expansion project.
Scan how Nucor's earnings guidance and Alabama expansion fit into a wider set of steel and infrastructure plays by reviewing the hand picked 41 power grid technology and infrastructure stocks in one place.
Nucor Investment Narrative Recap
For Nucor, the key belief is that a vertically integrated steel producer with three segments (mills, products and raw materials) can keep turning a strong balance sheet and large capital program into consistent cash generation. The recent third quarter results and fourth quarter guidance for earnings that are in line with or modestly higher than the prior period point to operating stability as the short term catalyst.
The biggest risk still lies with execution and demand. Large projects like the West Virginia sheet mill carry start up and commissioning risk, while any weaker nonresidential or infrastructure spending could hit shipments. The latest guidance does not remove those issues, although it also does not materially worsen them.
The Trinity, Alabama expansion is the announcement that ties this all together. Nucor plans to invest US$60 million to increase output of steel poles and structures for utility infrastructure, adding jobs and new inspection capacity alongside the existing Decatur mill. That pushes the towers and structures business deeper into long dated power grid work.
For you as a shareholder, that matters because growth in towers and structures is one of the clearer catalysts in the story. It links directly to multi year infrastructure and energy projects, and to earlier commentary that these operations could contribute higher margin earnings once fully ramped. The main execution watchpoint is whether new capacity in Trinity scales smoothly without the kind of delays that could pressure group margins.
Nucor Earnings Framework Through 2029
Nucor's narrative projects US$40.6 billion revenue and US$4.5 billion earnings by 2029, based on analyst estimates that assume 1.5% yearly revenue growth and an earnings increase of about US$0.9 billion from US$3.6 billion today.
Uncover why Nucor's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate read on Nucor focuses on project risk rather than earnings strength. The most cautious analysts worry that big builds like West Virginia and towers and structures could outpace demand, which would cap returns on the US$15b to US$20b program. Their pre news forecasts pointed to about US$39.2b of 2029 revenue and US$3.8b of earnings. That is materially lower than the consensus view. Your takeaway is that opinions around Nucor differ widely, so this fresh guidance and the Alabama expansion may lead both camps to revisit their numbers.
Explore 3 other Nucor fair value estimates, including one that suggests it could be worth just $291.88.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Nucor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nucor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nucor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nucor?
If the Nucor story has sharpened your thinking and you want to widen the field, the Simply Wall St Screener can help you quickly filter other opportunities that fit your style, whether you care more about value, resilience, or yield.
- For investors who want potential bargains with strong fundamentals, scan a curated 33 high quality undervalued stocks that may warrant a closer look.
- If capital preservation and steadier profiles matter more to you than headline growth, focus your search using a 29 resilient stocks with low risk scores that scores well on resilience.
- When you care about robust finances as much as upside, start with a list of solid balance sheet and fundamentals (24 results) and build your watchlist from there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com