


Vertex Pharmaceuticals (VRTX) Reports Strong Phase 3 Kidney Data, Is The Stock Still Cheap?
Vertex Pharmaceuticals (VRTX) has drawn fresh attention after reporting positive Phase 3 RAINIER data for its kidney therapy povetacicept, with statistically significant IgA nephropathy results published in NEJM and showcased at ASN Kidney Week.
Vertex Pharmaceuticals has seen its positive kidney data land in a strong tape, with the share price up 17.18% over the past 90 days and 23.65% year to date. This has contributed to a 31.36% 1 year total shareholder return and a 189.89% 5 year total shareholder return, which point to sustained momentum rather than a short lived spike.
Capitalize on the momentum around Vertex Pharmaceuticals' kidney data by scanning a curated 34 healthcare AI stocks that could be setting up for their own breakout moments in the healthcare space.Vertex Pharmaceuticals now trades close to its recent highs after the kidney data surge. The real tension is whether to pay up today or wait for a pullback before the valuation starts to look stretched.
Most Popular Narrative: 2% Undervalued
Vertex Pharmaceuticals closed at $559.05, which sits a touch below the most followed fair value estimate of about $571.39 that is built on detailed pipeline and revenue mix assumptions. That small gap is where the kidney readout, Crinetics deal and non cystic fibrosis launches start to matter for anyone weighing today’s price.
The acquisition of Crinetics for about US$10b in cash, which adds the approved oral acromegaly therapy Palsonify and the Phase III ACTH receptor antagonist atumelnant in congenital adrenal hyperplasia and Cushing’s, is expected by management to reach more than US$5b in combined peak annual sales and to be accretive to non GAAP operating income by 2029. This can affect both revenue growth and net margins once integration and launch investments are absorbed.
See why 140 investors see Vertex Pharmaceuticals as 2% undervalued.
Result: Fair Value of $571.39 (UNDERVALUED)
Still, the story can break if cystic fibrosis pricing or volumes soften faster than expected, or if the Crinetics integration drags on cost and execution.
Find out about the key risks to this Vertex Pharmaceuticals narrative.
Another View On Vertex Pharmaceuticals’ Valuation
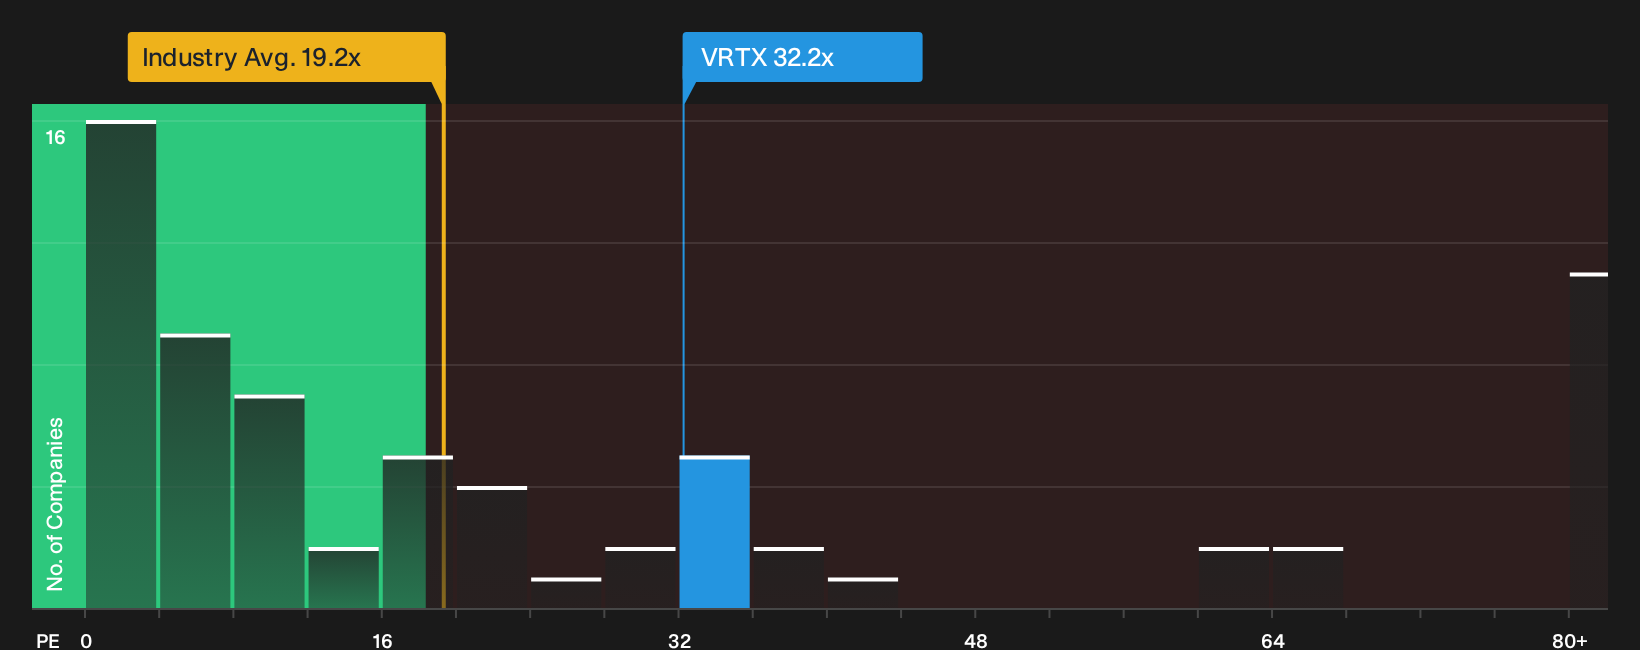
The story looks different once you zoom in on the P/E. Vertex Pharmaceuticals trades on 32.2x earnings, which is richer than the US Biotechs group at 19.2x, yet roughly in line with its own fair ratio of 32.5x and below a 60.3x peer average.
That mix sends a mixed signal. The share price carries a premium to the wider sector, but not to similar high growth peers. It also sits close to where the fair ratio suggests the multiple could gravitate. For anyone weighing position size, the real question is whether that premium feels like risk or room for quality.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the bullish tone around Vertex Pharmaceuticals but still on the fence? Move quickly to stress test the story against your own assumptions, and then weigh those 3 key rewards through 3 key rewards.
Looking for more investment ideas beyond Vertex Pharmaceuticals?
Do not stop with Vertex Pharmaceuticals. Broaden your watchlist today with fresh ideas that match your risk appetite, income needs, and balance sheet comfort zone.
- Target potential mispricing by scanning a focused set of quality bargains using the 33 high quality undervalued stocks.
- Build a sturdier income stream by reviewing companies in the 5 dividend fortresses.
- Dial back portfolio risk by concentrating on financially resilient businesses through the 29 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com