


TeraWulf (WULF) Expanded Its Credit Facility, Is More Upside Already Priced In?
Why TeraWulf’s Expanded Credit Facility Matters Now
TeraWulf (WULF) has reworked its senior secured revolving credit facility, lifting lender commitments to about $400 million and adding capacity for roughly $150 million more, while removing previous limits on letters of credit.
This financing update gives the bitcoin mining and digital infrastructure company broader access to bank funding, which can influence how investors think about TeraWulf’s capital needs, project pacing, and balance sheet risk.
For context, TeraWulf’s share price has been volatile, with a 1-day move down of 8% and a 30-day share price return down 24.27%. The 3-year total shareholder return sits at a very large gain of about 9.2x, so momentum has cooled from earlier gains even as this expanded credit facility reshapes how investors assess both funding capacity and risk appetite around the bitcoin mining build out.
Compare TeraWulf’s funding move with other high-conviction bitcoin and digital infrastructure plays by scanning our hand picked 18 cryptocurrency and blockchain stocks that are also emphasizing balance sheet flexibility.
After a 3 year total return of roughly 9.2x and a recent pullback, TeraWulf now sits at an interesting fork. Has the expanded credit line set up more upside, or was the real payoff already made earlier?
Most Popular Narrative: 64% Undervalued
The most followed valuation story around TeraWulf pegs fair value at $32.60, far above the last close at $11.73. This frames the credit facility expansion against an already optimistic long term setup built on contracted AI and data center demand.
TeraWulf's recent multi-billion-dollar, multi-year hyperscale hosting agreements (e.g., with Fluidstack and Google), mark a significant shift from a pure bitcoin mining model toward diversified, contracted revenue streams in high-demand digital infrastructure. This underpins higher revenue visibility and insulates earnings from bitcoin price volatility.
See why 149 investors see TeraWulf as 64% undervalued.
Result: Fair Value of $32.60 (UNDERVALUED)
Still, TeraWulf’s heavy capital needs and reliance on long term AI and data center tenants mean that delays, cost overruns, or tenant stress could quickly challenge that upbeat thesis.
Find out about the key risks to this TeraWulf narrative.
Another View: What Multiples Say About TeraWulf
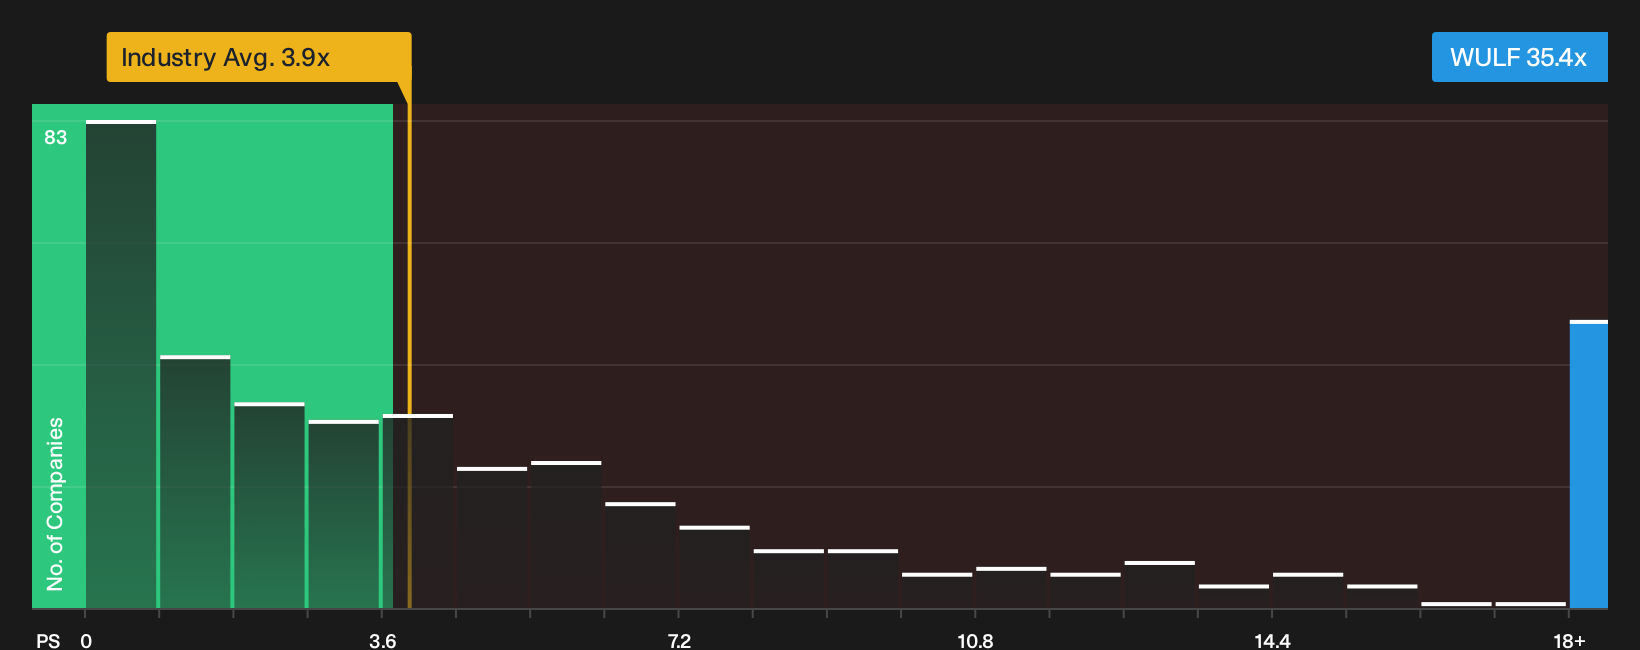
The fair value story for TeraWulf leans heavily on future contracts and earnings power. Look at today’s pricing though and the P/S ratio is 35.4x, versus 3.9x for the wider US Software group and 9.8x for closer peers. The fair ratio sits at 14.6x, which suggests a big valuation gap that could either compress sharply or take years to grow into. Which side of that trade are you really underwriting?
Before leaning on those contracts alone, it is worth checking how that kind of premium has played out across similar growth stocks in the past, and what the numbers imply for downside and upside if the market drifts toward the fair ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around TeraWulf’s valuation and funding can feel messy, so consider acting while the data is fresh and weigh both sides for yourself with 1 key reward and 4 important warning signs
Looking For More Investment Ideas Beyond TeraWulf?
If TeraWulf has you thinking harder about risk, reward, and timing, use this moment to scan fresh ideas before the next big move passes you by.
- Target potential mispricing by reviewing a curated set of quality opportunities through 33 high quality undervalued stocks that combine fundamentals with more grounded expectations.
- Strengthen income potential by focusing on reliable cash payouts using 5 dividend fortresses that highlight companies prioritizing consistent shareholder returns.
- Dial down portfolio stress by concentrating on sturdier businesses with 29 resilient stocks with low risk scores that screen for resilient financial and risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com