


Should Profit Drop Require Action From Lindab Stock Investors?
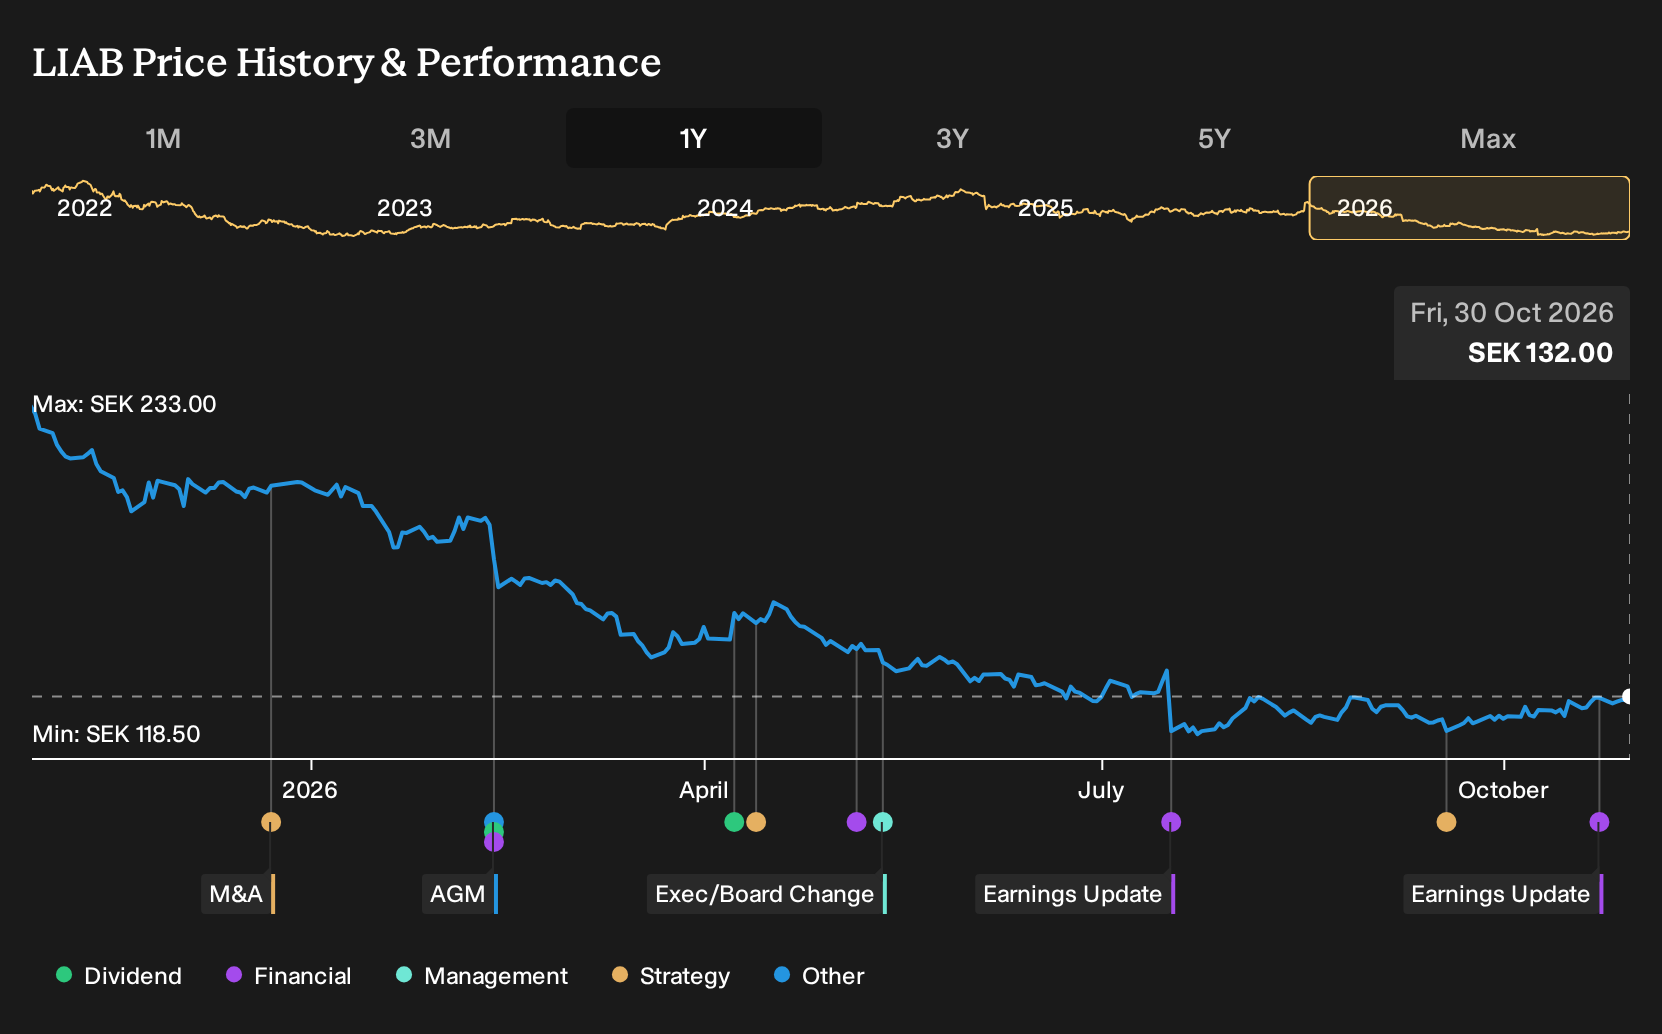
- Lindab International reported Q3 2026 sales of SEK 3,237 million, roughly in line with last year, while net income fell to SEK 187 million and basic earnings per share from continuing operations declined to SEK 2.42.
- The earnings release points to pressure on profitability rather than demand, with relatively stable revenue but materially weaker margins across both the quarter and year to date.
- We will examine how Lindab International's investment narrative is tested by sharply lower earnings, even though Q3 sales held broadly steady year on year.
Pressure test Lindab International's earnings story against peers and see which other industrials are holding margins steady with the hand picked 218 resilient stocks with low risk scores.
Lindab International Investment Narrative Recap
To own Lindab International, you need to believe that ventilation and building systems can still earn decent returns even when construction markets feel soft. The immediate story is about protecting profitability while sales stay broadly unchanged. The Q3 report, with SEK 3,237 million in revenue but much weaker earnings, puts that belief under stress and makes margin repair the key near term focus.
The main short term catalyst is whether cost measures and a shift in mix toward higher margin ventilation products start to show up in steadier earnings. The biggest risk right now is that flat European construction activity, combined with elevated transport and material costs, keeps squeezing margins longer than expected and slows any recovery in Profile Systems.
The Q3 2026 earnings announcement is the key release to focus on. It showed sales for the quarter and for the first nine months of 2026 broadly similar to the prior year, while net income and earnings per share declined sharply. That mix of stable top line and weaker profit highlights that Lindab International is wrestling more with cost and pricing than with volume collapse.
For catalysts, the question is whether existing efficiency programs in Ventilation Systems and the reshaping of Profile Systems can offset those pressures in coming quarters. If underlying demand for ventilation products holds while cost actions gain traction, earnings may stabilize from this lower base. If construction markets in core regions stay weak and input costs remain elevated, profitability may stay under pressure for longer.
Lindab International's narrative projects SEK 14.5b revenue and SEK 929.4 million earnings by 2029. This implies 4.4% yearly revenue growth and an earnings increase of about SEK 243 million from current earnings of SEK 686.0 million.
Uncover how Lindab International's fair value indicates a 7% potential upside to its current price before the discount to fundamentals narrows.
Exploring Other Perspectives
One alternate view leans hard into Lindab International’s higher value ventilation push. The most optimistic analysts were pencilling in revenue of about SEK 14.7b and earnings near SEK 1.3b by 2029, far above consensus. You can treat that as a stretch case that may be reconsidered after the Q3 2026 margin shock.
Explore 2 other Lindab International fair value estimates, including one that suggests there could be up to 99% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Lindab International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lindab International. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Lindab International's overall financial health at a glance.
Looking for more investment ideas beyond Lindab International?
If Lindab International has sharpened your focus on quality and risk, it can help to compare it with other companies that match clear financial filters. The Simply Wall St Screener lets you treat Lindab as a reference point while scanning for different mixes of balance sheet strength, income potential, or upside.
- If capital preservation is high on your list, start with companies that show resilient fundamentals through the 218 resilient stocks with low risk scores.
- For investors who want income on top of stability, use the screener to zero in on stocks that make the cut as 221 dividend fortresses.
- When you are hunting for quality at a reasonable price, it can be useful to compare Lindab International with a curated pool of 204 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com