


Does Third Quarter Earnings Change The Bull Case For Central Bancompany Stock (CBC)?
- Central Bancompany reported third quarter 2026 net interest income of US$218.86 million and net income of US$116.24 million, alongside net charge offs of US$3.55 million that were broadly similar to the prior year.
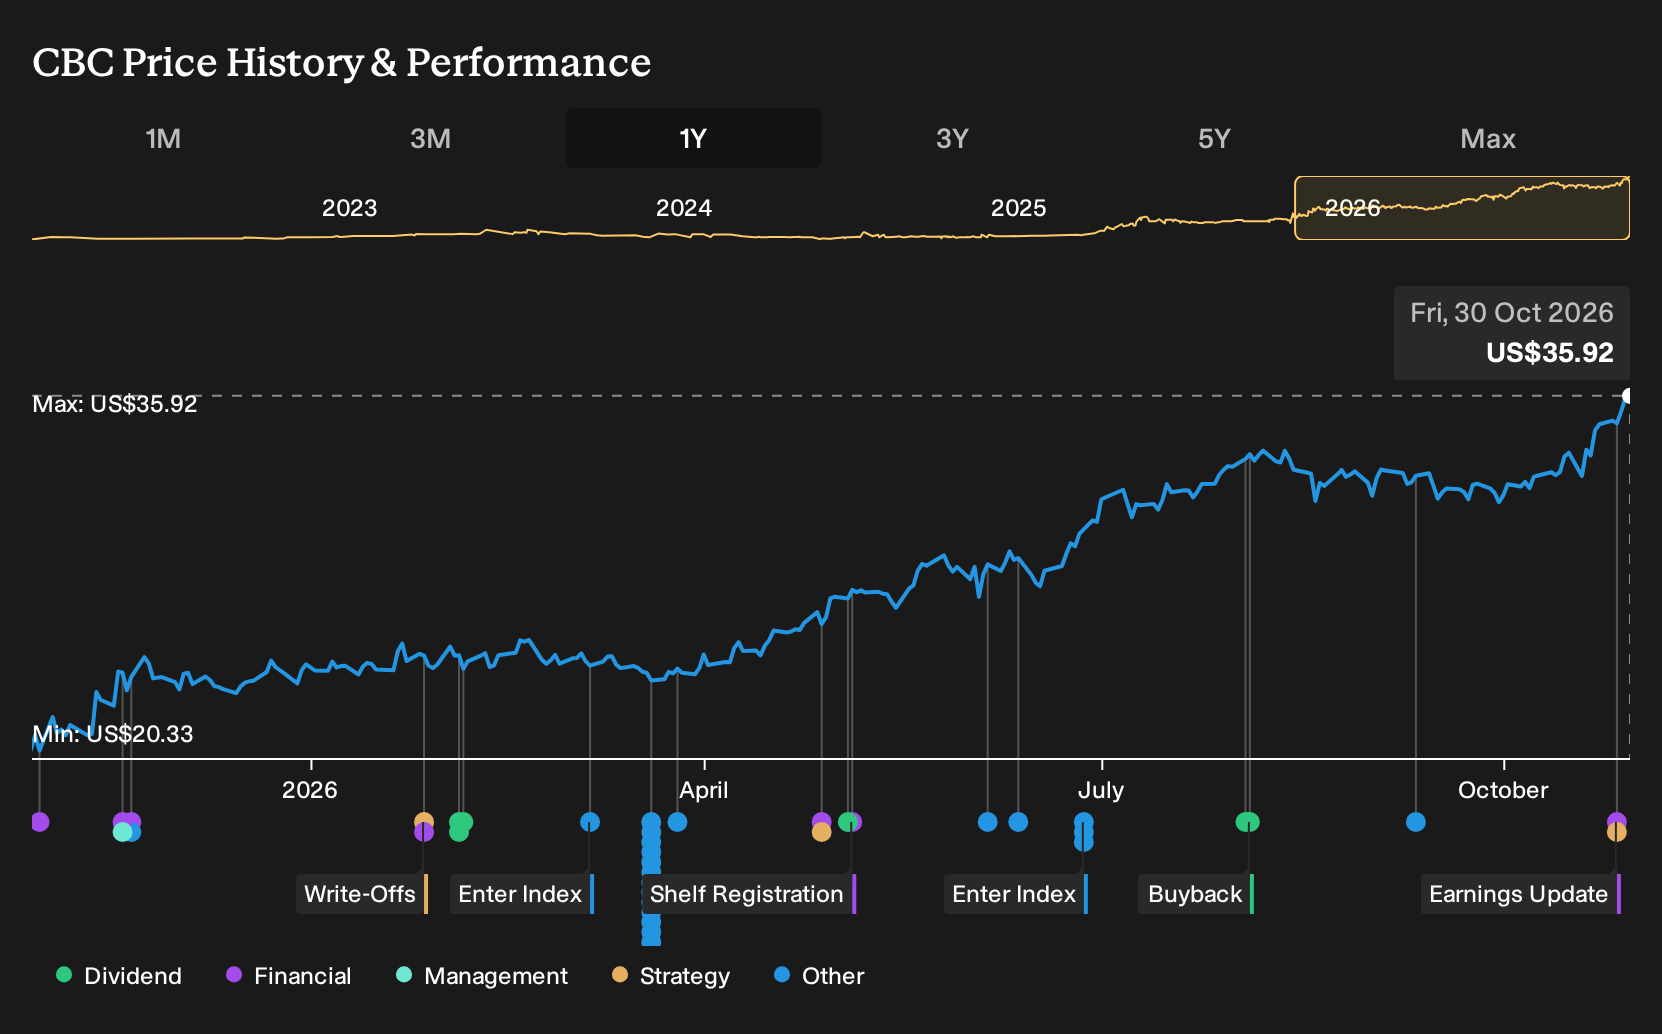
- The bank completed a US$3.8 million share repurchase tranche in late 2026, which reduces share count slightly and reflects ongoing capital deployment in the context of higher reported earnings.
- We will now assess how Central Bancompany's higher third quarter net interest income could influence the existing investment narrative around the bank.
Central Bancompany Investment Narrative Recap
To own Central Bancompany, you need to be comfortable with a story built on steady net interest income, disciplined credit and methodical capital use rather than rapid expansion. The latest quarter fits that pattern. Net interest income of US$218.86 million and net income of US$116.24 million signal an operating base that still leans heavily on spread income.
In the near term, the key catalyst is whether loan and deposit growth can sustain that higher run rate of interest income without eroding credit quality. Net charge offs of US$3.55 million, close to last year, keep that risk in check for now. On the risk side, branch expansion plans and excess capital still need productive deployment, but this specific quarter’s results do not materially change that equation.
The most relevant fresh data point is the third quarter net interest income and earnings print. Central Bancompany reported US$218.86 million of net interest income and US$116.24 million of net income, with diluted EPS from continuing operations at US$0.48. Those figures give you a cleaner reference point when weighing long term assumptions about revenue growth and profitability.
For catalysts, the interest income line is what ties the story together. Ongoing loan production priced at roughly 300 basis points over treasuries, supported by a funding base that includes Missouri public funds, is directly linked to whether this level of earnings can be sustained. If deposit costs or competitive loan pricing pressure that spread, the current earnings profile and use of Central Bancompany’s sizeable excess capital could look less flexible.
Central Bancompany's current narrative uses analyst expectations that revenues will reach US$1.3b and earnings will be US$526.1 million by 2029, based on 6.8% yearly revenue growth and an earnings increase of roughly US$96.8 million from the US$429.3 million reported today.
Uncover why Central Bancompany's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The Simply Wall St Community only shows two fair value views for Central Bancompany so far, with estimates between US$34.80 and about US$43.75 per share. That narrow sample still reflects how opinions can diverge. Set those crowd forecasts against rising net interest income, modest net charge offs and fresh buybacks, and then explore how others frame the same numbers.
Explore another Central Bancompany fair value estimate, including one that suggests it could be worth just $34.80.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Central Bancompany research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Central Bancompany. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Central Bancompany's overall financial health at a glance.
Looking for more investment ideas beyond Central Bancompany?
If Central Bancompany's mix of earnings, credit discipline and capital returns appeals to you, it can help to line it up against a wider field of potential opportunities using the Simply Wall St Screener.
- Prioritise resilience and balance sheet strength by checking companies in the list of solid balance sheet and fundamentals (24 results) that may better match your risk tolerance.
- Focus on value driven opportunities and see which businesses in the 33 high quality undervalued stocks align with your preferred combination of quality and price.
- If income matters most, scan for payout focused candidates through the 5 dividend fortresses and compare their profiles with Central Bancompany's approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com