


Tennant (TNC) Could Be 24% Undervalued On Its New P1 VAC Launch
What Tennant’s New P1 VAC Launch Means For Investors
Tennant (TNC) has rolled out the P1 VAC, its first autonomous robotic vacuum for commercial spaces, expanding its robotics line into soft-floor cleaning and opening a fresh product category for the business.
The P1 VAC combines autonomous vacuuming, dust mopping, and edge cleaning in a compact format aimed at improving cleaning consistency, productivity, and use of existing labor in offices, schools, healthcare facilities, and other high-traffic interiors.
Tennant’s launch of the P1 VAC lands after a tough stretch for the ticker, with the share price down 22.6% over 90 days and the 1 year total shareholder return declining 15.5%. This robotics expansion could help reset how investors view its long term potential.
Spot emerging cleaning automation plays alongside Tennant by scanning our hand picked 95 robotics and automation stocks that are focusing on robotics and autonomy for their next growth leg.Tennant’s shares have already reset after a rough year, yet the business is still investing in robotics and posting rising annual revenue and net income. Has most of the rerating already happened, or does valuation still leave room?
Most Popular Narrative: 24% Undervalued
Tennant’s most followed narrative anchors fair value at $87.75, compared with a last close of $66.44. This frames the current P1 VAC launch inside a wider robotics driven thesis that extends well beyond a single product cycle.
Accelerated adoption of autonomous mobile robots and equipment-as-a-service programs is still expanding Tennant's potential recurring revenue base. The company now targets robotics revenue of about US$250 million in 2028, supported by 10 planned product launches and recent 56% year-over-year growth in first half 2026 robotics sales, which is likely to matter most for long-term revenue and earnings quality.
See why 12 investors see Tennant as 24% undervalued.
Result: Fair Value of $87.75 (UNDERVALUED)
Still, Tennant’s ERP rollout issues and rising competition from lower priced Asian robotics peers could both undercut the robotics thesis that investors are leaning on.
Find out about the key risks to this Tennant narrative.
Another View On Tennant’s Valuation
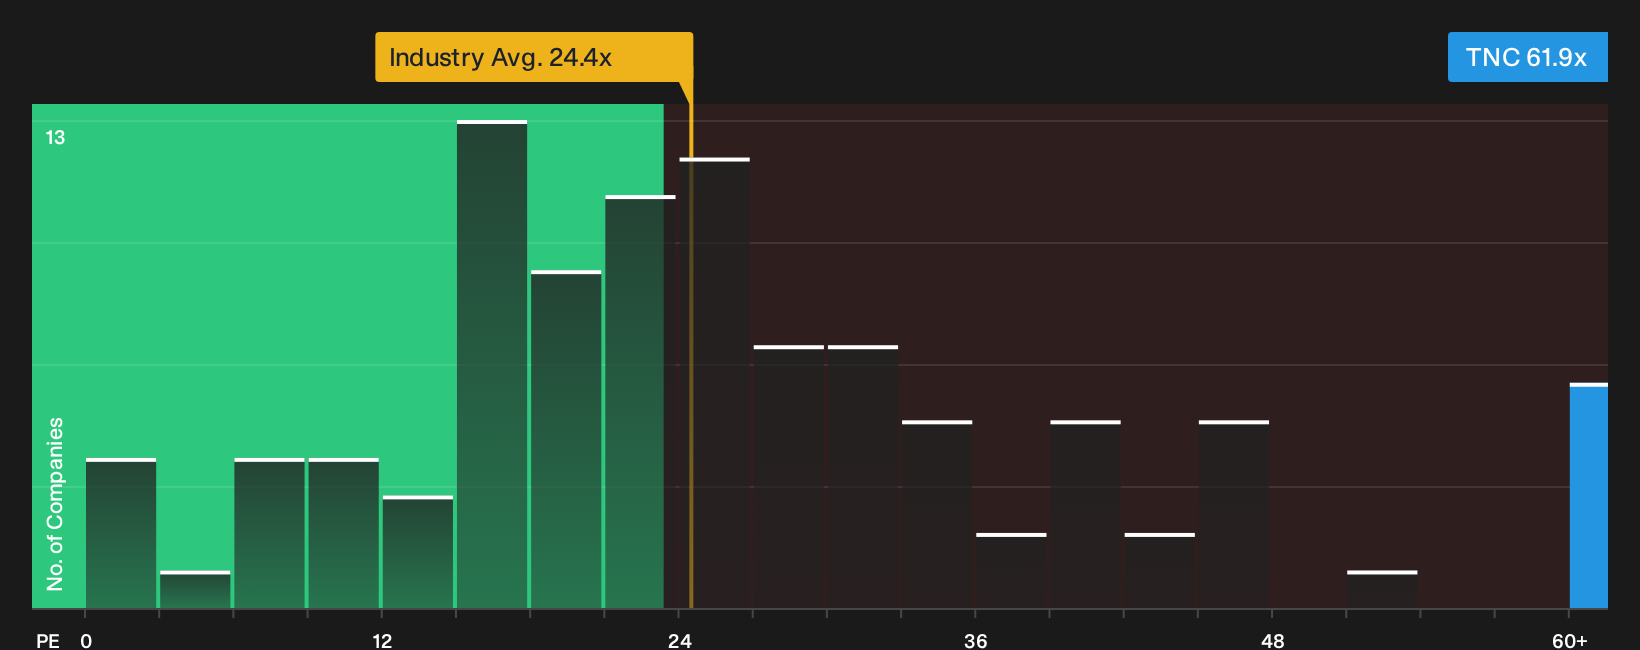
The most popular Tennant narrative leans on future earnings power and a fair value of $87.75. Yet the current P/E of 61.9x is higher than the estimated fair ratio of 54.2x, the Machinery industry on 24.2x, and peers at 27x. This points to real valuation risk if expectations slip.
To see how this rich earnings multiple could adjust over time, and what the numbers imply for potential re rating risk or opportunity, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Tennant story today, with both risks and rewards in play, mean the next move rests with you. Stress test the data, pressure check your own assumptions, and then ground your view in the 3 key rewards and 4 important warning signs.
Looking for more Tennant style investment ideas?
If you want a clearer view of how Tennant compares with other opportunities, use this moment to widen your lens. Fresh ideas now can matter more than small price moves.
- Zero in on quality at a discount by scanning our hand picked 33 high quality undervalued stocks that combine strong fundamentals with prices that lag their underlying business strength.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (24 results) so you are not caught off guard when conditions get tougher.
- Get ahead of the crowd by checking 19 high quality undiscovered gems that many investors have not focused on yet but still show robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com