


Nu Holdings (NU) Faces A Banking License Test As Its Undervalued Narrative Gets Harder To Trust
Nu Holdings (NYSE:NU) is back in focus after Brazil's central bank told the fintech to obtain a full banking license by 2026. The move raises fresh questions about regulation, capital needs, and long term profitability.
That regulatory twist lands on a stock that has already been under pressure. Nu Holdings’ share price has fallen 3.65% over the last day and 23.42% over the past week, contributing to a 31.79% decline year to date, while the three year total shareholder return is still positive at 36.91%. Political worries in Brazil after President Lula’s reelection, concerns about credit quality under prolonged high interest rates, and the recent resignation of the Chief Technology Officer have all contributed to a weaker 1 year total shareholder return of 27.93% and a fading near term share price trend as investors reassess both growth potential and regulatory risk.
Compare Nu Holdings’ regulatory and political risk mix with a hand picked group of bank and fintech stocks that currently screen as 29 resilient stocks with low risk scores.
After a drop like this, either Nu Holdings now offers meaningful upside or the best phase of the story already sits in the rearview mirror. The valuation section is where that tension really shows up in numbers.
Most Popular Narrative: 49% Undervalued
Nu Holdings last closed at $11.61, while the most followed narrative pegs fair value at $22.74 using a 13% discount rate. That gap frames a thesis built on earnings growth, high margins, and a compressed valuation that the market has not fully embraced.
The first is that Nu Holdings is currently trading at a historically low multiple relative to its growth profile. At $12.20 per share, the market is assigning it a 2026 forward P/E of just 13.7x based on an estimated earnings per share of $0.89, for a company growing that same earnings figure at roughly 48% annually. The 36% decline from its January highs ($18.98) has been driven by higher credit loss provisions in the first quarter and macroeconomic deterioration in Brazil, not by any change in the quality of the business model. That potentially creates an attractive entry window.
See why 108 investors see Nu Holdings as 49% undervalued.
Result: Fair Value of $22.74 (UNDERVALUED)
Still, Nu Holdings faces clear swing factors, including a tougher Brazilian credit cycle and any setback in winning or using a full banking license.
Find out about the key risks to this Nu Holdings narrative.
Another View on Nu Holdings’ Valuation
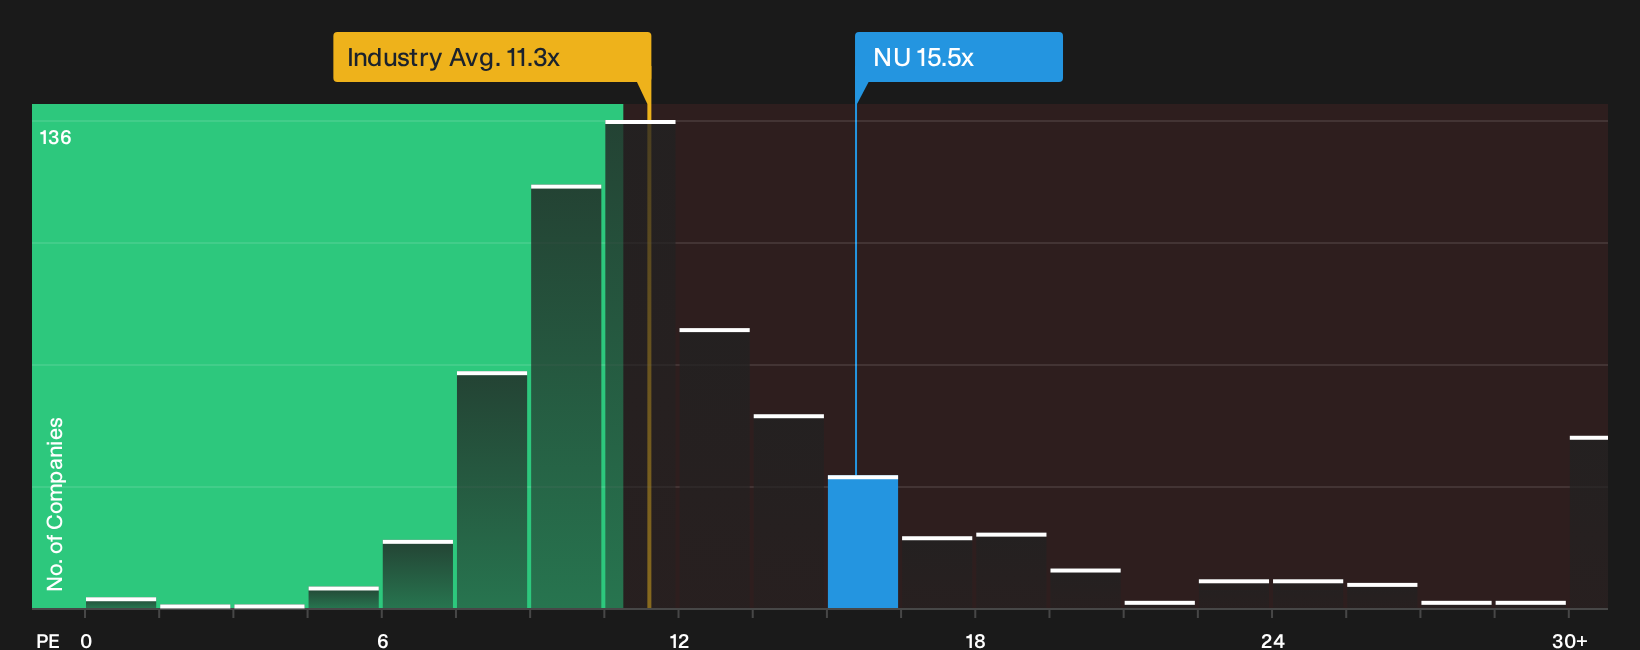
Multiples tell a different story. Nu Holdings trades on a P/E of 15.5x, which is richer than both the US banks sector at 11.3x and its peer group at 14.2x, yet still below a fair ratio of 17.5x that our work points to. Is that a measured premium or valuation risk building up?
That is where a closer look at the earnings-based valuation comes in. This is also where our fair ratio work steps in as a cross check on headline multiples, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Still undecided about Nu Holdings after all this, or already leaning strongly one way? Move quickly to pressure test that view against the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Nu Holdings?
If Nu Holdings has sharpened your view on risk and reward, use that same lens to scan other opportunities where quality, valuation, and resilience line up.
- Target resilient balance sheets and steady fundamentals by running your own shortlist through the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential mispricings by checking the 19 high quality undiscovered gems before the broader market pays attention.
- Lock in income ideas by filtering for reliable payers using the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com