


Vivendi (ENXTPA:VIV) Could Be 23% Undervalued As Revenue Growth Improves
Why Vivendi stock is back in focus
Vivendi (ENXTPA:VIV) is back on investors’ radar after unaudited figures showed third quarter revenue of €77 million, up 13.8%, with nine month revenue reaching €217 million, up 2.1% year on year.
That revenue update has coincided with a sharp shift in sentiment around Vivendi, with the share price up 6.9% over the last day and posting a 14.4% 30 day share price return. However, the 1 year total shareholder return is still down 46.9% and longer term performance remains weak.
Scan beyond Vivendi's rebound and line up other potential turnaround stories with the hand picked 204 high quality undervalued stocks that currently combine solid cash flows with stronger balance sheets.
Vivendi has posted improving revenue figures and a sharp short term share price bounce. The real tension now is simple: Does that recent optimism already reflect what this business is worth today?
Most Popular Narrative: 19% Undervalued
Vivendi’s most followed valuation storyline puts fair value at €2.01 per share, above the last close of €1.63. This raises a simple question about whether the recent rebound has gone far enough or not.
The current valuation implies the share price does not fully reflect Vivendi’s reduced net financial debt, improving profitability metrics and income from a roughly €5.5b listed portfolio. This narrative views the stock as undervalued and maintains a positive stance.
See why 11 investors see Vivendi as 19% undervalued.
Result: Fair Value of €2.01 (UNDERVALUED)
Still, the Vivendi story can break if Gameloft’s PC and console pivot stalls, or if swings in the €5.9b listed portfolio cut earnings support.
Find out about the key risks to this Vivendi narrative.
Another View: Vivendi looks pricey on earnings
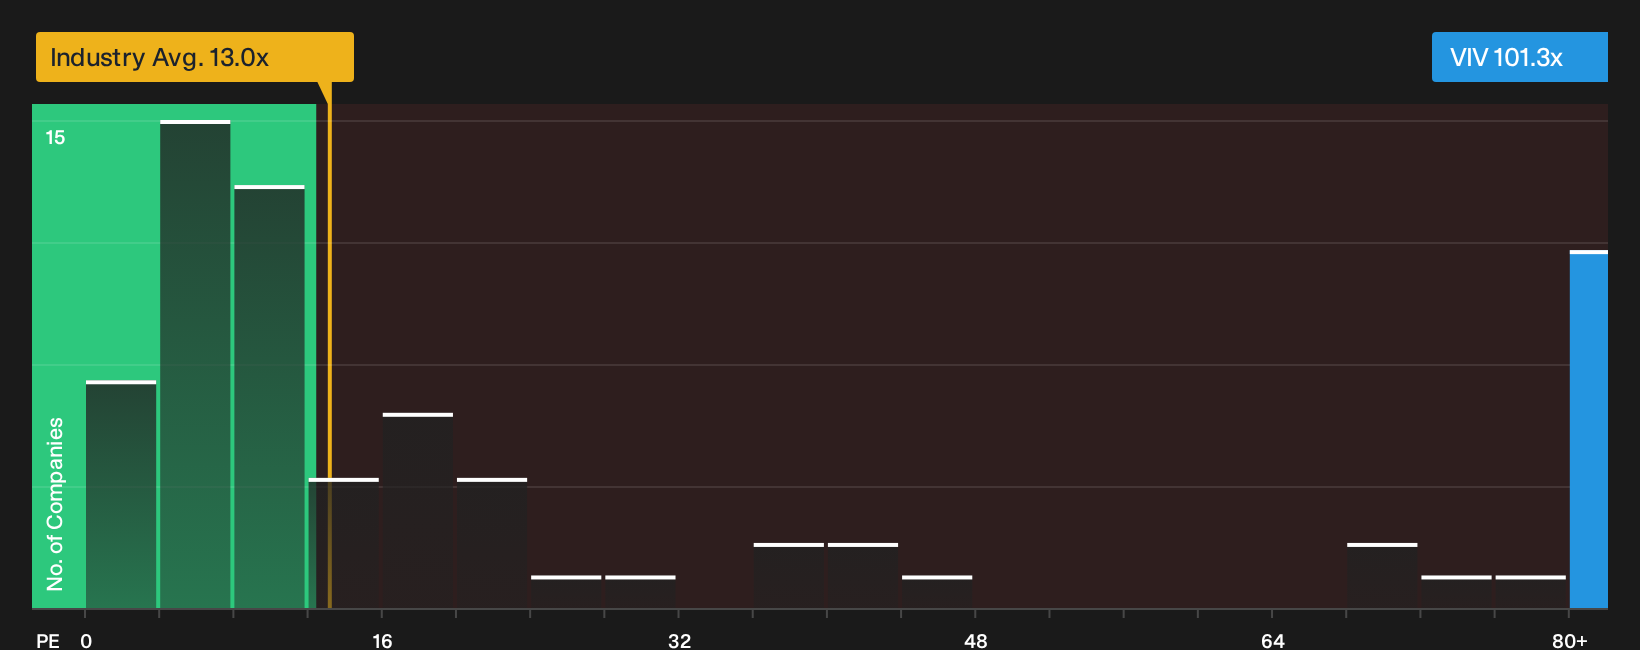
The first storyline leans on a fair value of €2.01 per Vivendi share, yet the current market is assigning a P/E of 101.3x. Peers closer to 27.4x and a fair ratio of 35.9x suggest investors are paying a steep premium for these earnings.
That gap can cut both ways. If profitability does not build as expected, a move toward the 35.9x fair ratio or the 13x European Entertainment average P/E would mean a lot of valuation risk packed into today’s price.
Before leaning on any single metric, it helps to see how this premium stacks up against other opportunities in the market, and where the numbers point to richer or leaner pricing overall, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Vivendi story so far. If you want to move quickly and judge the balance of risks and rewards for yourself, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Vivendi?
If Vivendi has your attention, do not stop here. Broader opportunities rarely wait around for long, and missing them can cost real upside.
- Spot potential rebound plays by hunting through the 121 elite penny stocks with strong financials that already pair stronger balance sheets with real operating traction.
- Prioritise resilience first by filtering for companies on the 218 resilient stocks with low risk scores that score well on both financial strength and risk checks.
- Get ahead of the crowd by scanning the 614 high quality undiscovered gems that combine quality fundamentals with far less market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com