


Earnings Guidance Reaffirmed Might Change The Case For Investing In Carlisle Companies (CSL)
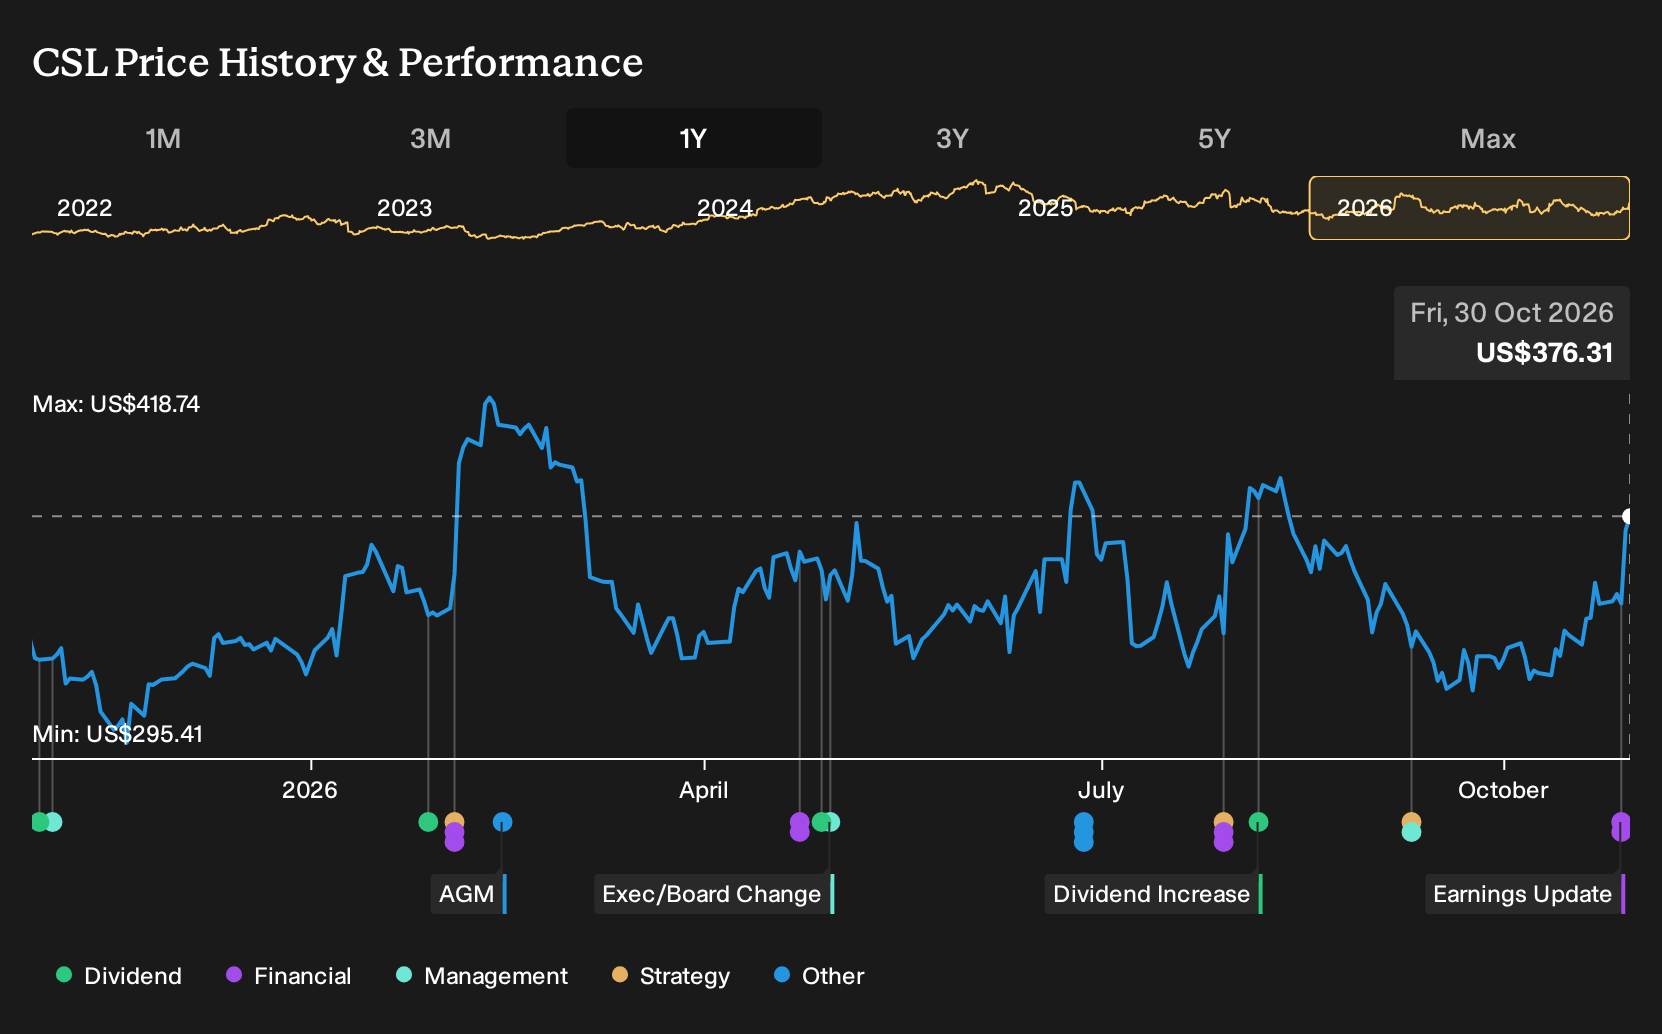
- Carlisle Companies reported third quarter 2026 sales of US$1,463.4 million and net income of US$208.1 million, alongside fourth quarter guidance that points to high single digit year over year revenue growth.
- The business used firm pricing and efficiency efforts to counter higher costs, while the Board reaffirmed its capital return stance with a US$1.25 per share dividend declared for December 2026.
- Investors may now consider how Carlisle Companies' earnings resilience and reaffirmed revenue outlook relate to the broader investment narrative.
Scan how Carlisle Companies' latest dividend affirmation and earnings update stack up against other income-focused industrials by reviewing our hand picked 5 dividend fortresses.
Carlisle Companies Investment Narrative Recap
Carlisle Companies appeals to shareholders who believe in a large reroofing and building envelope market, where pricing power, higher value products and the Carlisle Operating System can support earnings even when construction sentiment is mixed. The recent third quarter showed higher sales and earnings per share alongside some margin pressure, which keeps execution on cost management and productivity as the key short term catalyst.
The main operational risk right now sits with raw material and freight costs staying elevated while new construction volumes remain uneven. Management’s guidance for high single digit fourth quarter revenue growth points to a stable near term backdrop. However, the latest update does not fundamentally change either the core thesis or the key risk.
The most relevant recent announcement for you is Carlisle Companies’ fourth quarter 2026 guidance that points to high single digit revenue growth compared with the prior year period. That outlook connects directly to the reroofing and building envelope story because it sets expectations for near term demand and pricing before any longer term Vision 2030 ambitions even come into play.
That revenue view also frames the next checkpoint on the biggest swing factor: margins. With third quarter net income slightly lower year over year despite higher sales, the coming quarter will show how much efficiency work, price realization and product mix can offset raw material and freight costs. For investors tracking catalysts, execution against this guidance is where the near term evidence will show up first.
Carlisle Companies' narrative projects US$5.9b revenue and US$949.0 million earnings by 2029. This assumes 5.0% yearly revenue growth and an earnings increase of about US$218 million from current earnings of US$730.7 million.
Uncover why Carlisle Companies' fair value indicates a 7% potential upside to its current price before the market closes the discount.
Exploring Other Perspectives
You are seeing one clear disagreement. The bullish analysts treat Carlisle Companies’ data center roofing push as a potential accelerator, with forecasts already baking in US$6.2b revenue and US$1.0b earnings by 2029. Those projections came before this dividend and guidance update, so you may want to compare how your own view lines up with both narratives.
Explore 3 other Carlisle Companies fair value estimates, including one that suggests as much as 44% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider independent research and analysis.
- A great starting point for your Carlisle Companies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Carlisle Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Carlisle Companies' overall financial health at a glance.
Looking For More Carlisle Companies Style Ideas?
If Carlisle Companies has you rethinking how you balance income, quality and risk in your portfolio, it can help to line it up against a wider field of stocks using the Simply Wall St Screener.
- If you want potential upside with a margin of safety, scan a carefully filtered list of companies that screen as mispriced on quality metrics through our 33 high quality undervalued stocks.
- If balance sheet strength is non negotiable for you, sort the market by leverage and liquidity using the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for underfollowed opportunities with healthy fundamentals, widen your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com