


Will Fast Vaginitis Test Approval Change bioMérieux Stock Narrative
- bioMérieux reported that the BIOFIRE SPOTFIRE Vaginitis Panel received Dual 510(k) Clearance and a CLIA Waiver from the FDA, enabling rapid point of care PCR testing for eight vaginitis targets in about 20 minutes using either self collected or clinician collected swabs.
- This first rapid molecular vaginitis test extends bioMérieux’s SPOTFIRE menu beyond respiratory and sore throat panels, and deepens the reagent driven point of care opportunity across primary care, urgent care, and OB/GYN settings.
- We will now consider how bioMérieux’s investment narrative could be influenced by the CLIA waived, 20 minute SPOTFIRE Vaginitis Panel.
Compare bioMérieux's point of care push with other diagnostic players building similar momentum by scanning our hand picked 125 healthcare AI stocks in testing and healthcare automation.
bioMérieux Investment Narrative Recap
To own bioMérieux, you need to believe the heart of the story lies in BIOFIRE and SPOTFIRE reagent usage, industrial applications, and the GO•28 efficiency program continuing to offset weaker instrument demand, respiratory pressure, China softness, and higher tariffs. The new SPOTFIRE Vaginitis Panel fits squarely into that reagent driven thesis, but on its own does not change it.
In the near term, the key swing factor is how quickly SPOTFIRE non respiratory panels and industrial applications contribute to earnings while tariffs and China remain a drag. The vaginitis launch adds another reason for clinicians to use existing SPOTFIRE instruments, which supports the narrative, yet the biggest risk around softer BIOFIRE placements and expiring pandemic era contracts still matters.
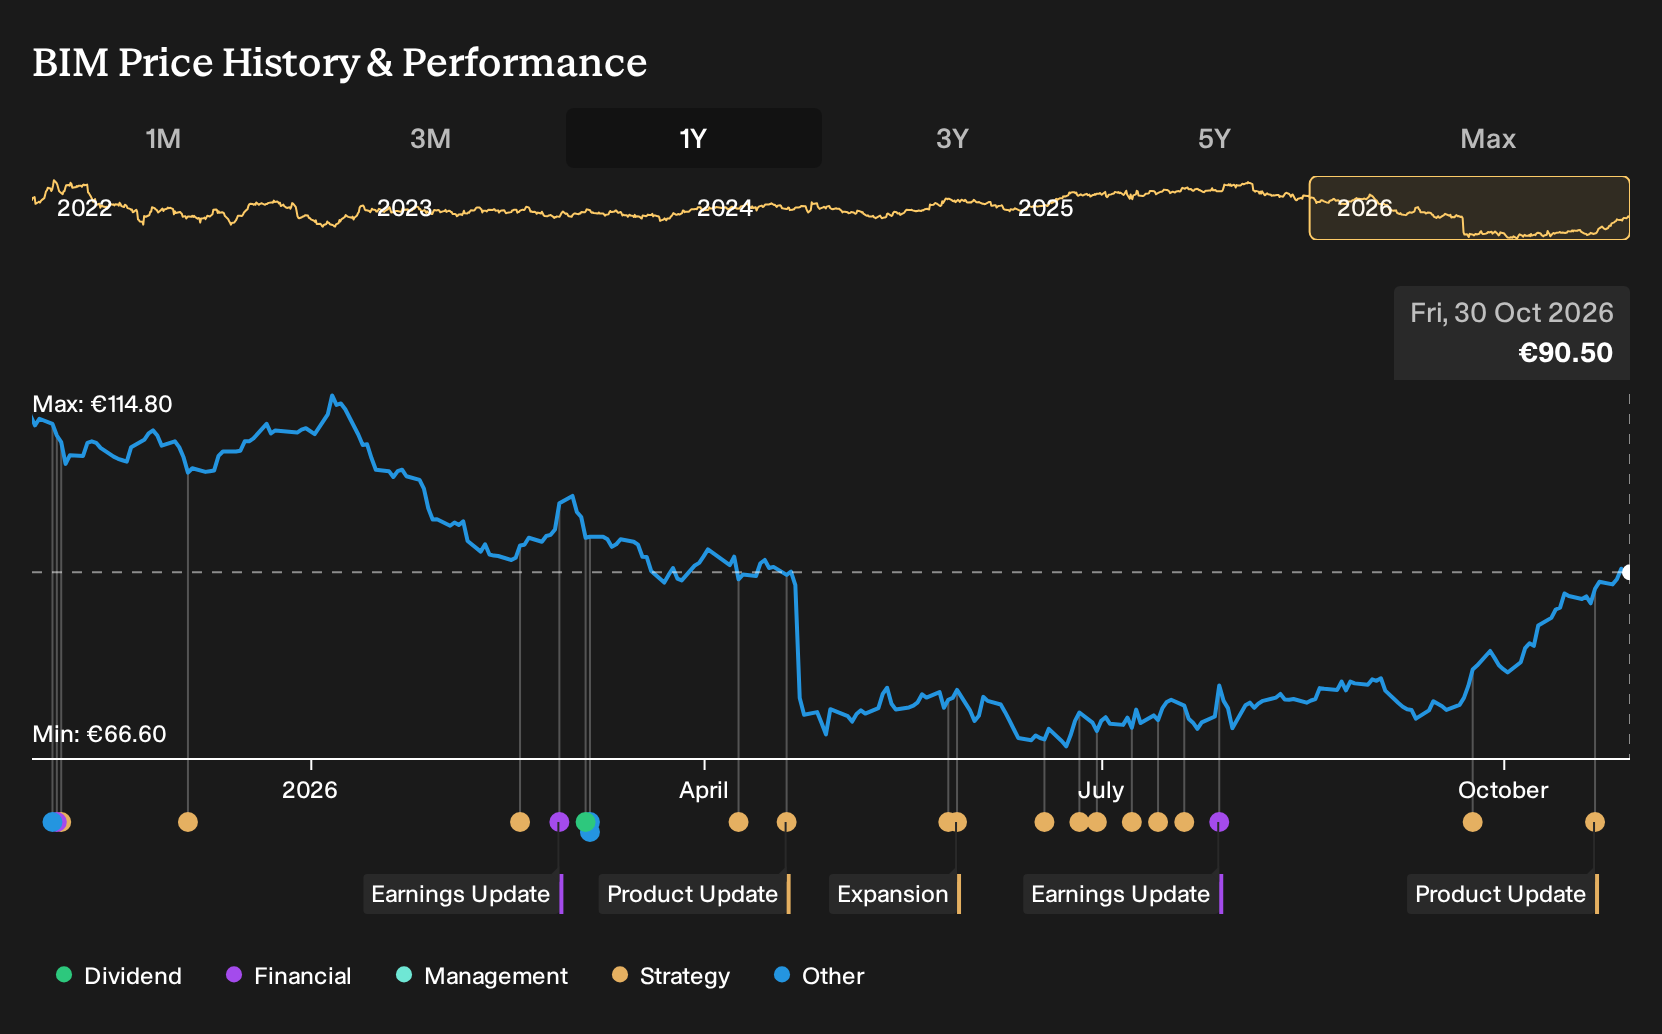
The clearest operational link to this news is SPOTFIRE’s earlier outperformance, which helped build an installed base of 7,200 instruments by the second quarter of 2026, around 60% above June 2025. That footprint gives bioMérieux more testing “real estate” where a CLIA waived, 20 minute vaginitis assay can plug straight in and potentially support reagent throughput.
For catalysts, the combination of this new panel with around 40% SPOTFIRE reagent growth in the second quarter of 2026 points to how menu expansion can matter over time. Execution risk sits on the other side of that coin, because if instrument demand stays weak or China pressure persists, even strong assay launches like the vaginitis panel may not fully offset headwinds to revenue mix and CEBIT margin.
bioMérieux's current analyst narrative points to revenues of €4.7b and earnings of €586.7m by 2029, based on a 5.4% yearly revenue growth rate and an earnings increase of about €124m from €462.6m today.
Uncover why bioMérieux's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts on bioMérieux already expected point of care to reshape the story, with forecasts of €4.9b in revenue and €672.4m in earnings by 2029 before this vaginitis panel news. Those forecasts lean on rapid SPOTFIRE expansion. You might see that as aggressive or achievable, and that is exactly why it helps to compare several viewpoints and decide where you land.
Explore 2 other bioMérieux fair value estimates, including one that suggests up to 25% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your bioMérieux research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for bioMérieux. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate bioMérieux's overall financial health at a glance.
Looking for more investment ideas beyond bioMérieux?
Once you have a view on bioMérieux, it helps to line that thesis up against a few other opportunities so you can see where the risk and reward trade off really feels comfortable for you.
- For investors willing to accept higher volatility in exchange for the chance of meaningful moves in smaller companies, scan our 121 elite penny stocks with strong financials that already show solid financial traits.
- If you prefer businesses where quality and valuation work together, check out our 204 high quality undervalued stocks that combine healthier balance sheets with stronger cash generation.
- Those who care most about capital preservation and steadier profiles can review our 218 resilient stocks with low risk scores that score well on resilience and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com