


The Bet Behind SSAB's Rally
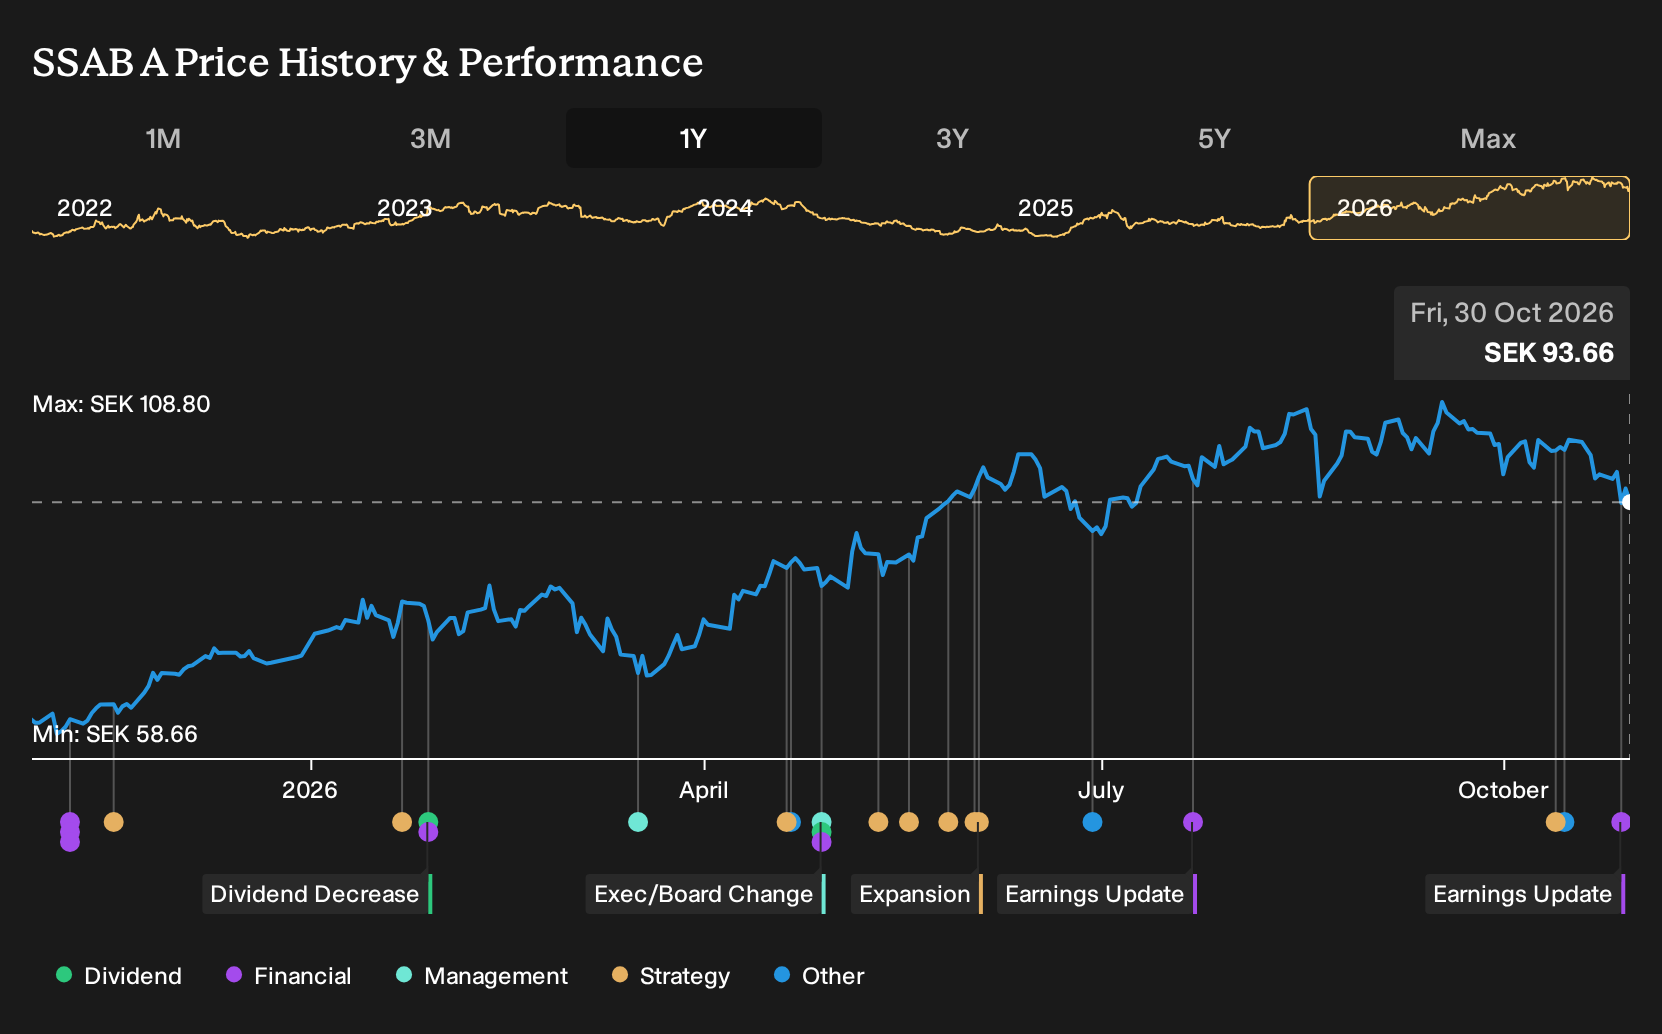
If SSAB was on your watchlist instead of in your portfolio, the outcome over the last year might feel like a missed shot. For SSAB shareholders, the return over the past year was 59.2%, including dividends. That kind of move invites a simple question. Back on 30 October 2025, when analysts were split between HYBRIT-led upside and decarbonization delays, how could you have judged whether SSAB’s push into fossil-free, premium steel would really translate into stronger pricing power?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
SSAB has already moved. See which of 204 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Weigh On SSAB
The shares cost SEK60.34 at the start of the period, and you were essentially choosing between two coherent stories about where SSAB could head next.
The bullish narrative saw fair value at SEK68.58 and leaned on HYBRIT and SSAB Zero attracting long term demand from major OEMs, with assumptions for 2.1% annual revenue growth and profit margins reaching 6.7% by 2028.
The bearish view put fair value at SEK52 and focused on decarbonization delays, flat assumed revenue growth at 0.0%, and earnings at SEK4.5b with margins nudging to 4.6%.
What The Evidence Around SSAB Actually Tested
The biggest real world test for SSAB was progress on fossil free steel. Shutting the Oxelösund blast furnace and moving to electric arc production, plus railcar projects using SSAB Zero, supported the thesis about decarbonized premium steel. Reported Q3 2026 revenue of SEK25,632m and net income of SEK1,559m, with net margin slipping to 6.1%, meant profitability progress looked more mixed. Overall, the evidence pointed in both directions.
The lesson to apply to other stocks is straightforward. When a thesis depends on premium, greener products, track concrete capacity shifts and product launches, and then compare them with revenue, profit and margin trends in each results release.
What SSAB’s Current Price Already Implies
SSAB now trades at SEK93.66 after a 59.2% total return over the past year. The selected Narrative’s Fair Value estimate sits below that level, which frames today’s quote as already baking in a stronger case than the author’s own numbers.
The Narrative leans on protection against Chinese steel and EU driven demand, so a buyer today is effectively assuming those trade and policy supports keep holding despite the risks flagged around energy driven economic pressure.
"Sweden's traditional steel mill, SSAB is in an enviable position relative to its peers for three reasons: 1) Its plants are strategically well placed on both sides of the Atlantic; thus, it will not be caught between millstones when the US and the EU get entangled in a trade war centred on steel and aluminium. Indeed, the company is set to downright profit from it, when its markets both in the US and the EU will get protection from Chinese and Korean competition."
The price and this Narrative do not agree. → Uncover what this Narrative says SSAB is actually worth
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 27% below our estimate - expands adult and oral health probiotics through direct channels and in-house production.
- Company 2 - 16% below our estimate - attracts senior lawyers to a dispersed, tech enabled platform with higher fee shares.
- Company 3 - 21% below our estimate - pushes tiltrotators into underpenetrated excavator markets as installed base and volumes climb.
Those are three of them. See all 199 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com