


How Strong Earnings Results At BioGaia (OM:BIOG B) Have Changed Its Investment Story
- BioGaia reported third quarter 2026 sales of SEK 400.44 million and net income of SEK 110.21 million, with higher basic and diluted earnings per share from continuing operations compared with the same period in 2025.
- The nine month figures show SEK 1,213.85 million in sales and SEK 292.78 million in net income. This indicates that BioGaia’s probiotics portfolio and distribution model continued to support profitability across both pediatric and adult product lines.
- We will examine how BioGaia’s stronger earnings per share trajectory may influence the investment narrative that focuses on margins and product mix.
Scan BioGaia’s earnings jump alongside other health-focused stocks that screen strongly on cash flows and balance sheets through our curated list of list of solid balance sheet and fundamentals (199 results).
BioGaia Investment Narrative Recap
To own BioGaia, you need to believe the probiotics portfolio can keep pulling in healthy earnings while the shift toward Adult Health and direct distribution holds together. The latest quarter delivered higher sales, net profit and earnings per share, which supports that view. The near term swing factor still looks like how effectively BioGaia turns this demand into consistent cash generation.
The clearest risk right now sits in execution. Asia Pacific has already shown uneven orders and working capital has been absorbing cash. With capital expenditure rising and internal production expanding, the recent earnings strength only helps if demand across regions and product mix remain supportive of that heavier asset base.
The most relevant update for this earnings print is management’s decision to step up investment in BioGaia Production in 2026, including the new warehouse and EasyDropper line. That spending relies on the same thesis investors are testing after this quarter. The business is committing to higher internal capacity to support its pediatric and adult probiotics.
Recent profit and earnings per share trends give that capex plan more operational backing, since the company is not investing from a position of weak profitability. The trade off is clear for you as a shareholder. Higher fixed costs and softer operating cash flows increase sensitivity to any slowdown in Asia Pacific or in higher margin Adult Health products.
BioGaia Forecasts and What Needs To Go Right
Analysts expect BioGaia to grow into a larger probiotics platform over the next few years, but the path they are sketching out comes with clear numerical hurdles. The projections combine top line expansion, firmer profit margins and a lower P/E than today. This means the story relies as much on execution as it does on simple growth.
BioGaia's narrative projects SEK 2.3b revenue and SEK 623.2 million earnings by 2029. This assumes 11.6% yearly revenue growth and an earnings increase of roughly SEK 231.6 million from SEK 391.6 million today.
Forecasts in the consensus work off a few core building blocks. Analysts are pencilling in 11.6% annual revenue growth over the next three years. Profit margins are expected to shift from 23.7% currently to 27.1% by around 2029. This effectively asks the business to convert a greater share of each krona of sales into profit while scaling internal production and direct markets.
Earnings form the other main pillar. The group of covering analysts expects profit to reach SEK 623.2 million in 2029 compared with SEK 391.6 million today. That is an uplift of about SEK 231.6 million. The consensus earnings per share estimate of SEK 6.18 in that same year is built on the view that the share count stays broadly flat, so the bulk of the increase comes from higher absolute earnings rather than financial engineering.
Valuation expectations then layer on top. To line up with the current analyst price targets, the share would need to trade on a P/E of 30.2x those 2029 earnings, compared with 32.9x today. That implies the scenario needs both higher earnings and a slightly lower earnings multiple at the same time. This leaves less room for disappointment on either margins or revenue growth if you are leaning on this framework.
Uncover how BioGaia's fair value indicates a 31% potential upside to its current price, prior to sentiment around BioGaia’s earnings strength resetting expectations.
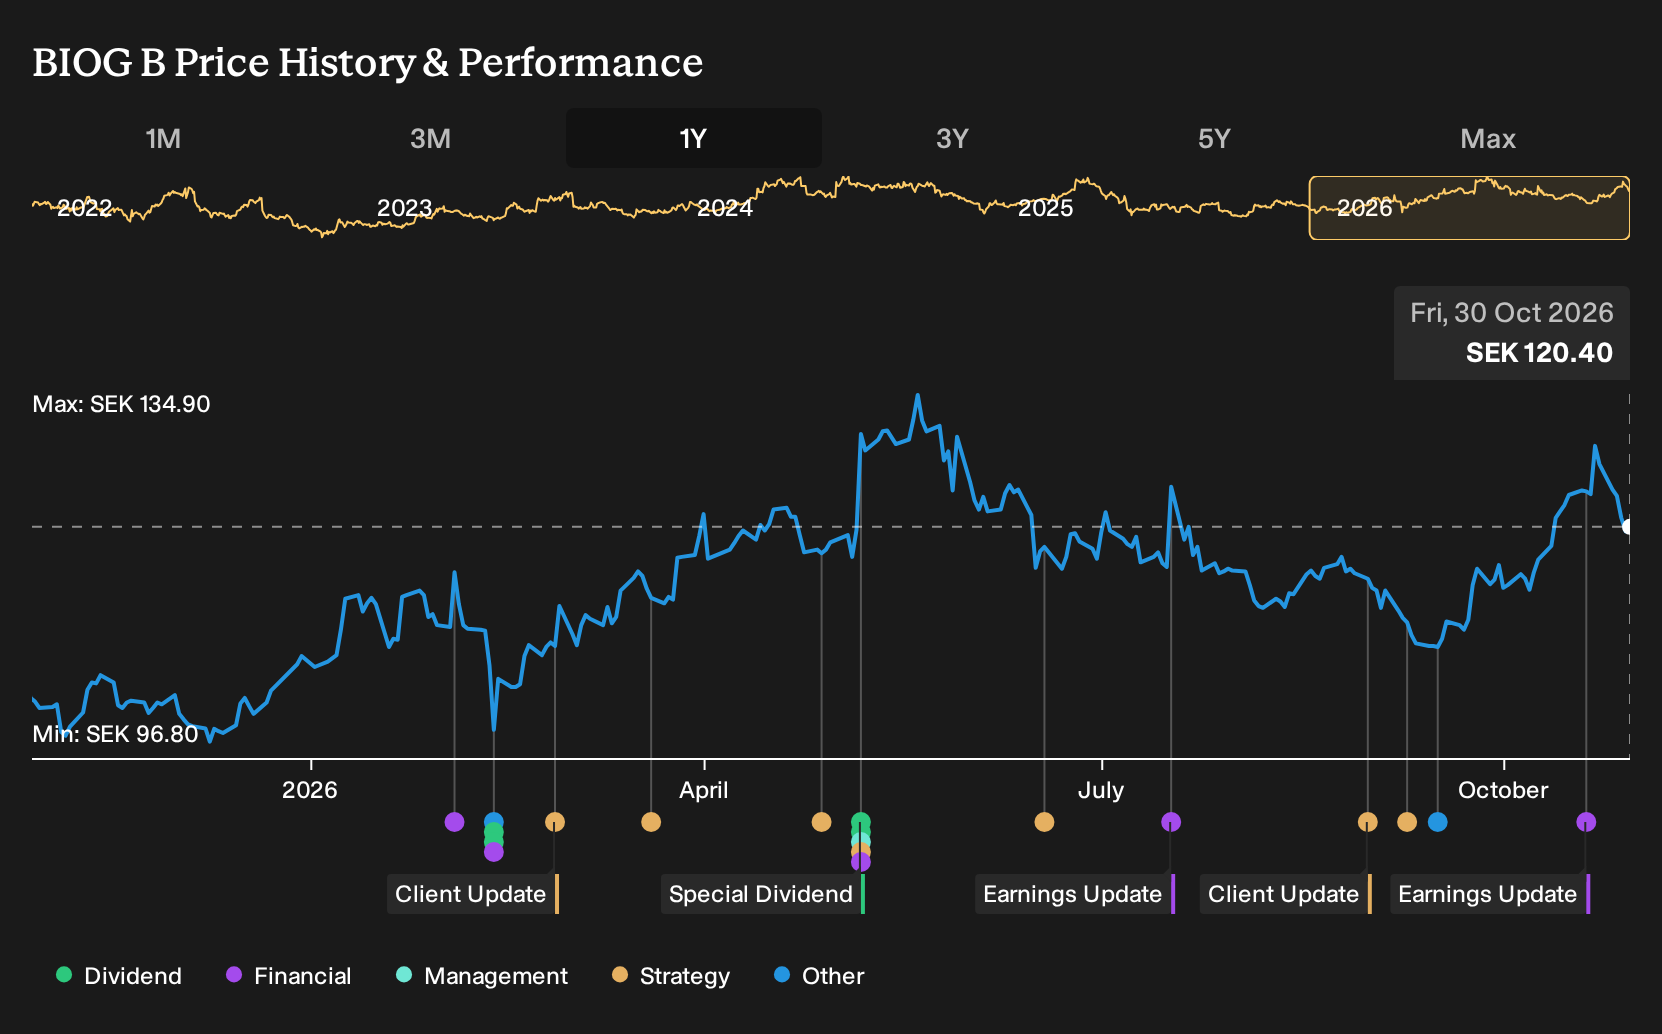
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between SEK 158 and about SEK 165, so private investors already span a tight band on what BioGaia might be worth. You should weigh that against Asia Pacific volatility and heavier capex, which together could influence how quickly recent earnings translate into sustainable performance.
Explore 2 other BioGaia fair value estimates, including one that suggests as much as 37% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BioGaia research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioGaia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioGaia's overall financial health at a glance.
Looking for more BioGaia-style investment ideas?
If BioGaia’s mix of earnings, margins and balance sheet detail has sharpened your appetite for further research, the Simply Wall St screener can help you quickly sort through other listed businesses that match your preferred risk and return profile.
- For investors who want stronger balance sheets and steadier fundamentals, consider starting with a list of solid balance sheet and fundamentals (199 results) that already pass a tougher quality filter.
- If you are hunting for companies that the market may be pricing conservatively, filter for value-focused opportunities using our 204 high quality undervalued stocks built on both earnings and balance sheet strength.
- Those looking beyond the usual index constituents can comb through a hand picked pool of underfollowed stocks by running the 614 high quality undiscovered gems and seeing which ideas match your own thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com