


Medpace Holdings (MEDP) Following Strong Q3 And 2026 Outlook Has Valuation Back In Focus
Why Medpace Holdings Is Back On Investors’ Radar
Medpace Holdings (MEDP) just paired a fresh 2026 outlook with a strong third quarter update, giving investors new numbers to work with on both growth expectations and current profitability.
The fresh 2026 guidance and buyback authorization have landed after a strong run, with Medpace Holdings delivering a 13.73% 90 day share price return and a three year total shareholder return of 137.78%. The one year total shareholder return of 11.47% points to momentum that has cooled slightly but remains firmly positive in a longer term context.
Scan how Medpace Holdings stacks up against other research driven healthcare players by reviewing our hand picked 34 healthcare AI stocks that are also seeing strong interest around earnings and guidance updates.
Medpace Holdings now trades roughly in line with the latest analyst target yet still shows a modest intrinsic discount, so the live question is where fair value actually lands in that spread.
Most Popular Narrative: 22% Overvalued
According to the most followed thesis on Medpace Holdings, the narrative fair value of $536 sits well below the recent $652.01 close, which puts a gap between the share price and the underlying cash generation story.
Medpace appears to be a high-quality CRO because it combines a differentiated small-biotech focus, strong therapeutic expertise, a global full-service platform, operating margins above 20%, low capital requirements, substantial cash and no funded debt.
The balanced conclusion is less promotional than “dominates a profitable niche.” Medpace has built a strong position in a difficult-to-replicate part of the CRO market, but its revenue is not locked in, its customers can be financially fragile, and founder control brings related-party governance considerations. At around 35 times management’s 2026 earnings guidance, the business quality is evident; however, the margin of safety in the share price is less obvious.
See why 7 investors see Medpace Holdings as 22% overvalued.
Result: Fair Value of $536 (OVERVALUED)
Still, the Medpace narrative can crack if small biotech clients struggle for funding or if trial cancellations start to eat into that US$3.03b backlog.
Find out about the key risks to this Medpace Holdings narrative.
Another Look At Medpace Holdings’ Valuation
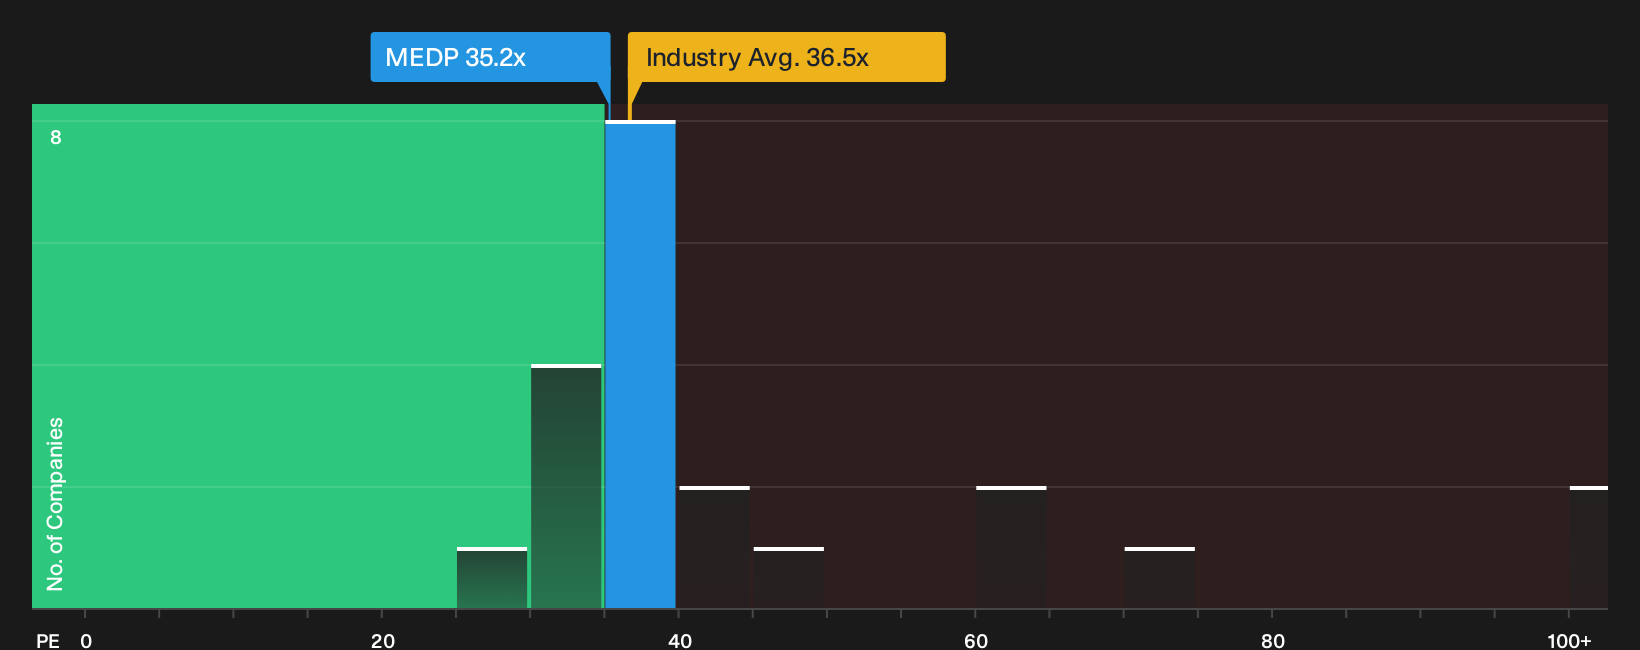
The user narrative calls Medpace Holdings roughly 22% overvalued at $652.01, yet the current P/E of 35.2x tells a more mixed story. It sits below the peer average of 51.7x and just under the global Life Sciences mark of 36.5x, but well above the 22.4x fair ratio the market could move toward. That gap suggests investors are paying a clear premium, which may reward patience if sentiment holds or punish holders if expectations reset.
To see how that premium compares with detailed earnings and peer data, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Medpace Holdings have probably come through clearly by now, with both potential downside and upside in play. Consider moving quickly and testing the narrative against your own thresholds using the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Medpace Holdings?
If Medpace Holdings has sharpened your thinking on valuation and risk, do not stop here. Broaden your watchlist now and avoid missing other clear opportunities.
- Target resilient income by scanning companies described as 5 dividend fortresses that may help anchor returns when growth stories are harder to find.
- Hunt for mispriced quality through a curated 19 high quality undiscovered gems that could add fresh ideas before they sit on everyone else's radar.
- Reduce portfolio stress by focusing on durability with a 29 resilient stocks with low risk scores and see which businesses hold up best when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com