


9.22 Ridgepost Capital (RPC) Looks Pricey As Valuation Checks Clash
Recent Performance Snapshot
Ridgepost Capital (RPC) has drawn fresh attention after recent trading left the stock at US$9.22, with the move capping a gain of about 21% over the past month.
That short burst in Ridgepost Capital’s share price comes after a tougher stretch, with a 30 day share price return of 21% contrasting with a year to date share price decline of 6.77% and a 1 year total shareholder return that is down 7.61%. This points to momentum rebuilding from a lower base rather than a long running rally.
Compare Ridgepost Capital’s rebound with a curated set of under pressure but quality-focused opportunities using the 33 high quality undervalued stocks as a starting shortlist.
The snapback in Ridgepost Capital after a weak year sets up a simple tension. Are buyers still getting paid for the risk at US$9.22, or has the easy part of the opportunity already passed?
Preferred P/E Multiple of 37.1x: Is It Justified?
Ridgepost Capital is currently valued at a P/E of 37.1x, while the share price sits at $9.22 and trails a weak 1 year total return. That combination raises the question of whether investors are paying too much for the recent earnings recovery or simply pricing in a higher quality growth profile.
The P/E ratio compares what the market is paying for each dollar of current earnings. For a diversified alternative asset manager like Ridgepost Capital, this often reflects how durable investors think fee income and performance-related revenue could be, especially after periods where profits either contract or are hit by one off items.
Management has reported earnings growth of 87.6% over the past year and revenue growth of 17.1% annually. However, this sits against a 5 year period where earnings declined 3.2% per year and where a $16.2m one off loss still distorts the trailing picture. Paying 37.1x earnings in that context indicates that the market is placing a rich price on the current profit level, with a multiple that is expensive relative to the peer average of 11.6x and only in line with the broader US Capital Markets industry at 37.1x.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 37.1x (OVERVALUED)
Still, Ridgepost Capital’s story can be knocked off course if fee dependent revenue softens or if that earlier one off loss proves less contained than expected.
Find out about the key risks to this Ridgepost Capital narrative.
Another View on Ridgepost Capital’s Valuation
The first check said Ridgepost Capital looks expensive on a 37.1x P/E. A second lens tells a different story. Our DCF model, which values the stock on future cash flows, points to a fair value of just $0.25 per share, implying a steep premium at the current $9.22 price.
When two methods disagree this sharply, which one do you trust more for your own process: the earnings multiple or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
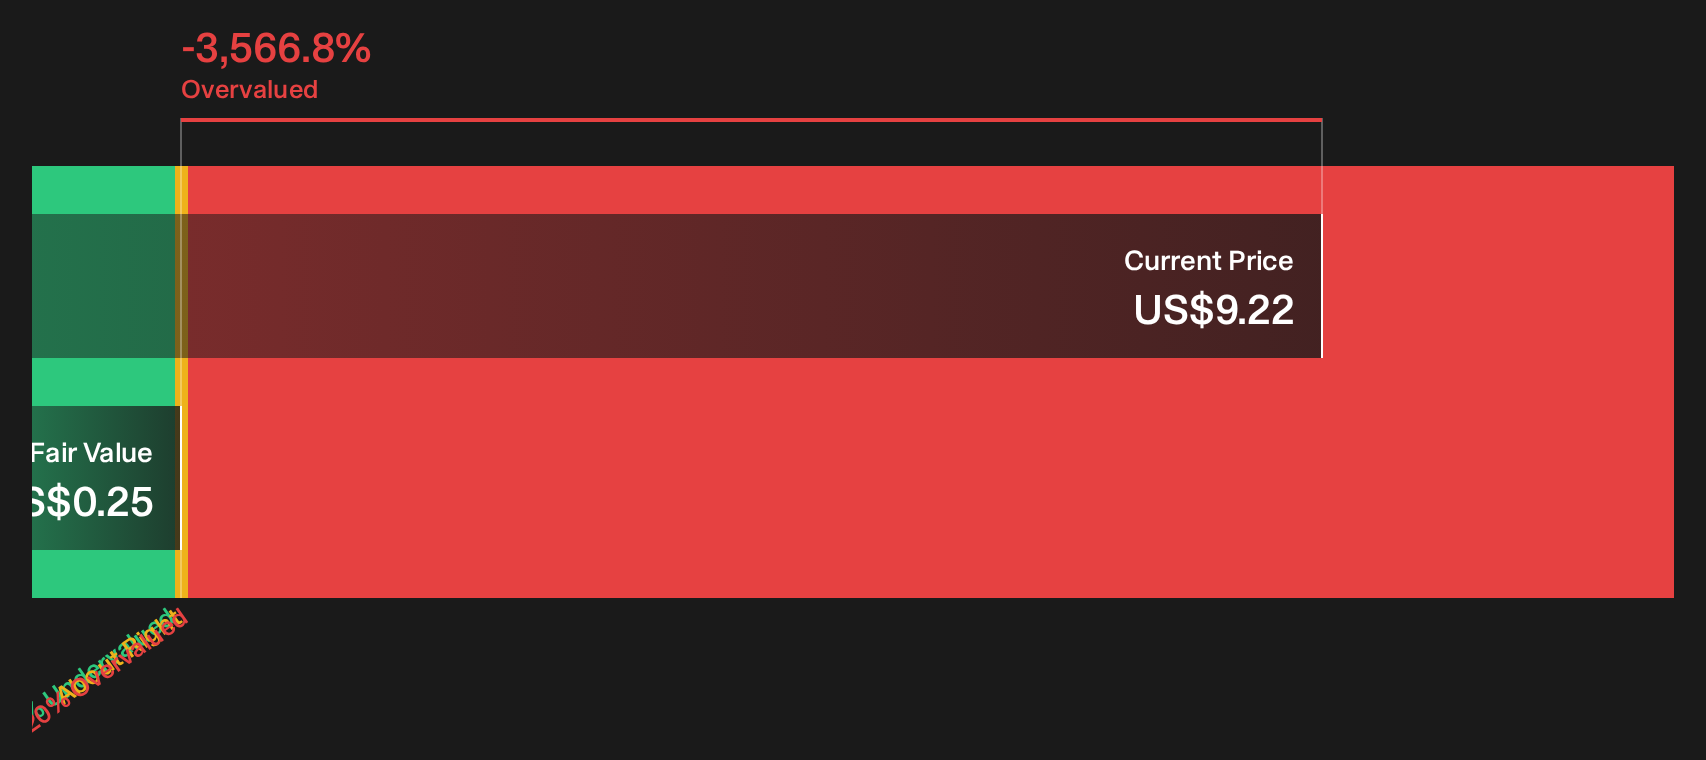
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ridgepost Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mixed picture around Ridgepost Capital feels hard to pin down, use the full dataset, weigh the trade offs, and pressure test your thesis against the 3 key rewards and 3 important warning signs.
Looking for more Ridgepost Capital style ideas?
Do not stop with just one stock. Broaden your watchlist with a few focused screens that surface different kinds of opportunities worth a closer look.
- Target potential mispricings by scanning a curated group of quality companies that appear out of favour using the 33 high quality undervalued stocks.
- Strengthen the defensive side of your holdings by filtering for businesses with resilient finances through the list of solid balance sheet and fundamentals (24 results).
- Hunt for underfollowed opportunities by checking a focused 19 high quality undiscovered gems that may not yet be crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com