


Did Dubai Flagship Debut Just Shift Yum! Brands' (YUM) Investment Narrative?
- KFC, part of Yum! Brands, opened its KFC Muse flagship in Dubai, pairing an evolved restaurant design with features like the Kinetic Bucket, KWENCH specialty drinks and the customizable KFC MIX'D chicken experience, with a second Muse site planned for Seoul.
- The KFC Muse concept focuses on hospitality and longer in store visits, which can influence store level economics, staffing needs and future remodel decisions across the Yum! Brands footprint.
- We will examine how Yum! Brands' investment narrative is affected by the KFC Muse concept and its KWENCH specialty beverage platform.
Scan how Yum! Brands' hospitality focused KFC Muse rollout compares with other consumer brands preparing for potential breakouts by reviewing our curated list of 19 high quality undiscovered gems.
Yum! Brands Investment Narrative Recap
To own Yum! Brands, you need to believe the global KFC and Taco Bell system can keep lifting digital mix and store economics, even as overall earnings are projected to edge down 1.2% per year over the next three years. The short-term swing factor is whether traffic recovers where demand has been softer, particularly at Taco Bell after the Cyclospora related hit.
The main risk remains pressure on restaurant profitability if value deals, weaker visits or higher operating costs linger. KFC Muse in Dubai looks more like a test bed than a near-term earnings driver, so the flagship itself probably does not change the immediate risk reward skew in a material way.
The launch of KFC Muse matters most because it links directly to Yum! Brands catalysts around KFC’s role as the global growth engine and the push toward a higher margin digital and beverage mix. KWENCH specialty drinks and the KFC MIX'D format give the group more reasons to drive higher checks and longer visits inside an experiential store concept.
If the Muse format and KWENCH platform scale effectively into new builds and remodels, they could tie into the identified 20,000 unit KFC whitespace and Yum!'s Byte digital rollout. Execution risk does not go away, especially with heavy reliance on technology and franchise partners, but the concept gives management another operational lever as digital sales and capital returns remain in focus.
Yum! Brands' current analyst script pegs revenues at US$9.7b and earnings at US$2.1b by 2029, off a base of US$2.2b in earnings today. That profile lines up with a 3.6% yearly revenue growth assumption and an earnings decline of US$0.1b from current levels.
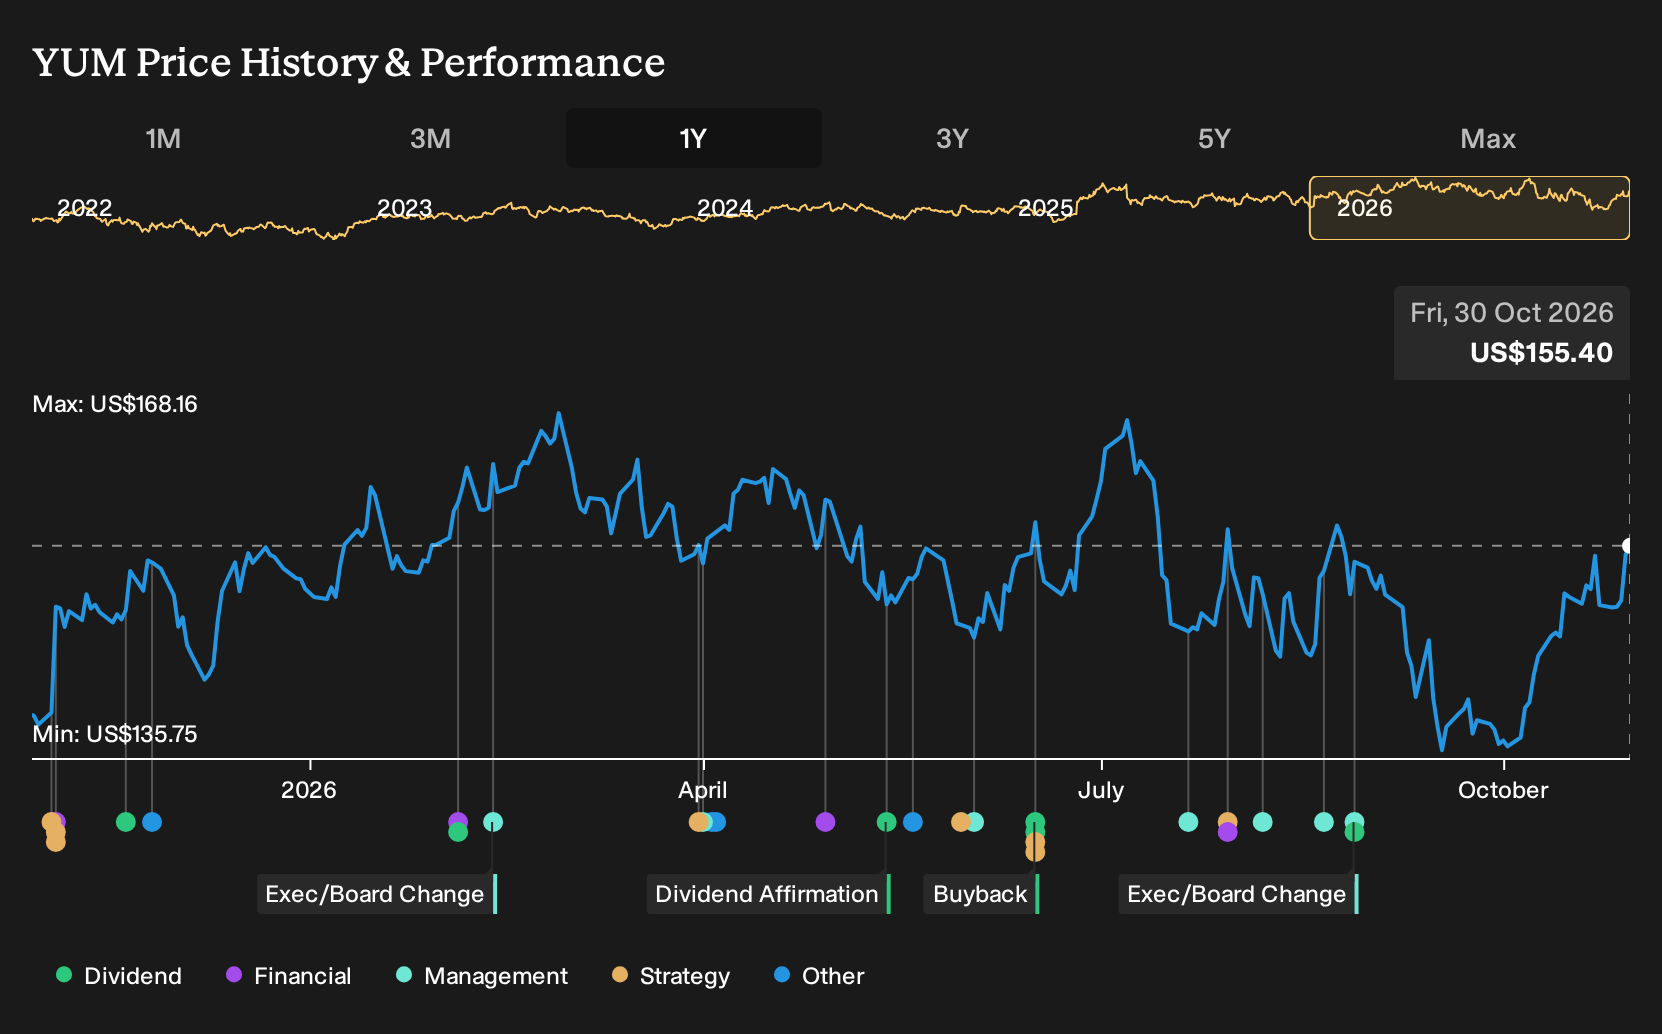
Uncover why Yum! Brands' fair value indicates an 11% potential upside to its current price before other investors close that discount.
Exploring Other Perspectives
Across four fair value estimates from the Simply Wall St Community, Yum! Brands lands in a tight band between US$170.61 and US$183.25, showing how closely some private investors cluster their views. You still face real disagreement on risks. Traffic softness, Taco Bell margin pressure and heavy Byte investment give plenty of reasons to weigh opposing narratives before deciding where you stand.
Explore 3 other Yum! Brands fair value estimates, including one that suggests there may be as much as 18% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yum! Brands research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Yum! Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yum! Brands' overall financial health at a glance.
Looking for more investment ideas beyond Yum! Brands?
If the Yum! Brands story has you thinking about where else disciplined capital and solid execution might show up, it can help to scan a wider field of opportunities that fit different risk and income preferences.
- For investors who want potential upside without stretching on quality, consider a curated set of 19 high quality undiscovered gems that pair stronger fundamentals with less crowded ownership.
- If capital preservation matters most and you want businesses with steadier profiles, you can filter for companies that score well on resilience using a 29 resilient stocks with low risk scores that keeps risk front and center.
- Income focused readers can focus on companies with meaningful yields by reviewing a hand picked group of 5 dividend fortresses that combine payout potential with durable operations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com