


Knorr Bremse (XTRA:KBX) Could Be 24% Undervalued As 2026 Outlook Was Reaffirmed
Earnings snapshot and market reaction
Knorr-Bremse (XTRA:KBX) just put fresh numbers on the table, reporting nine month 2026 results alongside a confirmed full year outlook that frames how the business is tracking against its revenue and profitability targets.
The group booked €6,132 million in sales and €6,289 million in revenue for the period, with net income of €502 million and basic earnings per share from continuing operations of €3.11.
Knorr-Bremse shares closed at €90.4 after the earnings release, with a 1-day share price return of 0.67% following the confirmed 2026 guidance, even though the 30-day share price return is down 8.87%. That short-term weakness contrasts with a 1-year total shareholder return of 14.35% and a 3-year total shareholder return of 77.59%. This points to momentum that has been built over a longer timeframe despite recent volatility around results and outlook headlines.
Scan beyond Knorr-Bremse and line up other industrials showing strong fundamentals and earnings momentum with our hand picked 218 resilient stocks with low risk scores.
Knorr-Bremse has solid year to date figures but a share price that has slipped over the past quarter. Does that mix still tilt the risk reward balance toward buyers at around €90?
Most Popular Narrative: 24% Undervalued
On the widely followed narrative, Knorr-Bremse screens as undervalued, with a fair value of €119.60 against the latest close at €90.40 and a discount rate of 6.77% anchoring that view.
Ongoing portfolio rotation, with around €750m of mainly sub 5% margin revenue divested and about €600m of 15% plus margin businesses acquired, including signaling and digital service assets, is shifting Knorr-Bremse toward a mix that can support higher group EBIT margins and cash generation.
Further scaling of Commercial Vehicle Systems after its breakeven load reduction to roughly 65 to 66% and personnel expense cuts of about €100m enables greater operating leverage, which can support the division's target of 12 to 14% EBIT margins by 2030 and lift group earnings when volumes grow.
See why 6 investors see Knorr-Bremse as 24% undervalued.
Result: Fair Value of €119.60 (UNDERVALUED)
Still, parts of the Knorr-Bremse story could unravel if the shift to lower cost production runs into geopolitical or quality problems, or if acquisitions such as duagon underperform margin goals.
Find out about the key risks to this Knorr-Bremse narrative.
Another View: Knorr-Bremse Through The P/E Lens
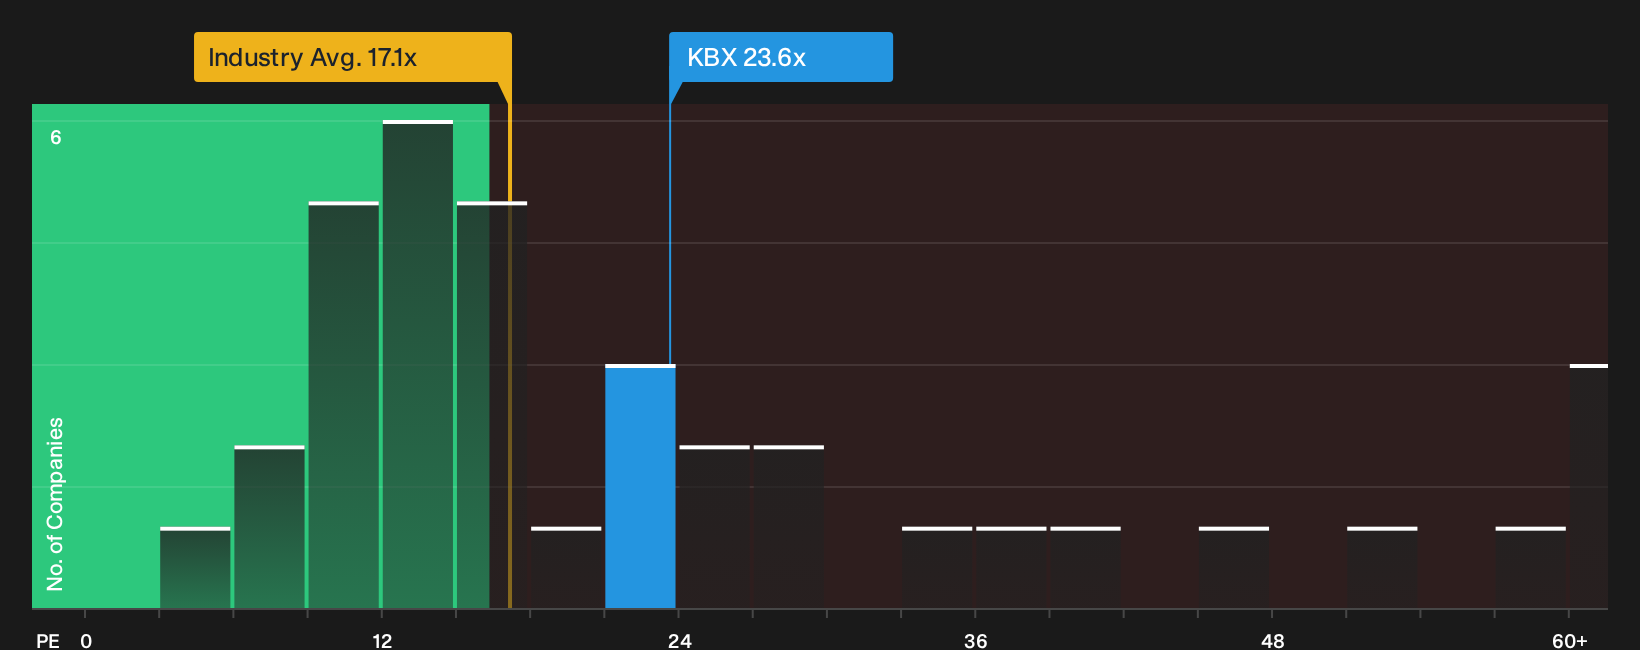
On simple earnings multiples, Knorr-Bremse looks less generous. The stock trades on a P/E of 23.6x, compared with 17.1x for the German Machinery industry and 20.7x for peers, while the fair ratio is 23x. That premium hints at less margin of safety if expectations slip.
For a closer look at what the current earnings multiple implies for upside or downside, including how it compares with peers over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Knorr-Bremse story so far. Take a few minutes to pull up the full data, evaluate it for yourself, and then run through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Knorr-Bremse?
If Knorr-Bremse has your attention, do not stop there. Put a few more high quality ideas on your radar before the next move.
- Target resilience first and hunt for companies with low risk profiles using the 218 resilient stocks with low risk scores to narrow the field fast.
- Push for quality at a sensible price by scanning the 204 high quality undervalued stocks so you are not relying on headlines alone.
- Prioritise balance sheet strength and filter for financially robust businesses through the list of solid balance sheet and fundamentals (199 results) before committing fresh capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com