


Medicover (OM:MCOV B) Could Be 5% Overvalued On Its ESMO 2026 Test Launch
Medicover (OM:MCOV B) has drawn fresh investor attention after Medicover Genetics launched its OncoSentia MRD liquid biopsy test at ESMO 2026 in Madrid, targeting longitudinal ctDNA monitoring in unresectable NSCLC patients.
Against this backdrop, Medicover’s momentum has been picking up. The company has recorded a 27.7% 90-day share price return and a 33.7% year-to-date gain at SEK 283.5, while the 3-year total shareholder return of 116.6% contrasts with a more modest 10.6% over the past year.
Spot fresh oncology momentum at Medicover, then widen your watchlist with carefully filtered peers in healthcare using the 125 healthcare AI stocks.Medicover’s sharp run, backed by fresh oncology data and a high-profile test launch, now leaves a simple tension. Are you paying for sentiment, or for a business that supports these prices?
Most Popular Narrative: 5% Overvalued
The most followed Medicover narrative pegs fair value at SEK269.91, a little below the SEK283.5 last close. As a result, the story now hinges on whether current optimism fully prices in the reinvestment plan and margin ambitions.
The main factor that has to go right is that Medicover successfully redeploys the approximately €0.74b of cash from the India hospitals sale into higher margin European healthcare and diagnostics while managing ongoing reimbursement and tariff reforms in Poland, Romania, and Germany.
The current valuation implies the share price already reflects a fairly valued, bullish view that Medicover can deliver its reiterated 2028 targets for more than €3.25b of organic revenue and over €600m of adjusted organic EBITDA while keeping leverage below 3x.
See why 6 investors see Medicover as 5% overvalued.
Result: Fair Value of SEK269.91 (OVERVALUED)
Still, Medicover’s dependence on Poland and Germany, along with heavy reinvestment of the €0.74b India proceeds, could backfire if tariffs tighten or new projects underperform.
Find out about the key risks to this Medicover narrative.
Another View: Medicover Through A Cash Flow Lens
Medicover screens as expensive on earnings multiples, with a P/E of 46.3x against 17.9x for the European healthcare sector and a fair ratio of 33.3x that the market could move towards. The Simply Wall St model instead values future cash flows at SEK687.66 per share, which points to a large discount. Which signal do you trust when these yardsticks disagree this much?
Our DCF model tackles that question by mapping out those future cash flows in detail, then discounting them back to today so you can see how sensitive the outcome is to your own assumptions about Medicover, not just the consensus view.Look into how the SWS DCF model arrives at its fair value.
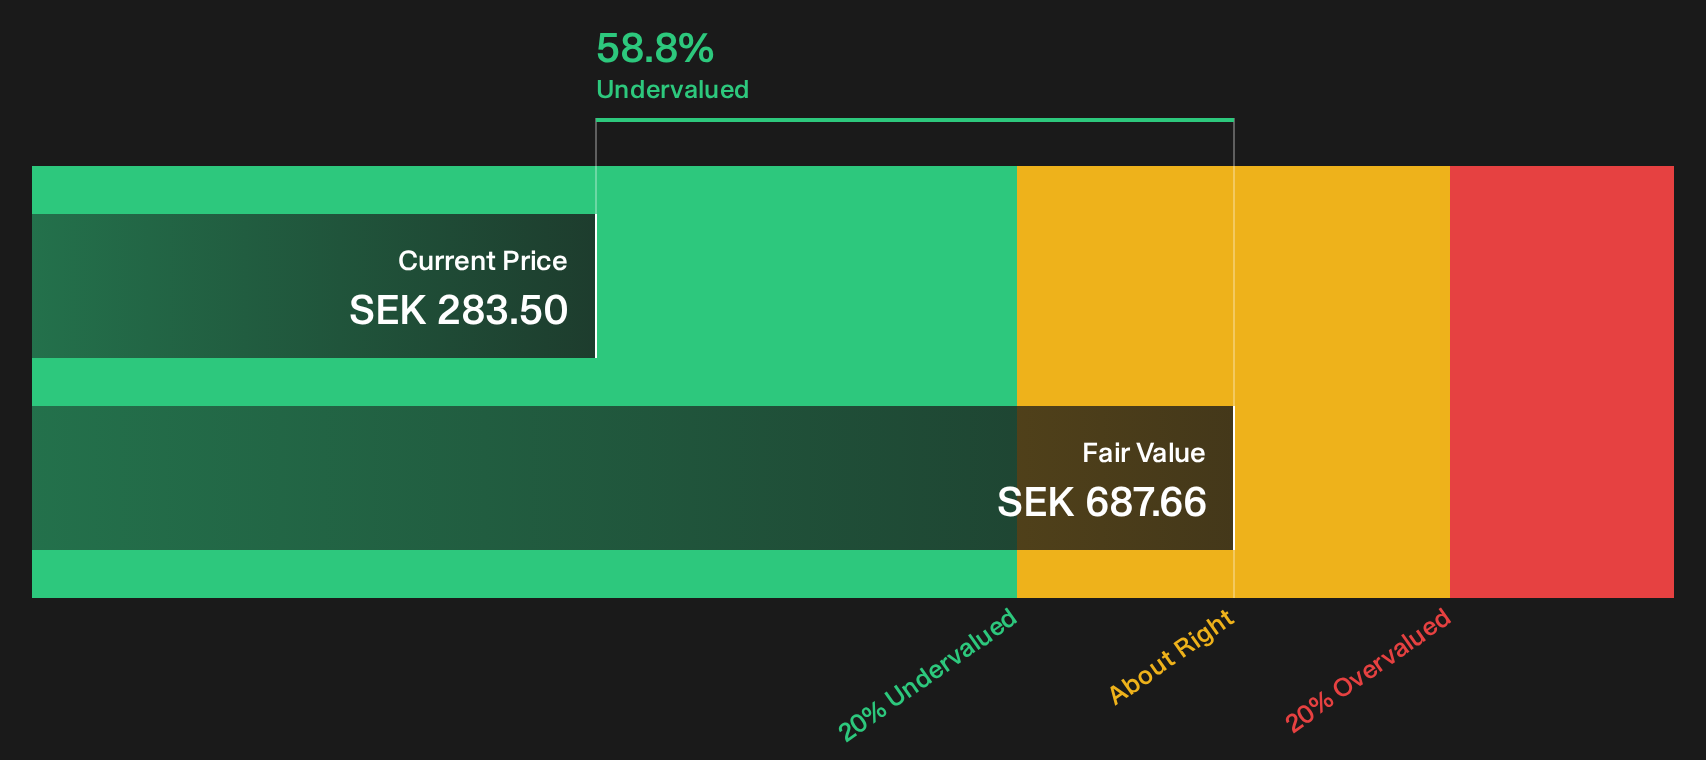
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Medicover for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty of investors see Medicover as finely balanced between promise and pressure, so move quickly, test the numbers yourself, and weigh both sides with the 3 key rewards and 2 important warning signs.
Looking for more Medicover-sized ideas?
If Medicover has sharpened your focus, do not stop here. Broaden your opportunity set now or risk missing better fits for your portfolio.
- Target quality at a discount by scanning a curated set of companies that combine strong fundamentals with appealing valuations using the 204 high quality undervalued stocks.
- Prioritise resilience and sleep-better-at-night positions by filtering for businesses with low risk profiles through the 218 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd notices by zeroing in on under-followed businesses with solid fundamentals via the 614 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com