


Is Higher Cash Distribution Altering The Investment Case For Global Partners (GLP)?
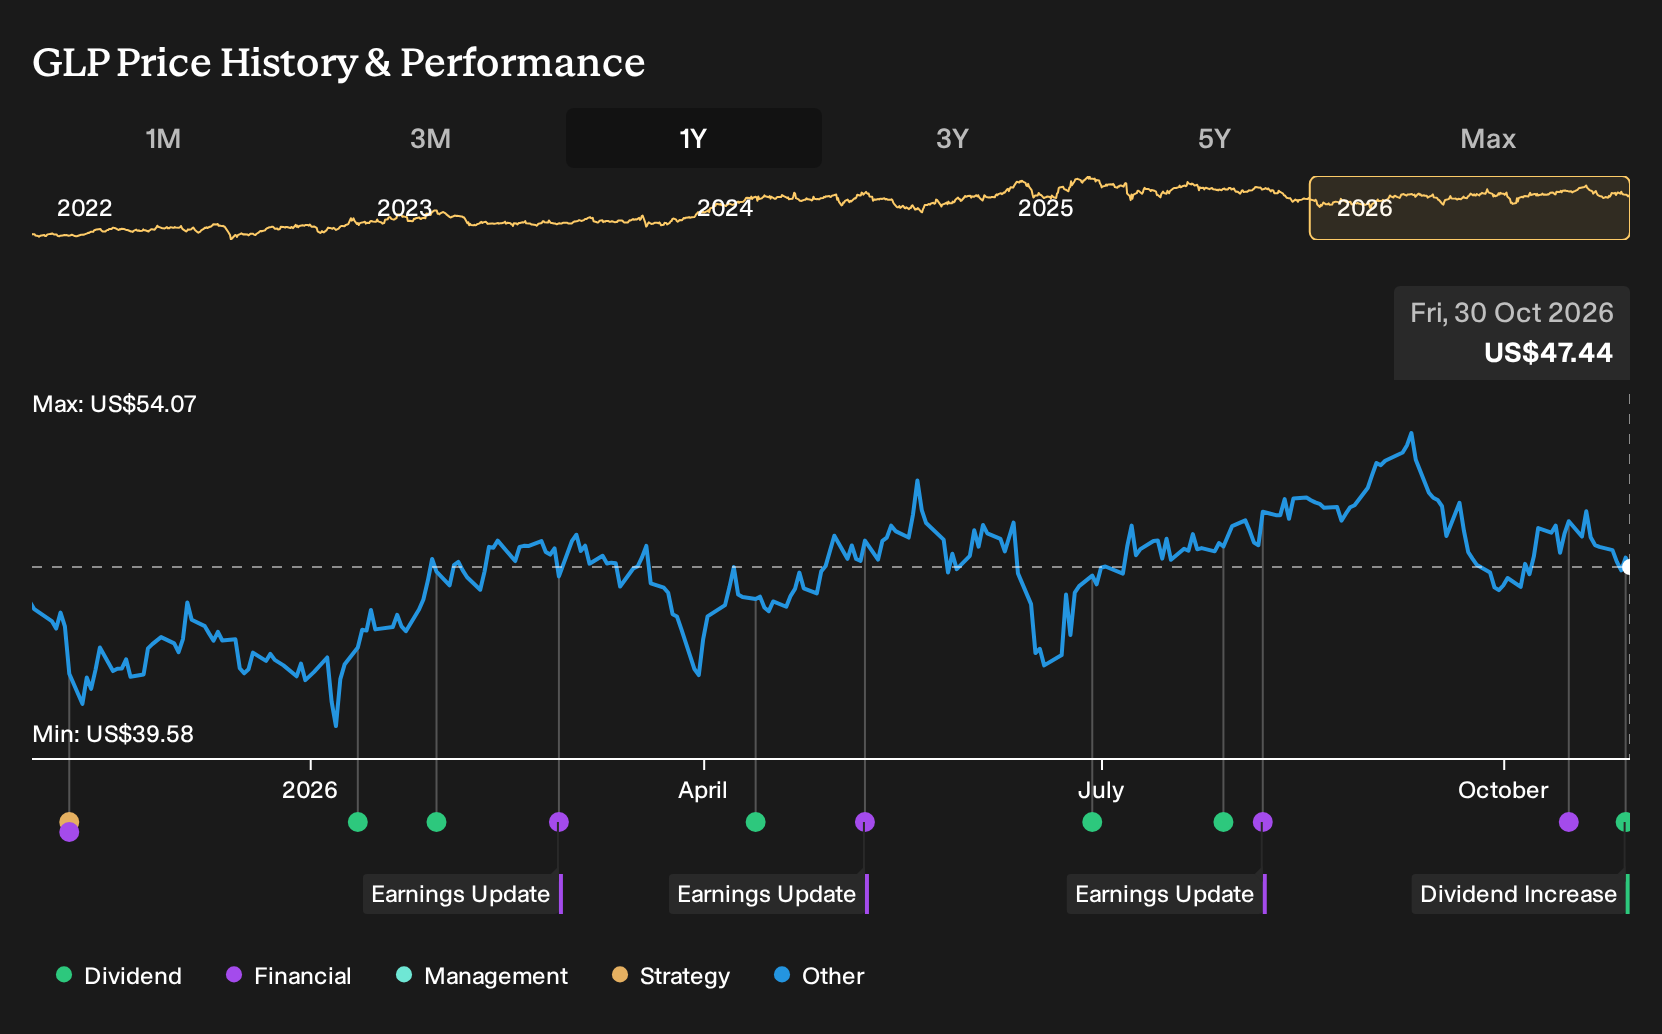
- Global Partners LP previously declared a quarterly cash distribution of $0.7850 per unit, or $3.14 on an annualized basis, for the July to September 2026 period, payable on November 13, 2026 to unitholders of record on November 9, 2026.
- The higher cash payout indicates that Global Partners' board sees sufficient distributable cash flow from its fuel distribution and retail operations to support an increased return of capital to unitholders.
- We will now look at how Global Partners' higher quarterly cash distribution could influence the existing investment narrative around cash flows.
Global Partners Investment Narrative Recap
To own Global Partners, you need to be comfortable with a midstream and fuel distribution business that leans heavily on gasoline, diesel and related products, while trying to keep throughput volumes healthy across Wholesale, GDSO and Commercial segments. The higher cash distribution signals confidence in current distributable cash flow, but the near term swing factor still sits in fuel demand resilience and operating margins across those units.
The biggest operational risk in the short run remains balance sheet pressure, since interest costs are not well covered by earnings and dividend consistency has been mixed. If funding costs rise or volumes soften, the new payout could prove less important than management’s ability to protect cash generation and maintain sensible leverage.
The fresh US$0.7850 per unit cash distribution, or US$3.14 on an annualized basis, is the most relevant recent update for Global Partners because it directly touches the income thesis. This payout leans on a business that already carries higher risk funding, with liabilities fully reliant on external borrowing rather than lower risk customer deposits.
For you, the link back to catalysts is simple. Any benefit from network expansion, portfolio pruning of weaker sites and revenue growth expectations only matters if those moves translate into steady cash that can service interest and still support distributions. If operational execution stumbles, the combination of debt costs and an unstable dividend history could weigh more heavily on the story.
Global Partners Forecasts Behind The Higher Distribution
Global Partners' narrative projects US$42.5b revenue and US$168.5m earnings by 2029. This rests on analysts assuming 30.1% yearly revenue growth and an earnings increase of about US$45.9m from US$122.6m today.
Uncover how Global Partners' fair value points to a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The Simply Wall St Community has only two fair value estimates for Global Partners, ranging from US$45.50 up to about US$120.64 per unit. This is a huge spread for one business. That kind of gap highlights how differently people frame long term fuel demand, energy transition risk and the future role of Global Partners' asset base. You should treat this as a prompt to compare several viewpoints rather than rely on any single number.
Explore another Global Partners fair value estimate, including one that suggests potential upside of up to 154% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Global Partners research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Global Partners. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Global Partners' overall financial health at a glance.
Looking for more investment ideas beyond Global Partners?
Once you have formed a view on Global Partners, it can help to widen the lens and line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If you want income potential with a focus on resilience, start by scanning a curated 5 dividend fortresses that can help you compare yields, balance sheet strength and payout histories side by side.
- For investors who care most about paying a sensible price for quality, use the 33 high quality undervalued stocks to spot businesses where fundamentals and valuation checks look more aligned.
- If you are hunting for fresh ideas off the beaten path, filter through the 19 high quality undiscovered gems and see which smaller opportunities match your return and risk preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com