


Reply (BIT:REY) Could Be 21% Over Fair Value After GitHub Award Win
Reply (BIT:REY) is back in focus after being named EMEA winner in GitHub’s 2026 Services and Channel Partner of the Year Awards, putting its software modernization work under a brighter spotlight for investors.
Reply’s recent GitHub recognition lands at a time when momentum in the shares has been picking up, with the 30-day share price return of 9.5% and year-to-date gain of 20.56% contrasting with a 5-year total shareholder return that is down 21.55%, highlighting a recovery phase after a weaker longer stretch.
Scan beyond Reply to see which peers are also riding the software modernization and AI tailwind in our hand picked 41 profitable AI stocks that aren't just burning cash list.
Reply has just put in a strong short term run, yet the five year return still sits in negative territory. Is this the moment to commit fresh capital or wait for a more forgiving entry as valuation markers line up?
Preferred P/E of 18.9x for Reply: Is it justified?
Reply trades on a P/E of 18.9x, which sets a richer bar compared to peers even as the share price sits at €133.7 after a strong recent run.
The P/E ratio compares what investors pay today to the earnings the business generates, which matters a lot for a software and services group like Reply where profit quality and consistency are central. For a firm reporting €2,535.4m in revenue and €258.0m in net income, this yardstick helps you see how much of a premium the market is attaching to those profits.
On one side, Reply is flagged as expensive against both its direct peer group on 12x P/E and the broader European IT sector on 17.8x. This suggests investors are agreeing to pay more for each euro of earnings than they would for rivals. On the other side, the estimated fair P/E of 32.6x is far higher than the current 18.9x. This signals a large gap between what the market currently pays and the level the fair ratio suggests it could move toward if the firm keeps backing up its earnings record.
Explore the SWS fair ratio for Reply.
Result: Price-to-earnings of 18.9x (ABOUT RIGHT)
Still, Reply’s pitch can wobble if demand for consulting and integration projects cools, or if rivals undercut pricing in key industries such as financial services and telecoms.
Find out about the key risks to this Reply narrative.
Another View on Reply’s value using cash flows
The P/E story for Reply looks forgiving, yet the SWS DCF model tells a cooler story. On that approach, the shares at €133.7 sit above an estimated future cash flow value of €110.39, which points to an overvalued tag instead of a bargain. Which lens do you trust more when money is on the line?
Look into how the SWS DCF model arrives at its fair value.
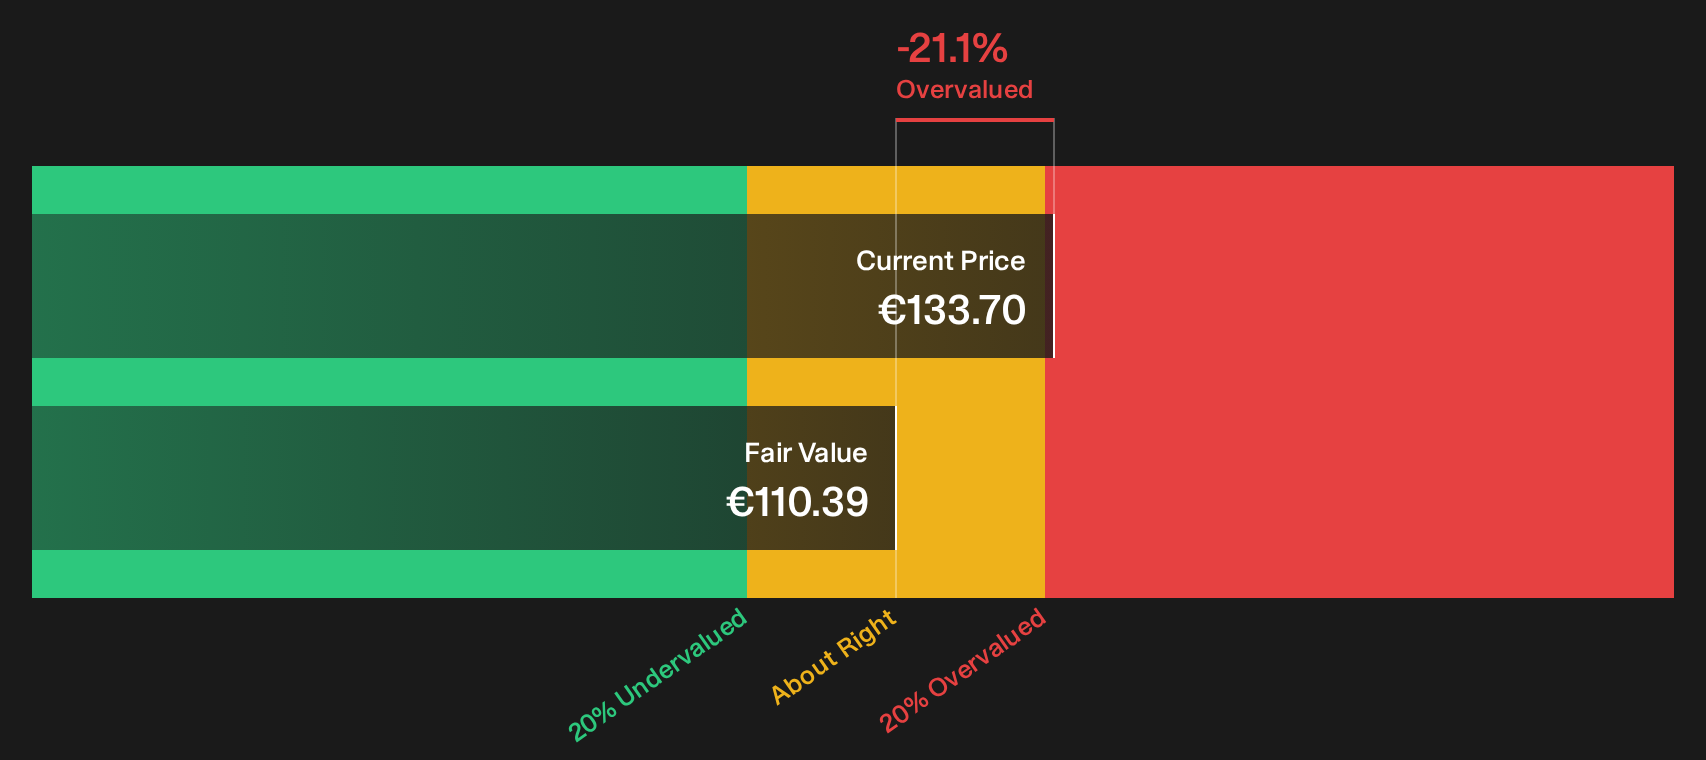
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Reply for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Reply leave you on the fence, use that hesitation as a prompt to move fast and inspect the details yourself. Then pressure test the upside case with the 2 key rewards.
Looking for more investment ideas beyond Reply?
Do not stop at Reply. The next strong opportunity in your portfolio could come from a corner of the market you have not checked yet.
- Target resilience with companies that pair financial strength and manageable risk by reviewing the 218 resilient stocks with low risk scores.
- Hunt for potential bargains where quality and pricing line up more tightly by scanning the 204 high quality undervalued stocks.
- Build a shortlist of under-the-radar opportunities that many investors have not researched yet with the 614 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com