


Is SITC International Holdings (SEHK:1308) Undervalued As Revenue Growth And A Special Dividend Lift Sentiment?
Revenue update and special dividend set the tone
SITC International Holdings (SEHK:1308) just paired a trading update with a special dividend announcement, giving investors fresh data on operations and a defined near term cash payout timeline to assess.
The fresh trading update and special dividend have landed after a powerful run in SITC International Holdings, with a 90 day share price return of 22.19% and a year to date share price gain of 71.43%. This has fed into a 1 year total shareholder return of 84.10%, and an even stronger 3 year total shareholder return of more than 4x that suggests momentum may currently be in play.
Scan how SITC International Holdings compares with other shipping and logistics stocks that have recently shown strong momentum and cash generation traits by reviewing the curated list of solid balance sheet and fundamentals (199 results).
After a sharp re rating in SITC International Holdings, the stock now trades slightly above the average analyst target, yet it still screens at a sizeable discount to estimated intrinsic value. Is the market’s caution already stretched, or is it still warranted as you test the valuation numbers next?
Preferred P/E of 13.1x for SITC International Holdings: Is it justified?
SITC International Holdings is flagged as expensive on a P/E basis, trading at 13.1x earnings while the last close sits at HK$48.24 and the SWS DCF model still points to a fair value of HK$70.65. That mix of a premium earnings multiple and a sizeable DCF gap gives you two very different valuation signals to weigh against each other.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a shipping and logistics group like SITC International Holdings, where earnings can be influenced by freight rates, capacity and trade flows, the P/E is often read as the market’s view on how durable current profitability might be.
Here the P/E of 13.1x sits above both the Asian shipping industry average of 11.4x and the peer group average of 10.3x. This implies investors are paying a clear premium versus comparable stocks. The same checks show this multiple is also higher than an estimated fair P/E of 9.2x, a level the market could move towards if sentiment cools or if earnings expectations are revised.
Explore the SWS fair ratio for SITC International Holdings.
Result: Price-to-earnings of 13.1x (OVERVALUED)
Still, revenue growth of 1.9% alongside a decline of 3.9% in net income leaves SITC International Holdings exposed if freight conditions or pricing power weaken further.
Find out about the key risks to this SITC International Holdings narrative.
Another view on SITC International Holdings’ valuation
The SWS DCF model points in the opposite direction to the P/E story. At HK$48.24, SITC International Holdings is flagged as trading at a 31.7% discount to an estimated fair value of HK$70.65, which frames current pricing as potentially conservative rather than stretched.
For anyone weighing how that cash flow view is built, it can help to walk through the moving parts instead of focusing only on the headline discount. Look into how the SWS DCF model arrives at its fair value.
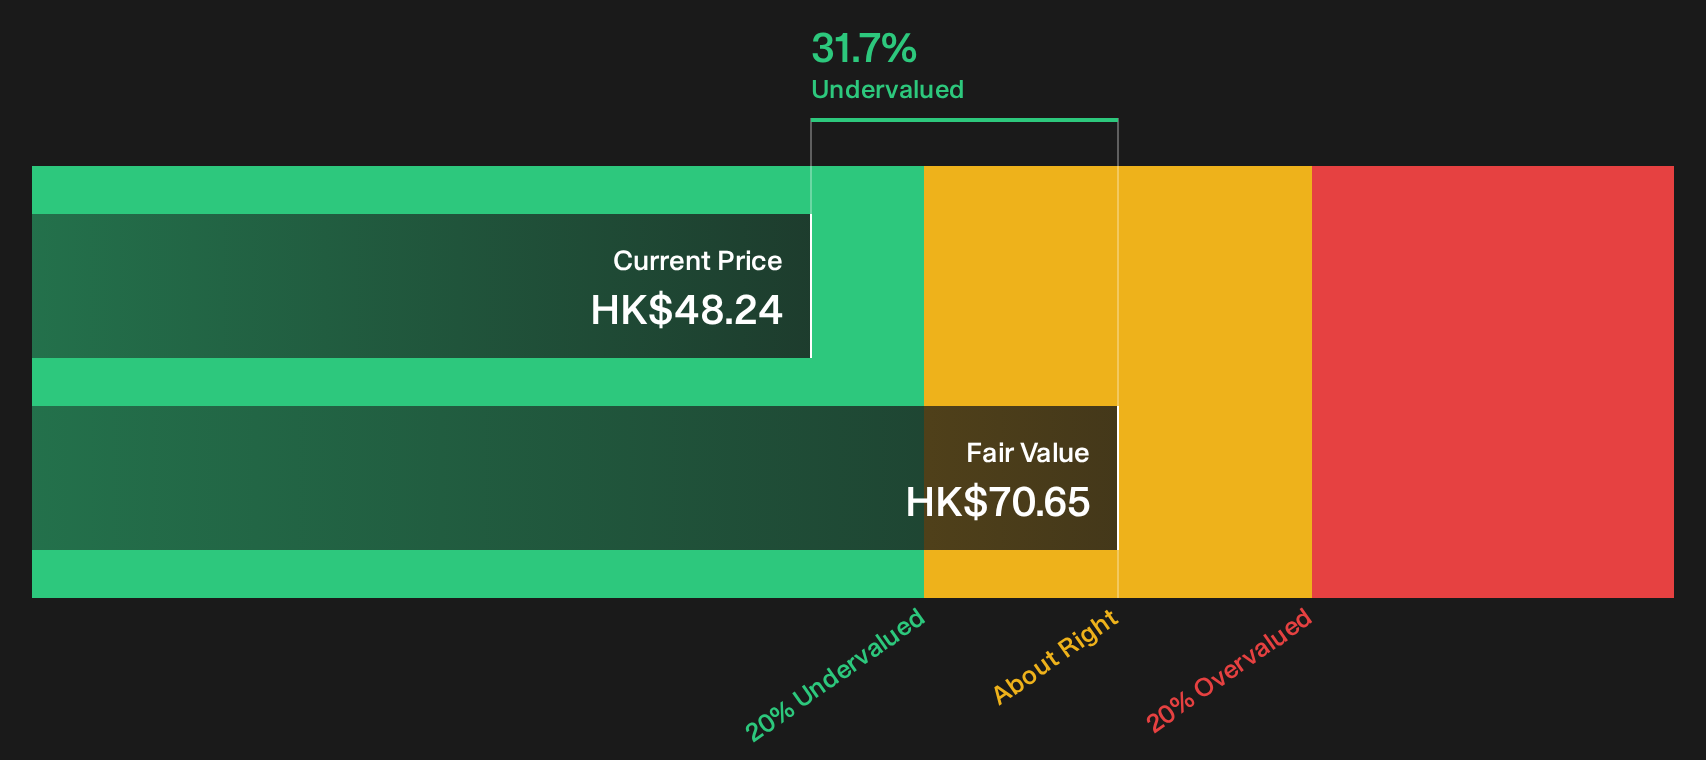
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SITC International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 204 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around SITC International Holdings can feel messy, so move quickly, weigh the data for yourself, and then pressure test that view against the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond SITC International Holdings?
If the mixed signals around SITC International Holdings have sharpened your focus, you can use that momentum to scan broader opportunities with targeted screeners built from real fundamentals.
- Pinpoint value by reviewing companies that combine quality fundamentals with attractive pricing through the 204 high quality undervalued stocks.
- Strengthen your income watchlist by tracking dependable yield opportunities inside the 222 dividend fortresses.
- Dial down potential stress by focusing on resilient businesses with healthier financial profiles using the 218 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com