


Is Astellas Pharma (TSE:4503) Fully Valued After Its $1.34b DAX 044 Oncology Deal?
Astellas Pharma (TSE:4503) just signed an exclusive option and license agreement with Audax Biosciences for DAX-044, an immuno-oncology AVIKINE candidate, in a deal valued at up to US$1.34b.
The Audax agreement lands while Astellas Pharma’s recent share price return has been strong, with a 30-day gain of 11.27% feeding into a 90-day move of 16.76% and year to date share price return of 20.70%, alongside a 1-year total shareholder return of 64.56%. This points to momentum that investors may now be weighing against pipeline risks and execution on deals like DAX-044.
Spot similar oncology-driven opportunities by scanning our curated list of 10 healthcare AI stocks, which also focus on next generation therapies and platform technologies as potential drivers of their next leg of momentum.Astellas Pharma now trades slightly above analyst targets yet still screens at a sizeable intrinsic discount. Is the market rightly cautious about execution and earnings pressure, or is it mispricing that gap?
Most Popular Narrative: 2% Overvalued
Astellas Pharma last closed at ¥2,571 against a narrative fair value of ¥2,529, so the prevailing view is that the shares trade slightly ahead of that framework while still hinging on how XTANDI pressure is managed over the coming years.
The main thing that has to go right is successful execution on margin expansion and R&D productivity plans so that strategic brands and late stage programs can offset XTANDI pressure and pricing headwinds.
The current numbers and guidance imply a share price that already reflects a fairly valued, more diversified Astellas Pharma with meaningful exposure to XTANDI loss of exclusivity and U.S. pricing constraints, which this narrative views as bearish.
See why 4 investors see Astellas Pharma as 2% overvalued.
Result: Fair Value of ¥2,529 (OVERVALUED)
Still, pressure on U.S. drug pricing and the shift away from XTANDI’s ¥960.8b peak sales could easily upset the current Astellas Pharma fair value story.
Find out about the key risks to this Astellas Pharma narrative.
Another View: Astellas Pharma Through The P/E Lens
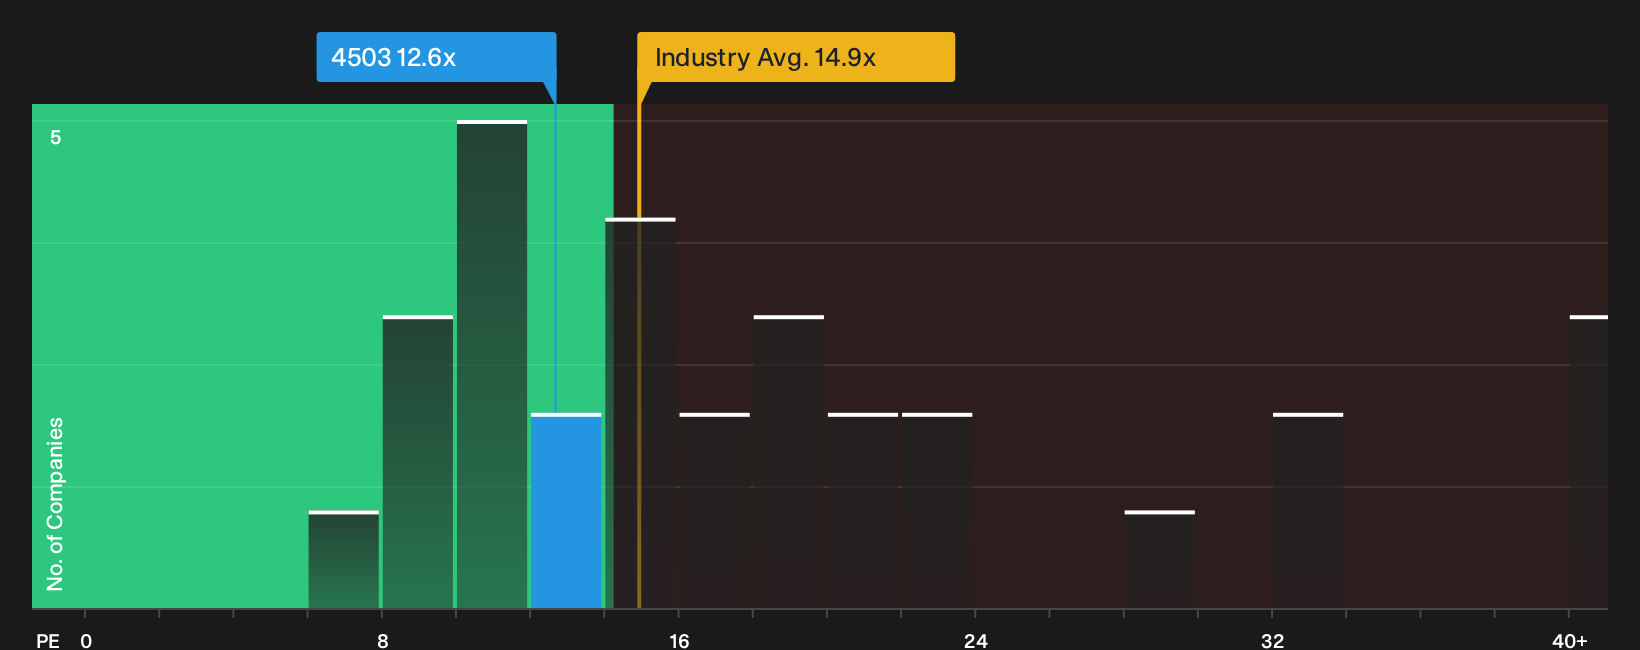
The first fair value framework flags Astellas Pharma as slightly overvalued, yet the simple earnings multiple paints a different picture. The shares change hands at a P/E of 12.6x, compared with 17.1x for peers and 14.1x for the JP Pharmaceuticals industry, while the fair ratio sits at 19.8x. That gap suggests the market is pricing in meaningful execution and earnings risk, so the key question is whether those concerns are fully justified or overly harsh on the current fundamentals.
To see what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Astellas Pharma feels familiar, act while the facts are fresh and weigh the trade off yourself. To see how current optimism and concern stack up side by side, review the 4 key rewards and 1 important warning sign
Looking for more Astellas Pharma sized ideas?
You have fresh context on Astellas Pharma right now, so put it to work and line up a few more candidates before the next headline hits.
- Target resilient compounding potential by scanning a 28 dividend fortresses that can help anchor returns when other positions feel volatile.
- Hunt for mispriced quality through a 69 high quality undiscovered gems that highlights financially sound businesses still flying under most radars.
- Dial back downside risk by focusing on a 23 resilient stocks with low risk scores designed to surface companies with sturdier overall profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com