


PACS Group (PACS) Faces Medicare Fraud Suit As Investors Weigh Its Valuation
Why a Medicare fraud lawsuit now sits at the center of the PACS Group story
PACS Group (PACS) is under sharper scrutiny after an investor lawsuit in the Southern District of New York claimed the business relied on allegedly false Medicare billings and misleading disclosures between 2020 and 2023.
The complaint alleges improper Medicare claims for therapies, falsified licensure and staffing records, and that these practices allegedly underpinned more than 100% of reported operating and net income. A consolidated amended complaint arrived in December 2025, and management responded with a motion to dismiss filed on February 17, 2026.
For anyone tracking PACS Group stock today, this legal overhang is a key event to understand before looking at the current share price or recent returns.
PACS Group’s latest legal headlines land after a powerful run in the stock, with the 1-year total shareholder return near 3x and a year to date share price gain of 21.01% from a recent close of $47.81.
In the short term, the share price fell 3.76% over the last day but remains up 11.58% over 30 days and 7.44% over 90 days. This suggests that investors may be reassessing risk rather than fully abandoning the earlier momentum around PACS Group.
Spot other healthcare operators where the story is less clouded by litigation risk by scanning our hand-picked 29 resilient stocks with low risk scores featuring resilient balance sheets and steadier risk profiles.PACS Group has surged, even with a serious Medicare lawsuit hanging over past profits. Do you pay up now for that momentum, or wait for a cleaner entry as the valuation picture comes into focus?
Most Popular Narrative: 20% Undervalued
PACS Group last traded at $47.81, while the most followed narrative framework pegs fair value at $59.75. This frames current pricing as meaningfully below that reference point and puts a spotlight on what might justify the gap.
Systematic improvement of newly acquired and turnaround facilities from low single digit margins toward the high single digit and low double digit margin profile of mature sites should unlock embedded profitability, lifting consolidated net margins and EBITDA over time.
See why 14 investors see PACS Group as 20% undervalued.
The fair value work behind that $59.75 figure uses a 7.5% discount rate and incorporates both higher forecast revenue growth of 8.88% and a slightly lower net profit margin assumption of 6.44%. It also leans on a future P/E of 26.21x, which is higher than the US Healthcare sector multiple of 25.8x mentioned in the widely followed narrative. As a result, the valuation view assumes the market will be comfortable paying a premium if PACS Group meets those profit targets.
Analysts referenced in the narrative cluster price targets close to that fair value mark, with a range in the high $50s, and see forecast earnings rising from $269.2m to $461.5m over the coming years. That kind of earnings path, combined with a premium multiple, is doing most of the heavy lifting in the valuation story. This means anyone assessing PACS Group today is really deciding how much confidence to place in those longer term margin and growth expectations while a Medicare fraud lawsuit and past governance issues remain in the background.
Result: Fair Value of $59.75 (UNDERVALUED)
Still, the Medicare fraud lawsuit and any renewed questions about internal controls or compliance could quickly challenge the PACS Group fair value story that investors are leaning on.
Find out about the key risks to this PACS Group narrative.
Another View: PACS Group through the earnings multiple lens
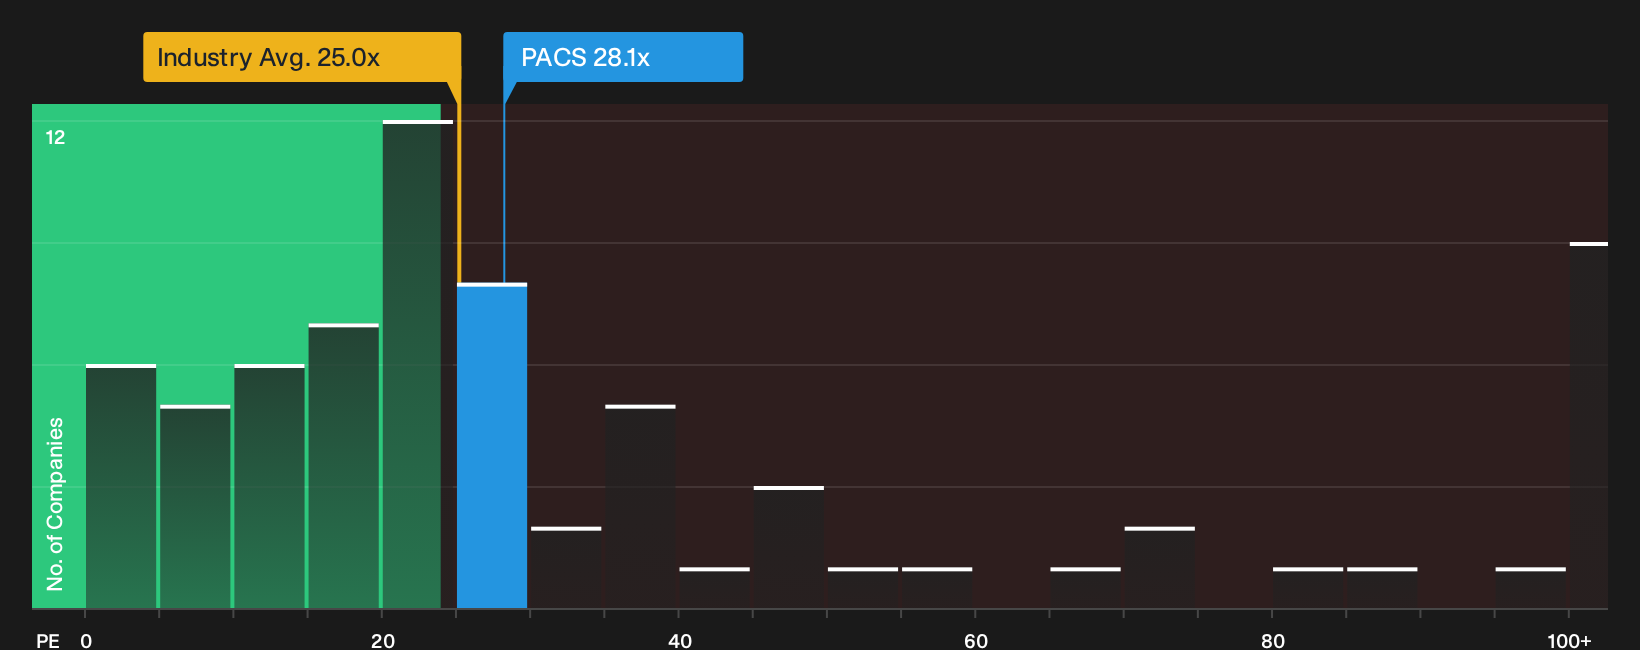
The fair value story around PACS Group leans on future forecasts, yet the current P/E of 28.1x already sits above both the US Healthcare sector at 25x and the peer average at 20.3x. At the same time, the fair ratio suggests 40.8x as a level the market could move toward, which leaves you deciding whether today’s price reflects stretched expectations or room for re rating if those earnings arrive.
To see how this P/E picture fits with your own expectations, it helps to walk through the full valuation breakdown and compare PACS Group with peers using the same yardstick. You can then decide where the real risk or opportunity lies in that gap. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about PACS Group after all of this, and wondering what really matters most for your own portfolio? The fastest way to ground that view in hard evidence is to weigh both sides of the ledger with our 3 key rewards and 1 important warning sign.
Looking for more PACS Group sized opportunities?
If PACS Group leaves you uncertain, use that as a prompt to refresh your broader watchlist with ideas that match your risk, income, and value preferences.
- Chase value by lining up stocks trading below their estimated worth through our 33 high quality undervalued stocks and see which businesses might warrant a closer look.
- Lock in potential income streams by reviewing the 5 dividend fortresses that highlight companies with higher yields and sturdier payout records.
- Stress test your downside protection by scanning the list of solid balance sheet and fundamentals (24 results) for businesses carrying stronger finances and more resilient balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com