


AptarGroup (ATR) Shares Just Climbed, What Is Driving Attention Now?
Why AptarGroup’s latest earnings matter
AptarGroup (ATR) just paired higher third quarter sales with weaker profitability, as emergency medicine destocking and softer Beauty and Closures margins weighed on earnings, which is what has drawn fresh investor attention.
The earnings surprise has arrived alongside a sharp swing in AptarGroup’s trading, with a 1 month share price return of 14.42% and a 7 day move of 8.42% pushing the stock to about $137.20. A 1 year total shareholder return of 19.61% points to momentum that has been building rather than fading.
Scan how AptarGroup’s latest earnings and dividend move stack up against other packaging and materials stocks with 29 resilient stocks with low risk scores that pair resilient balance sheets with steadier fundamentals.
AptarGroup now appears to be a strong operator with a more mixed earnings story and a sharply higher share price. The real question is whether that quality is already fully reflected in what you pay today.
Most Popular Narrative: 15% Undervalued
AptarGroup’s most followed valuation story pegs fair value around $162 per share, compared with the latest close near $137. This puts the recent rally into context rather than calling it excessive. That gap rests on the idea that the higher margin Pharma engine and capacity buildout are not fully reflected in today’s price.
Ongoing work to move from component supplier to a more integrated drug delivery and services partner, including formulation, analytical and regulatory support, clinical filling and digital patient tools, increases customer dependence on AptarGroup and can support higher value revenue and more resilient net margins.
See why 7 investors see AptarGroup as 15% undervalued.
Result: Fair Value of $162 (UNDERVALUED)
Still, the emergency medicine destocking that is expected to trim about US$65 million from 2026 Pharma sales and the ongoing legal expenses could easily pressure that upside story.
Find out about the key risks to this AptarGroup narrative.
Another view on AptarGroup’s valuation
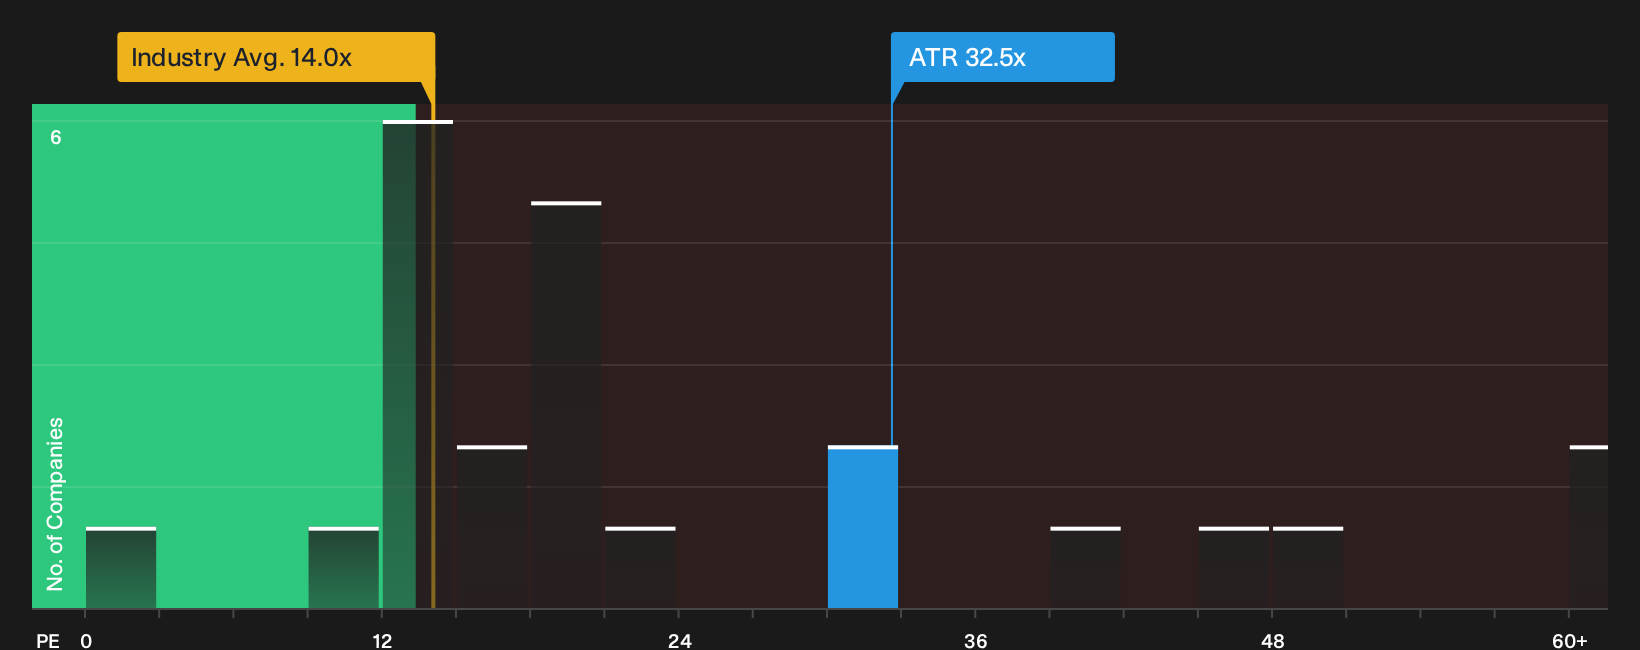
The story flips when you look at AptarGroup through its P/E. The stock trades on about 32.5x earnings, compared with 13.8x for the global packaging industry and a 19.8x fair ratio estimate. That is a rich gap, and it raises a simple question: How confident are you that the higher rating sticks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about AptarGroup’s premium valuation and its Pharma engine are normal, so move fast and stress test the story against the underlying numbers yourself with 3 key rewards and 3 important warning signs
Looking for more investment ideas beyond AptarGroup?
If AptarGroup has sharpened your focus, do not stop here. Apply the same disciplined lens to a wider set of opportunities using targeted stock lists on Simply Wall Street.
- Look for potential mispricings early by scanning a 33 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Explore steadier income streams by reviewing 5 dividend fortresses that combine higher yields with an emphasis on durability.
- Guard your capital by starting with a 29 resilient stocks with low risk scores that screens for resilient companies with stronger balance sheets and fewer red flags.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com