


Perella Weinberg Partners (PWP) On Strong Q3 Results And A Steady Dividend Looks Fully Valued
Perella Weinberg Partners (PWP) has become a talking point after Q3 2026 results showed net income of US$17.56 million and higher earnings per share, alongside the board affirming a US$0.07 quarterly dividend.
The stronger Q3 release has already fed into trading, with Perella Weinberg Partners’ share price jumping 5.21% on the day of the results and gaining 18.98% over the past week. However, the 90-day share price return is still down 14.21%, and the 1-year total shareholder return is down 19.93%, despite a 48.69% total shareholder return over three years that indicates earlier momentum which has cooled recently.
Spot under-the-radar advisory firms that show similar earnings momentum and dividend discipline as Perella Weinberg Partners by scanning our curated list of 19 high quality undiscovered gems.Perella Weinberg Partners now splits opinion. Bulls point to the sharp Q3 rebound and steady dividend, while bears focus on a weak 1 year return and thin margins. Which case does the valuation actually support next?
Price-to-Earnings of 35.4x: Is it justified?
On current numbers, Perella Weinberg Partners changes hands at a P/E of 35.4x while the broader Capital Markets industry sits at 37.1x, and peer companies across its own comparison group average 22.1x. That leaves the stock priced close to the wider sector but clearly richer than its direct peer set.
The P/E ratio compares the share price to earnings per share and gives a rough sense of how much investors are willing to pay for each dollar of profit. For an advisory firm like Perella Weinberg Partners, this matters because earnings can be influenced by deal activity, one off items and margin swings, so a high multiple often reflects expectations that profitability will improve or at least hold up.
Screening outputs flag that the market is assigning a premium tag to PWP relative to its specific peer average at 22.1x. At the same time, the stock is described as good value against the broader US Capital Markets group at 37.1x. This suggests buyers are paying less than the wider sector for the same dollar of earnings while still giving the business a higher valuation than closer comparables.
Relative to the industry, the wording is clear. PWP is considered expensive versus peers on a P/E basis, yet marginally attractive when set against the full Capital Markets benchmark. That split view lines up with the mixed track record, including declining profit margins to 4.3% from 6.2% and a low 11.8% return on equity, alongside revenue that is forecast to grow 17.3% per year, faster than the US market but slower than a high growth threshold of 20%.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 35.4x (ABOUT RIGHT)
Still, the thin 4.3% profit margin and weak 1 year return raise the risk that any slip in deal activity could pressure Perella Weinberg Partners’ premium P/E ratio.
Find out about the key risks to this Perella Weinberg Partners narrative.
Another view on Perella Weinberg Partners’ valuation
The P/E comparison paints PWP as roughly in line with the broader Capital Markets group. A different tool tells a sharper story. Simply Wall St’s DCF model estimates future cash flow value at $6.63 per share versus a recent price of $14.73, which implies the stock screens as overvalued on that basis.
For readers who rely more on cash flow maths than earnings multiples, this gap suggests less room for error if revenue forecasts or margins disappoint. Look into how the SWS DCF model arrives at its fair value.
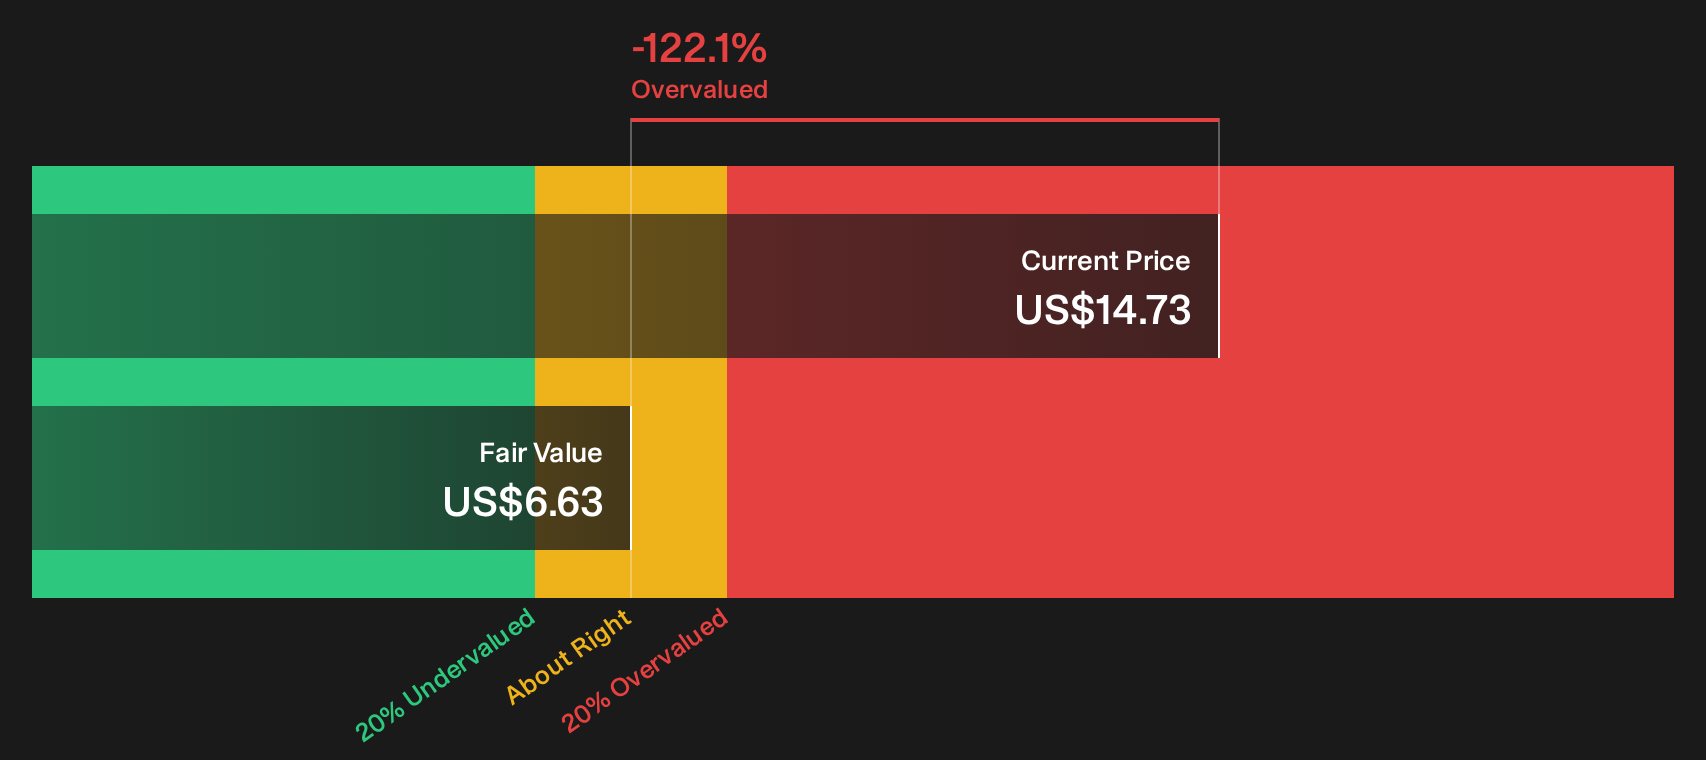
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Perella Weinberg Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Perella Weinberg Partners so far. If you want to move quickly and form your own take based on the underlying data, weigh both sides of the story with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Perella Weinberg Partners?
If Perella Weinberg Partners has sharpened your focus on valuation and quality, do not stop here. Broaden your opportunity set with a few targeted stock searches.
- Target potential mispriced opportunities early by scanning a curated pool of 33 high quality undervalued stocks that pair earnings power with more reasonable market expectations.
- Strengthen your income watchlist by focusing on companies in the 5 dividend fortresses that match higher yields with disciplined payout histories.
- Protect your capital on the downside by filtering for companies in the 29 resilient stocks with low risk scores that combine durability scores with steadier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com