


How Investors Are Reacting To TriNet Group (TNET) Reaffirmed Earnings Guidance
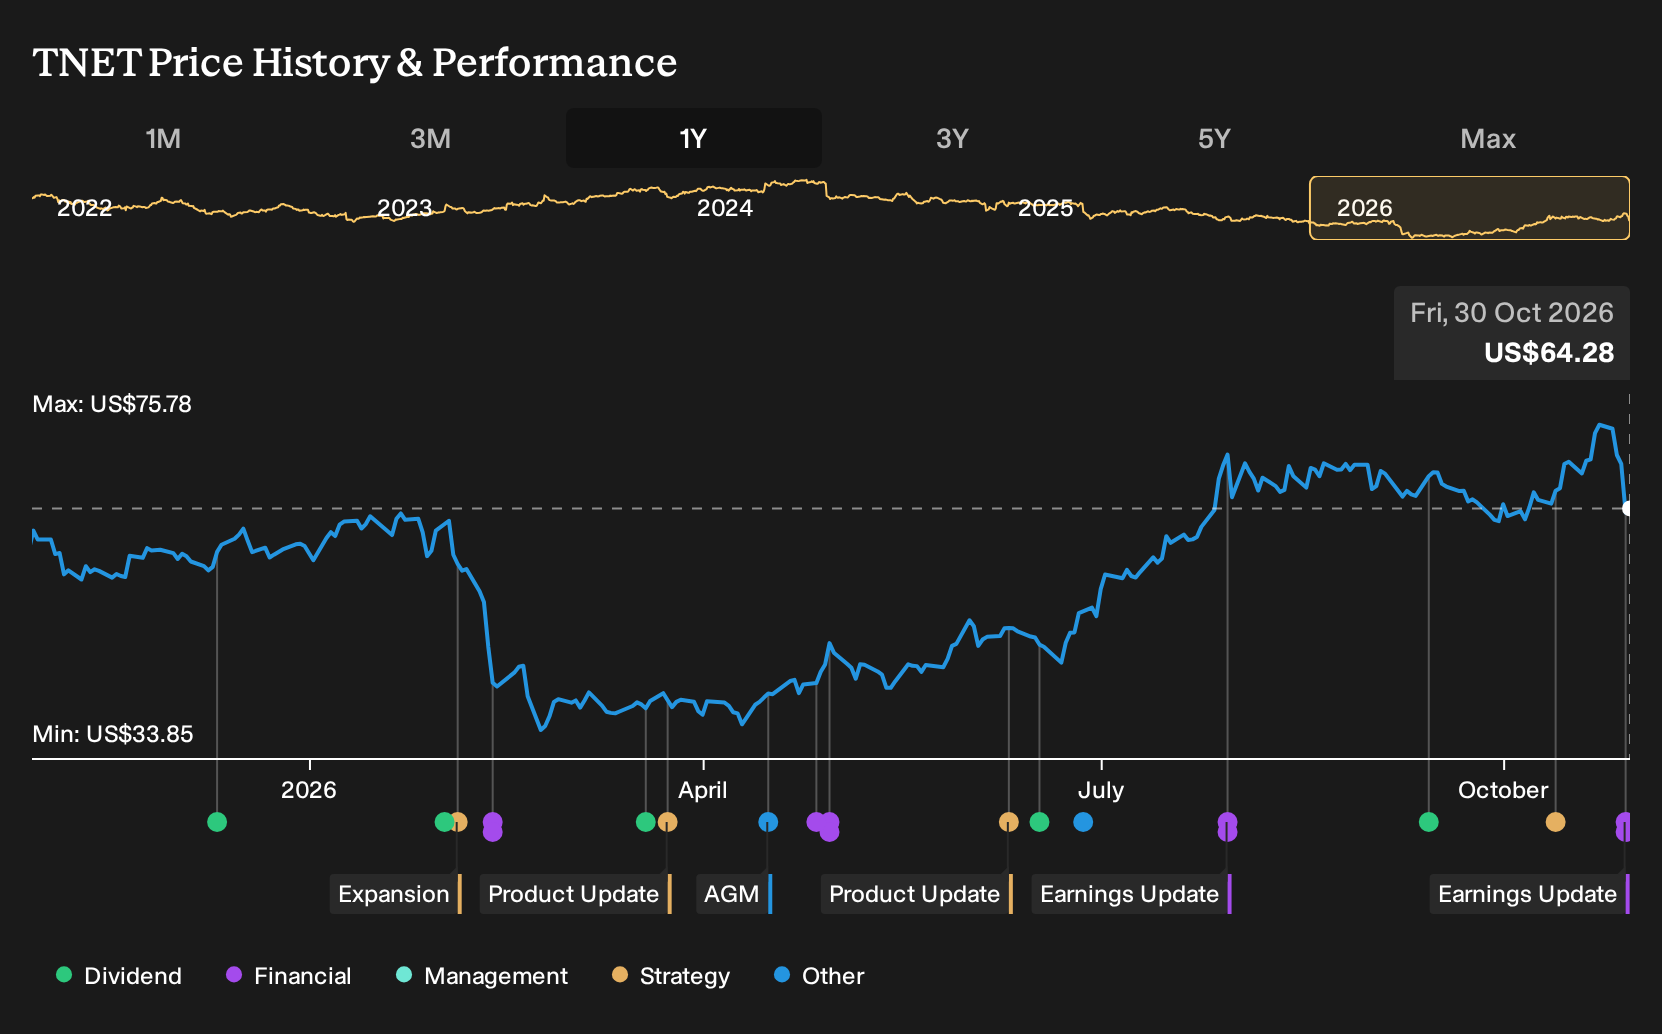
- TriNet Group reported third quarter 2026 revenue of US$1,175 million and net income of US$31 million, reaffirming full year revenue and diluted EPS guidance despite pressure from lower worksite employee volumes after health plan repricing.
- Insurance performance improved, with the insurance cost ratio back inside management’s target range and customer retention and new sales showing signs of recovery. This supports the earnings outlook even as hiring trends and health cost pressures remain important watchpoints.
- We will look at how TriNet Group's reaffirmed full year earnings guidance shapes the investment narrative around its HR outsourcing platform.
Scan other HR and payroll platforms that combine recurring fee income with disciplined risk control through our handpicked list of solid balance sheet and fundamentals (24 results) as a comparison point for TriNet Group’s latest guidance and insurance reset.
TriNet Group Investment Narrative Recap
To own TriNet Group, you need to believe its HR outsourcing platform can offset softer worksite employee volumes with better pricing discipline, broader products and AI driven efficiencies. The third quarter showed revenue and quarterly earnings slightly lower than a year ago, but nine month profit and EPS still higher, which keeps that thesis intact for now.
The key near term swing factor remains whether worksite employee counts and client retention stabilise after the health plan repricing. The biggest risk is still health cost inflation that runs hotter than expected and squeezes the insurance cost ratio again. This update does not remove that risk, but an 89% ratio inside target helps contain it.
The most relevant update is TriNet Group reaffirming full year 2026 guidance for total revenue of US$4,750 million to US$4,900 million and diluted EPS of US$2.85 to US$3.35. Management now expects earnings toward the top of that EPS range, which indicates cost control and insurance profitability are offsetting the drag from weaker volumes.
That guidance, combined with improved insurance performance and early signs of better customer retention and sales, keeps the main catalyst squarely on execution around distribution, AI tools and product breadth. On the other side of the ledger, the shares still screen as expensive versus a tailored fair multiple model, so debate among investors remains focused on whether this profitability profile justifies the current P/E.
TriNet Group's consensus story assumes revenue of US$5.2b and earnings of US$164.8 million by 2029, based on analysts modelling 2.2% yearly revenue growth. That outlook implies earnings declining by US$10.2 million from US$175.0 million today to reach the US$164.8 million forecast in 2029.
Uncover how TriNet Group's fair value indicates a 3% potential upside to its current price. This upside could narrow quickly if TriNet Group keeps executing on this guidance.
Exploring Other Perspectives
For TriNet Group, the bullish twist in the story is earnings power. The most optimistic analysts were pencilling in US$5.3b of revenue and about US$204.6 million of earnings by 2029 before this earnings release, which is far above the US$164.8 million consensus path. Use that spread as a prompt to explore how your own expectations could shift after this new guidance.
Explore 3 other TriNet Group fair value estimates, including one that suggests as much as 275% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TriNet Group research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TriNet Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TriNet Group's overall financial health at a glance.
Looking for more investment ideas beyond TriNet Group?
If the TriNet Group story has sharpened your view on quality, income and risk, use that same lens on a wider watchlist. The Simply Wall St Screener can help you quickly filter for businesses that better match your return goals and risk comfort level.
- For investors who want quality at a reasonable entry point, scan a curated set of companies that combine strong fundamentals with attractive pricing using the 33 high quality undervalued stocks.
- If capital protection matters just as much as upside, focus on companies that aim to keep balance sheets robust and risk profiles measured through the 29 resilient stocks with low risk scores.
- When you are hunting for opportunities the crowd might be overlooking, broaden your radar with a carefully filtered pool of underfollowed stocks through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com