


Imerys (ENXTPA:NK) Faces A 2% Fair Value Gap On Mixed Earnings
Imerys earnings trigger mixed reaction
Imerys (ENXTPA:NK) just posted third quarter 2026 results, with sales of €884 million and net income of €43 million, alongside softer nine month profitability that is giving investors more to think about.
Imerys shares have surged on the results, with a 1 day share price return of 13.84% and a 7 day gain of 18.41% at €25.34. That short term momentum contrasts with a more modest 5.67% year to date share price return and a 1 year total shareholder return of 22.69%, which together suggest sentiment has recently improved as investors reassess both earnings risks and longer term potential.
Spot potential follow through by comparing Imerys with other materials businesses showing strong momentum and fundamentals in our curated 614 high quality undiscovered gems.After a 14% one-day jump, and with Imerys trading only slightly below the average analyst target yet at a sizeable discount to some fair value estimates, the question is where a reasonable valuation actually lands now.
Most Popular Narrative: 2% Overvalued
On the most followed view, Imerys carries a fair value of €24.82 compared with the latest close at €25.34, which leaves only a small valuation gap and puts more weight on how its long term projects actually play out.
The EMILI lithium project's commercial production is delayed until at least 2030, and with current lithium prices at ~$10/kg (down 85% from project planning) and CapEx up 80% to €1.8 billion due to inflation and ESG compliance, the project is not viable at present price levels. It requires lithium prices to rise by 30 to 40% just to break even, posing long-term risks to revenue growth, ROI, and balance sheet leverage.
See why 8 investors see Imerys as 2% overvalued.
Result: Fair Value of €24.82 (OVERVALUED)
Still, the EMILI lithium project's higher €1.8b CapEx and delay to at least 2030, along with ongoing US litigation exposure, could easily upset the current Imerys narrative.
Find out about the key risks to this Imerys narrative.
Another view on Imerys valuation
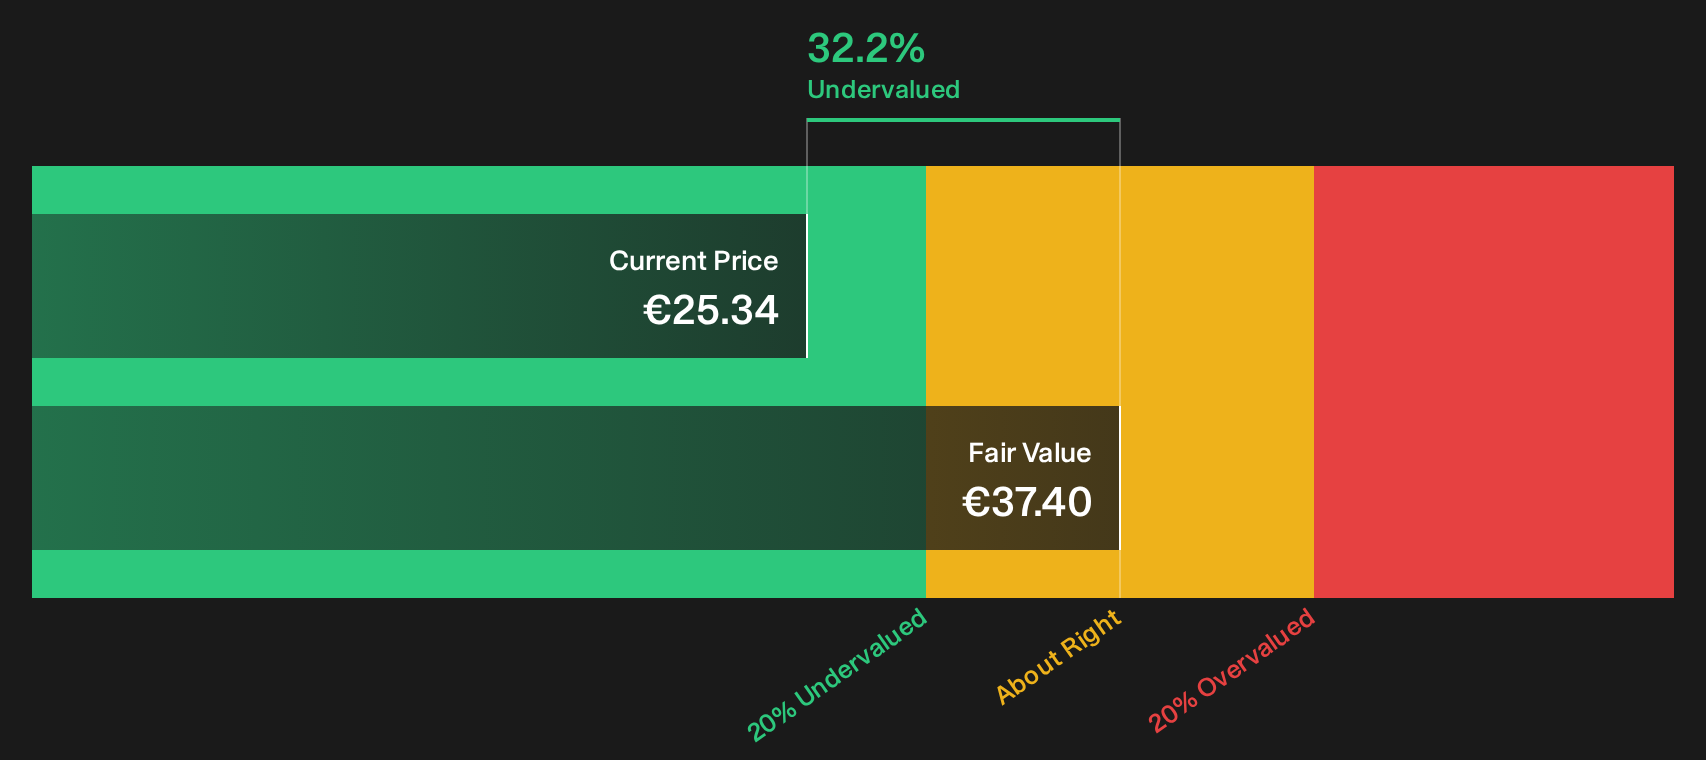
DCF suggests a different perspective. While the most followed narrative has Imerys marginally overvalued at €24.82 compared with the €25.34 share price, the SWS DCF model points to an estimated future cash flow value of €37.40, well above where the stock trades today. Which signal do you put more weight on?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages around Imerys valuation and project risk can feel messy. Move quickly, review the data yourself, weigh both sides, then judge the balance of 3 key rewards and 2 important warning signs
Looking for more Imerys-like investment ideas?
Do not stop with Imerys. Spread your research across a wider opportunity set so one project delay or single stock risk does not dominate your portfolio.
- Target potential mispricings by scanning a curated pool of financially strong candidates through the 204 high quality undervalued stocks.
- Strengthen portfolio resilience by prioritising businesses with cleaner finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (199 results).
- Add a pipeline of new possibilities by tracking a focused list of under-the-radar opportunities with the 614 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com