


How Investors Are Reacting To KONE Oyj (HLSE:KNEBV) Raised Sales Guidance
- KONE Oyj reported third quarter 2026 sales of €2,906 million and net income of €268.3 million, with earnings per share from continuing operations at €0.52, and modestly higher nine month results versus the prior year.
- Management also lifted 2026 sales guidance to 4% to 6% growth at comparable exchange rates, highlighting Service and Modernization demand and a solid order book as offsets to pressure in China's New Building Solutions market.
- We will now assess how KONE's raised 2026 sales guidance might reshape the existing investment narrative built around services and modernization.
Scan beyond KONE Oyj and compare its service led story with other businesses on our hand picked list of solid balance sheet and fundamentals (199 results) to see how quality and resilience line up.
KONE Oyj Investment Narrative Recap
To own KONE Oyj, you need to believe that services, modernization and digital maintenance can keep gaining weight in the mix while big new build markets like China stay under pressure. The raised 2026 sales guidance to 4% to 6% growth suggests management sees enough demand in upgrades and maintenance to support that thesis in the near term.
The key short term catalyst is execution in Service and Modernization, where higher recurring work can support earnings quality. The biggest risk still sits in China, with a declining New Building Solutions market and pricing pressure that could squeeze order margins if cost control and mix shift do not keep pace.
The most relevant announcement here is the upgraded 2026 sales outlook. Management now guides to 4% to 6% comparable sales growth, up from 3% to 6%, anchored by a solid order book and confidence in modernization and maintenance demand. That guidance frames how much protection those recurring oriented activities might offer against weaker new equipment demand.
For catalysts, this matters because stronger top line expectations give more room for KONE Oyj to work on order margins and connected services penetration, while also absorbing higher logistics and inflation linked costs. On the risk side, if China new build volumes or pricing soften faster than planned, the raised range could prove demanding and keep investor focus on execution discipline.
KONE Oyj's current analyst narrative points to revenues of €13.7 billion and earnings of €1.5 billion by 2029, based on a forecast revenue expansion of 6.3% a year and an earnings increase of about €556 million from €944.0 million today.
Uncover why KONE Oyj's fair value indicates an 8% potential upside to its current price that could narrow quickly.
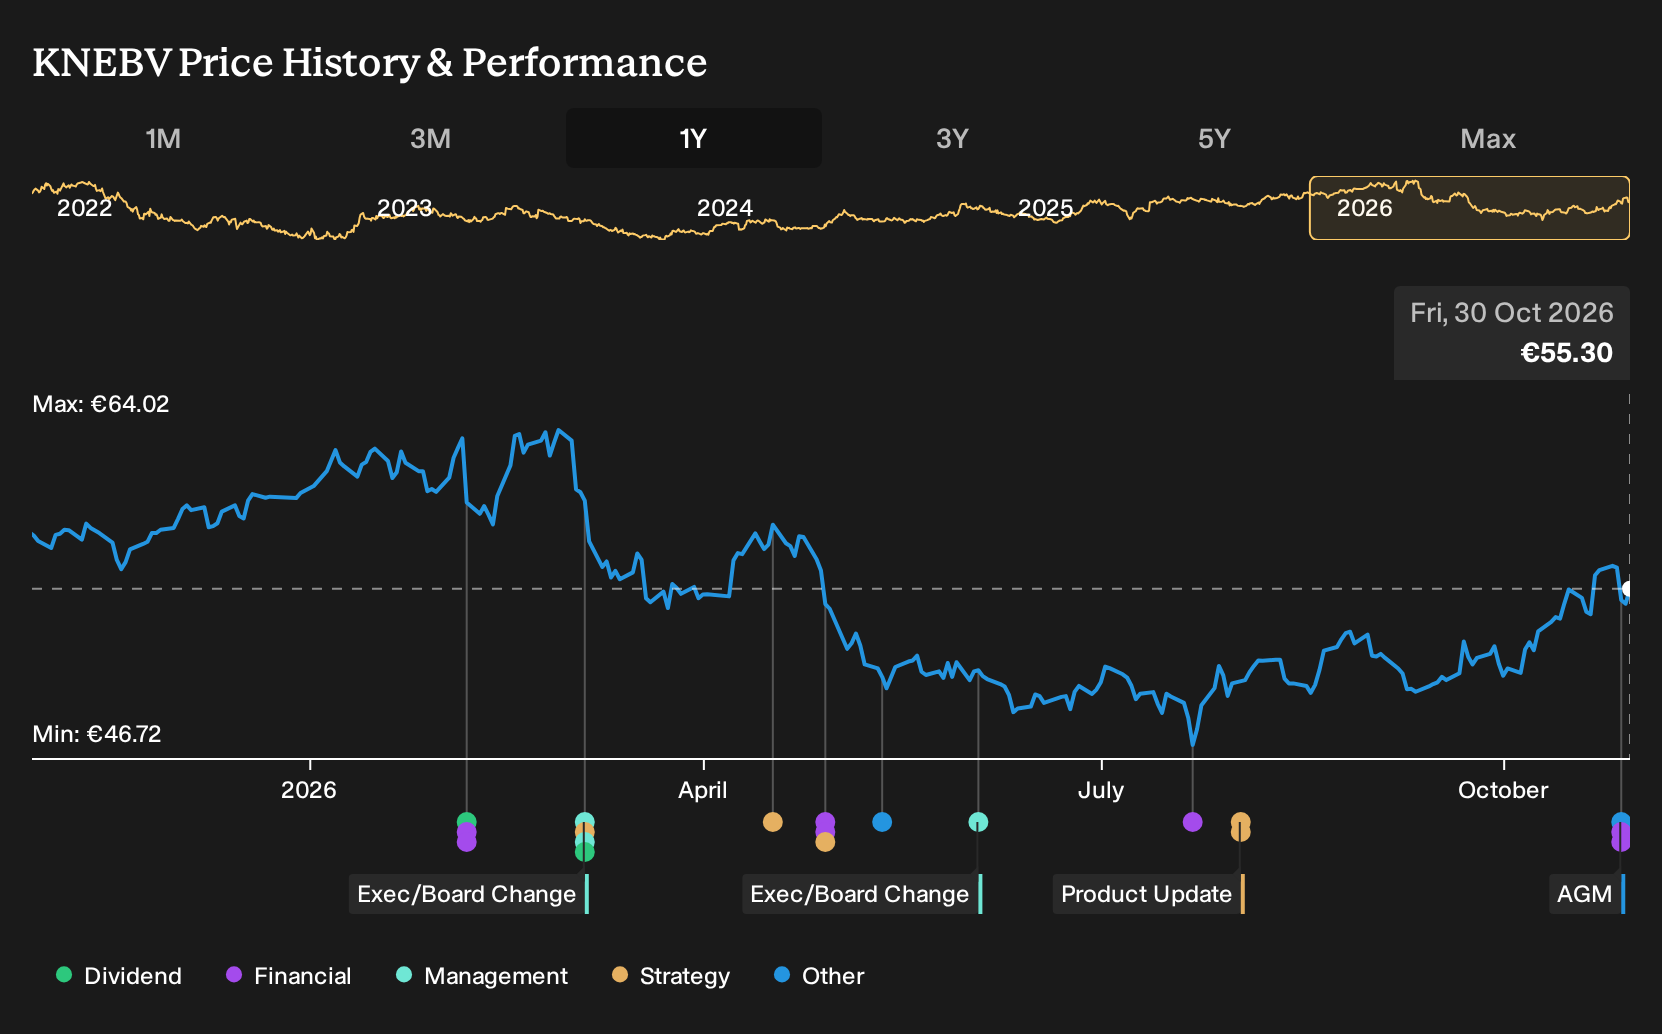
Exploring Other Perspectives
One alternate view on KONE Oyj leans heavily on TK Elevator execution risk. The most cautious analysts had pencilled in around €13.2b of 2029 revenue and €1.4b of earnings before this update. That is a tighter, more skeptical story. Use this guidance raise as a trigger to explore how far opinions can spread.
Explore 4 other KONE Oyj fair value estimates, including one that suggests up to 17% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your KONE Oyj research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for KONE Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KONE Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond KONE Oyj?
Once you have formed a view on KONE Oyj, it can help to benchmark that thesis against other businesses with different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential mispricings with quality fundamentals, scan through 204 high quality undervalued stocks that meet tight quality and valuation filters.
- If capital protection and balance sheet strength matter most to you, focus on our 218 resilient stocks with low risk scores that screen for resilient financial profiles.
- Income focused readers who care about cash returns can review 222 dividend fortresses built around higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com