


How Investors Are Reacting To Hulic (TSE:3003) Raised Guidance And Dividend
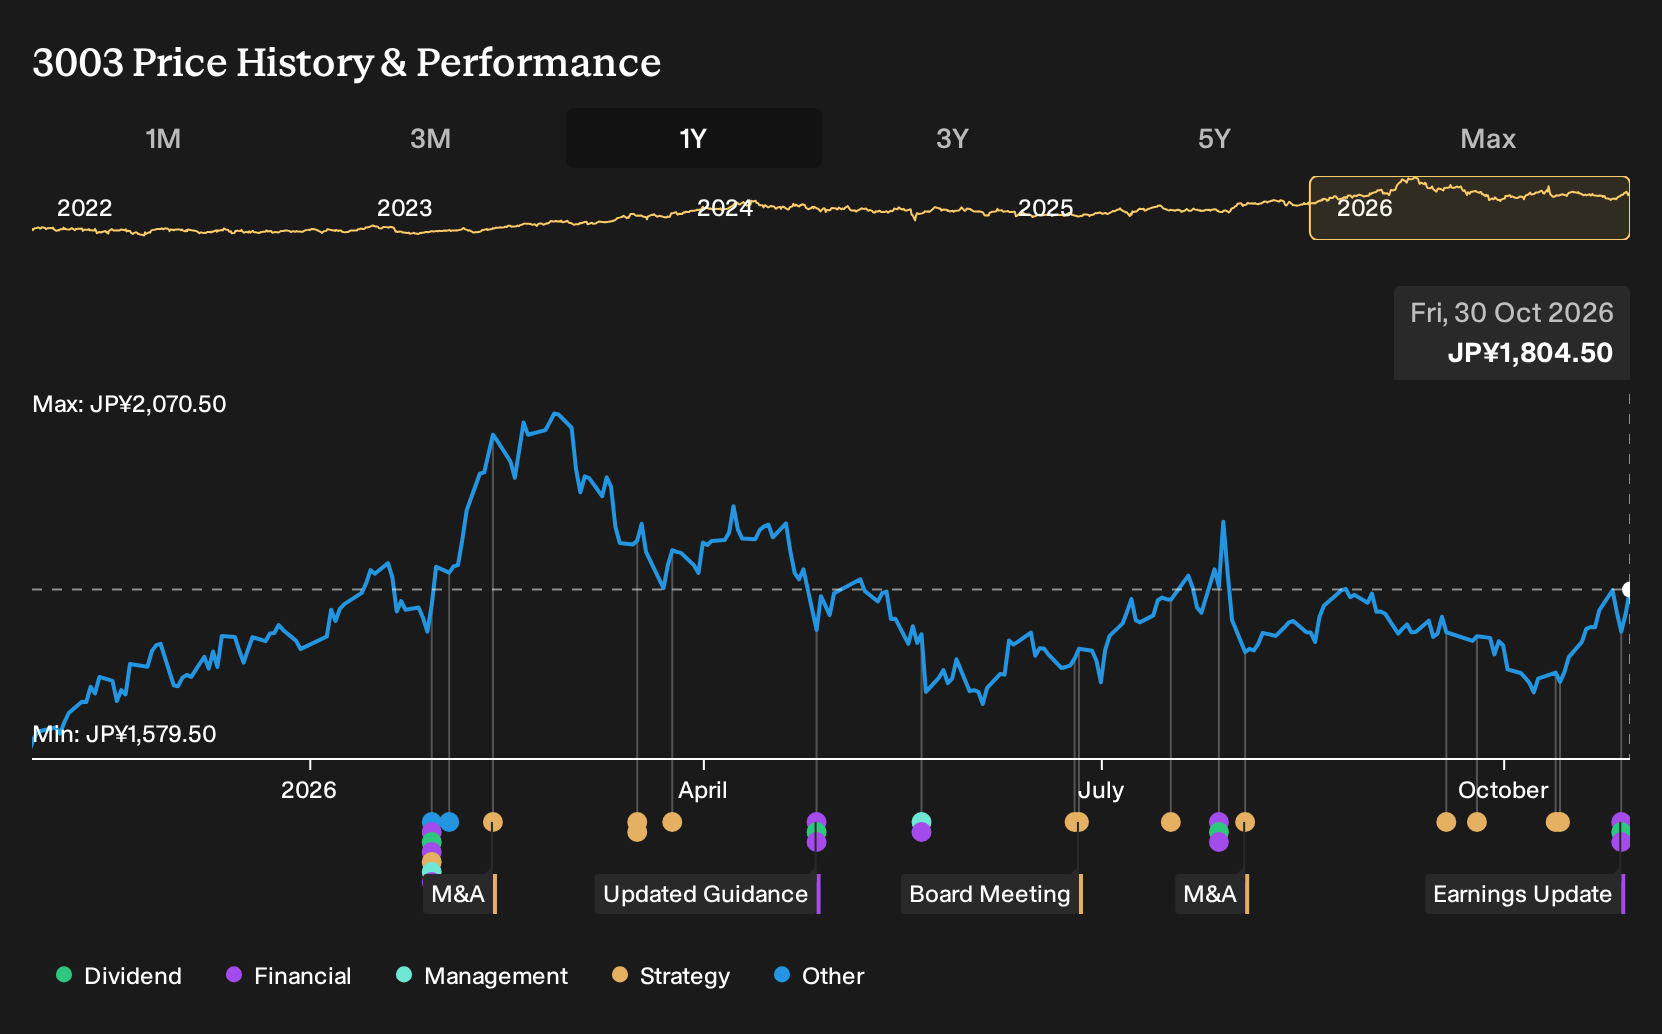
- Hulic raised its 2026 earnings guidance in October, projecting operating revenue of ¥900,000m and higher profit metrics after selling properties that did not fit its long term leasing portfolio plan, while also reporting nine month sales of ¥574,725m and net income of ¥69,470m.
- The group paired this profit upgrade with a richer shareholder payout, lifting its planned 2026 annual dividend to ¥70.00 per share as it targets a phased payout ratio increase toward 45% by 2029.
- The next consideration is what this upgraded Hulic outlook and higher dividend may signal for the broader investment narrative that investors now need to reassess.
What Is Hulic's Investment Narrative?
To own Hulic, you need to buy into a fairly straightforward story. This is a property centric group that tries to recycle capital out of non core assets and into a tighter, income driven leasing portfolio. The revised 2026 guidance and record profit outlook sit squarely in that playbook, backed by nine month sales of ¥574,725m and profit attributable to owners of parent of ¥69,470m. The higher dividend and planned payout ratio lift add a clearer income angle, which matters if you care about a mix of cash yield and real estate exposure in Japan.
In the short term, the main swing factors stay the same. Hulic still has a capital intensive model, relies on external borrowing and has debt that is described as not well covered by operating cash flow, while also running a dividend that screening flags as not well supported by free cash flow. The upgraded earnings guidance and richer payout do not remove those pressure points; they raise the bar for execution on asset sales and leasing performance, especially with revenue and earnings forecasts that sit below broader market growth rates.
Even so, the real tension in the Hulic story shows up once you look closely at how that bigger dividend interacts with ...
There's only one way to know the right time to buy, sell or hold Hulic. Head to Simply Wall St's company report for the latest analysis of Hulic's Fair Value.
Exploring Other Perspectives
Hulic attracts only 2 fair value views from the Simply Wall St Community, yet those estimates stretch from ¥161.69 to roughly ¥1,965.71 per share. That very wide gap shows how far opinions can spread when retail investors forecast future cash flows. These figures were set before the October 2026 guidance and dividend revision, so treat the higher earnings targets and payout plan as fresh information that could reshape expectations. Consider that disconnect as an opportunity to compare multiple viewpoints before deciding how Hulic fits your own return and risk priorities.
Explore another Hulic fair value estimate, including one that suggests up to 9% upside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hulic research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hulic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hulic's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hulic?
Once you have a view on Hulic, it can help to scan a broader set of opportunities so your portfolio does not hinge on a single story or sector. The Simply Wall St Screener lets you filter listed businesses by balance sheet strength, income focus, valuation and more, so you can line up Hulic beside other options that match your risk and return goals.
- If income stability is high on your list, check stocks that offer resilient payouts and consistent distributions through the 28 dividend fortresses.
- If capital preservation matters most, focus on companies that pair modest growth with lower risk profiles using the 23 resilient stocks with low risk scores.
- If you want potential upside before the crowd pays attention, scan quality smaller companies that screens flag as overlooked through the 69 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com