


Learn Why The Bull Case For Xenon Pharmaceuticals Stock Could Change Following Pain Trial Progress
- Xenon Pharmaceuticals reported past Phase 1 and preclinical results for pain candidates XEN1701 and XEN1120, supporting plans to move both ion channel modulators into Phase 2 proof of concept studies for acute pain in 2027.
- The data package suggested each asset reached exposure levels linked to analgesic effects in models while remaining generally well tolerated, which matters for Xenon Pharmaceuticals as it works to build a broader non opioid pain franchise focused on ion channel modulation.
- We will now look at how Xenon Pharmaceuticals' investment narrative could be influenced by XEN1701 achieving high NaV1.7 receptor occupancy.
Scan beyond Xenon Pharmaceuticals to see how other pain and ion channel specialists are positioned right now with a curated list of 34 healthcare AI stocks in this space.
Xenon Pharmaceuticals Investment Narrative Recap
Xenon Pharmaceuticals still hinges on a simple idea. You need to believe that ion channel drugs for epilepsy, mood disorders and pain can move from clinical promise to commercial reality before funding pressure bites. The XEN1701 and XEN1120 updates strengthen the pain-franchise story, but the key near term catalyst remains late stage azetukalner readouts, because the business currently reports no revenue.
The biggest operational risk is that Xenon Pharmaceuticals keeps absorbing heavy R&D spend while remaining unprofitable and reliant on external capital, especially after recent shareholder dilution. The acute pain programs help broaden the story, yet they are early, with Phase 2 studies planned for 2027, so they do not materially change near term risk.
The most relevant additional announcement is the equity inducement grants to nine new non officer employees. Fresh stock options and RSUs suggest Xenon Pharmaceuticals is adding talent as it gears up for more complex execution, including multiple late stage epilepsy trials and the planned Phase 2 pain studies.
For you as a shareholder, this kind of equity-based hiring matters for both catalysts and risk. Better staffed clinical and development teams can support timely trial starts and cleaner study operations. At the same time, the extra options and RSUs incrementally increase dilution on top of an already loss making profile and a P/B that screens above the wider US biotech industry.
Xenon Pharmaceuticals' narrative projects US$435.9 million in revenue and US$75.0 million in earnings by 2029. This implies a move from no revenue today and an earnings swing of about US$484.2 million, from the current loss of US$409.2 million to the forecast profit.
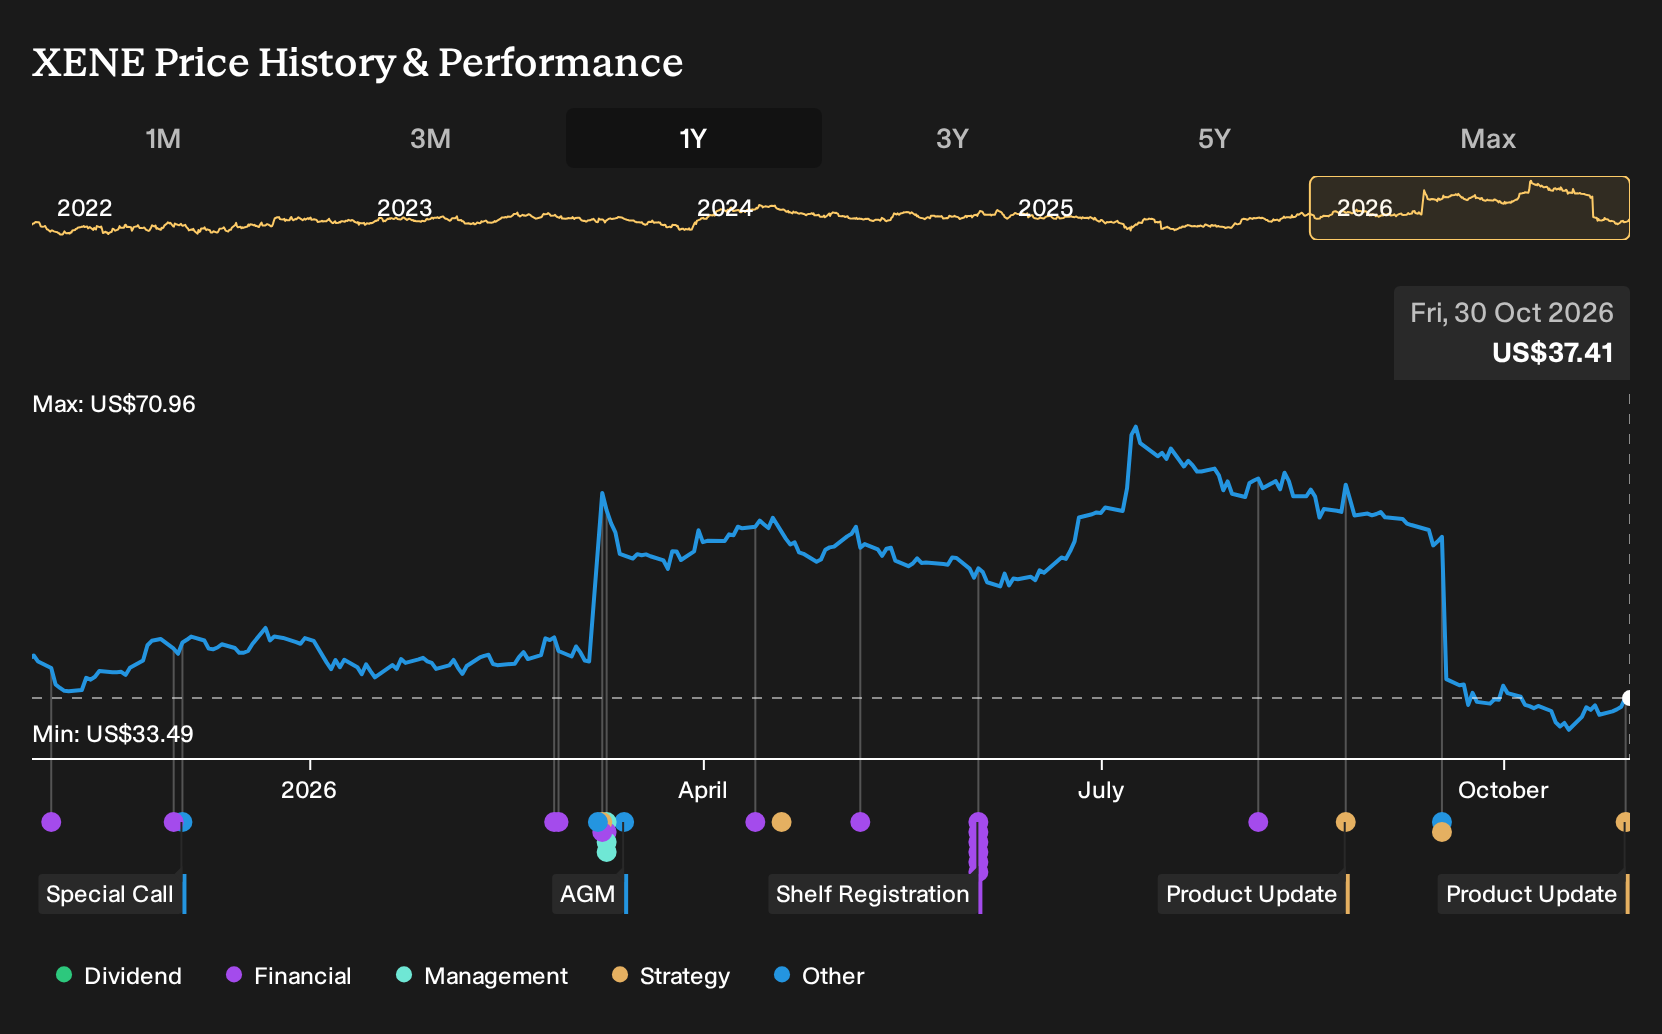
Uncover why Xenon Pharmaceuticals' fair value indicates a 94% potential upside to its current price before the market removes the discount.
Exploring Other Perspectives
One alternate view leans hard into the ion channel pain story at Xenon Pharmaceuticals. That bullish camp was already pencilling in US$955.9 million of 2029 revenue and US$164.4 million of earnings, far above consensus. Those forecasts came before this NaV1.7 update, so analyst opinions may shift and diverge further from here.
Explore 2 other Xenon Pharmaceuticals fair value estimates, including one that suggests as much as 1042% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Xenon Pharmaceuticals research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Xenon Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Xenon Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Xenon Pharmaceuticals?
If the Xenon Pharmaceuticals story has you thinking about position sizing, risk and return, it can help to set it alongside a few very different profiles from the Simply Wall St Screener.
- For investors who want potential upside but do not want to completely sacrifice balance sheet strength, start with a curated 29 resilient stocks with low risk scores that may better match a cautious style.
- If income matters as much as price moves, scan through a focused set of 5 dividend fortresses that aim to pair higher yields with business resilience.
- When you want to widen the search beyond well known tickers, cast a wider net across 19 high quality undiscovered gems that combine stronger fundamentals with less crowded ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com