


Charge Offs Rise Might Change The Case For Investing In First Interstate BancSystem Stock (FIBK)
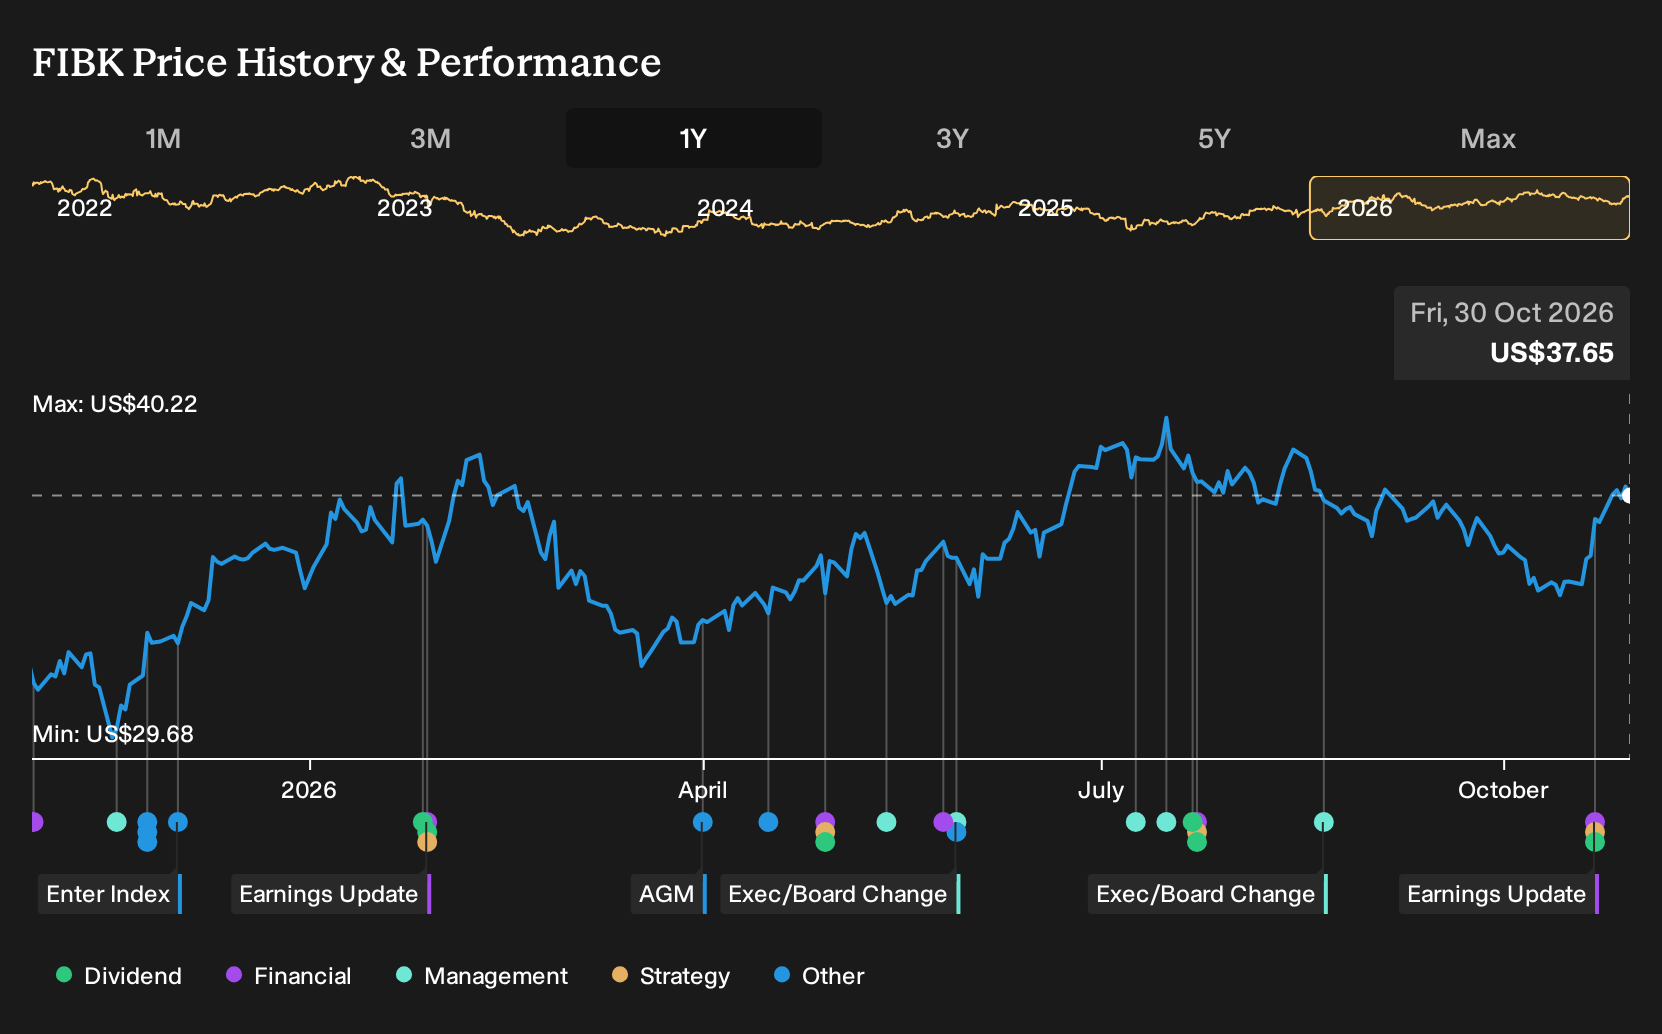
- First Interstate BancSystem reported third quarter 2026 net income of US$62.2 million, with basic EPS from continuing operations of US$0.66 and diluted EPS of US$0.65, alongside net loan charge offs of US$9.9 million.
- The board kept the quarterly dividend at US$0.47 per share, which equated to a 5.0% annualized yield based on the third quarter 2026 average share price and highlighted management’s willingness to return capital even as charge offs and earnings data point to operating pressure.
- The focus now turns to how First Interstate BancSystem's higher third quarter loan charge offs may reshape the existing investment narrative.
Scan how First Interstate BancSystem’s higher charge offs and steady payout compare with peers by lining up banks with resilient balance sheets using the list of solid balance sheet and fundamentals (24 results).
First Interstate BancSystem Investment Narrative Recap
To own First Interstate BancSystem, you need to be comfortable with a slow growth, clean up story where earnings power comes less from rapid loan expansion and more from repricing, cost control and credit discipline. The latest quarter fits that picture. Net income of US$62.2 million and softer EPS underline a business still working through an efficiency and balance sheet transition.
The short term swing factor remains whether management can stabilize loan volumes and keep credit costs contained as criticized and non relationship loans run off. Higher net charge offs of US$9.9 million highlight that risk. If problem credits stay manageable and repricing benefits hold, the recent figures may not materially alter the broader thesis.
The dividend affirmation at US$0.47 per share is the clearest signal out of this earnings batch for you as a shareholder. It indicates that First Interstate BancSystem is continuing to prioritize a regular cash return even as profit is lower than a year ago and credit costs are heavier in this quarter.
That payout, which equated to a 5.0% annualized yield based on the third quarter average share price, now sits alongside guidance that loans could keep shrinking and that earnings are forecast by analysts to decline over the next three years. Your decision is whether the combination of dividend income, balance sheet clean up and repricing catalysts offsets the risk of softer long term profit trends.
First Interstate BancSystem is modeled to reach about US$1.0b in revenue and US$325.7 million in earnings by 2029. Analysts assume fairly flat top line performance over the next few years, which implies minimal yearly revenue growth and an earnings increase of about US$1.4 million from current earnings of roughly US$324.3 million.
Uncover why First Interstate BancSystem's fair value is essentially in line with its current price.
Exploring Other Perspectives
You also have a very different story on First Interstate BancSystem from the lowest analysts, who focus on balance sheet shrinkage risk. They were penciling in 2029 earnings of about US$275.9 million on roughly US$1.0 billion of revenue before this quarter, well below consensus, so your own view might shift as you compare these pre-news forecasts with the fresh charge-offs and the dividend decision.
Explore 6 other First Interstate BancSystem fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Interstate BancSystem research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for First Interstate BancSystem. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Interstate BancSystem's overall financial health at a glance.
Looking for more investment ideas beyond First Interstate BancSystem?
Once you have a clear view on First Interstate BancSystem, it can help to compare it with a wider set of listed businesses that share similar qualities or offer different risk and income profiles.
- If you want potential value with quality fundamentals, use the 33 high quality undervalued stocks to line up candidates that pair balance sheet strength with attractive pricing signals.
- If income is your priority, scan the market for companies that offer robust cash distributions through the 5 dividend fortresses and see how that yield stacks up against First Interstate BancSystem.
- If capital protection matters most to you, narrow your search to businesses with steadier profiles using the 29 resilient stocks with low risk scores and compare how their risk scores fit your comfort level.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com