


How Strong Earnings And Buybacks Will Impact Universal Insurance Holdings (UVE) Investors
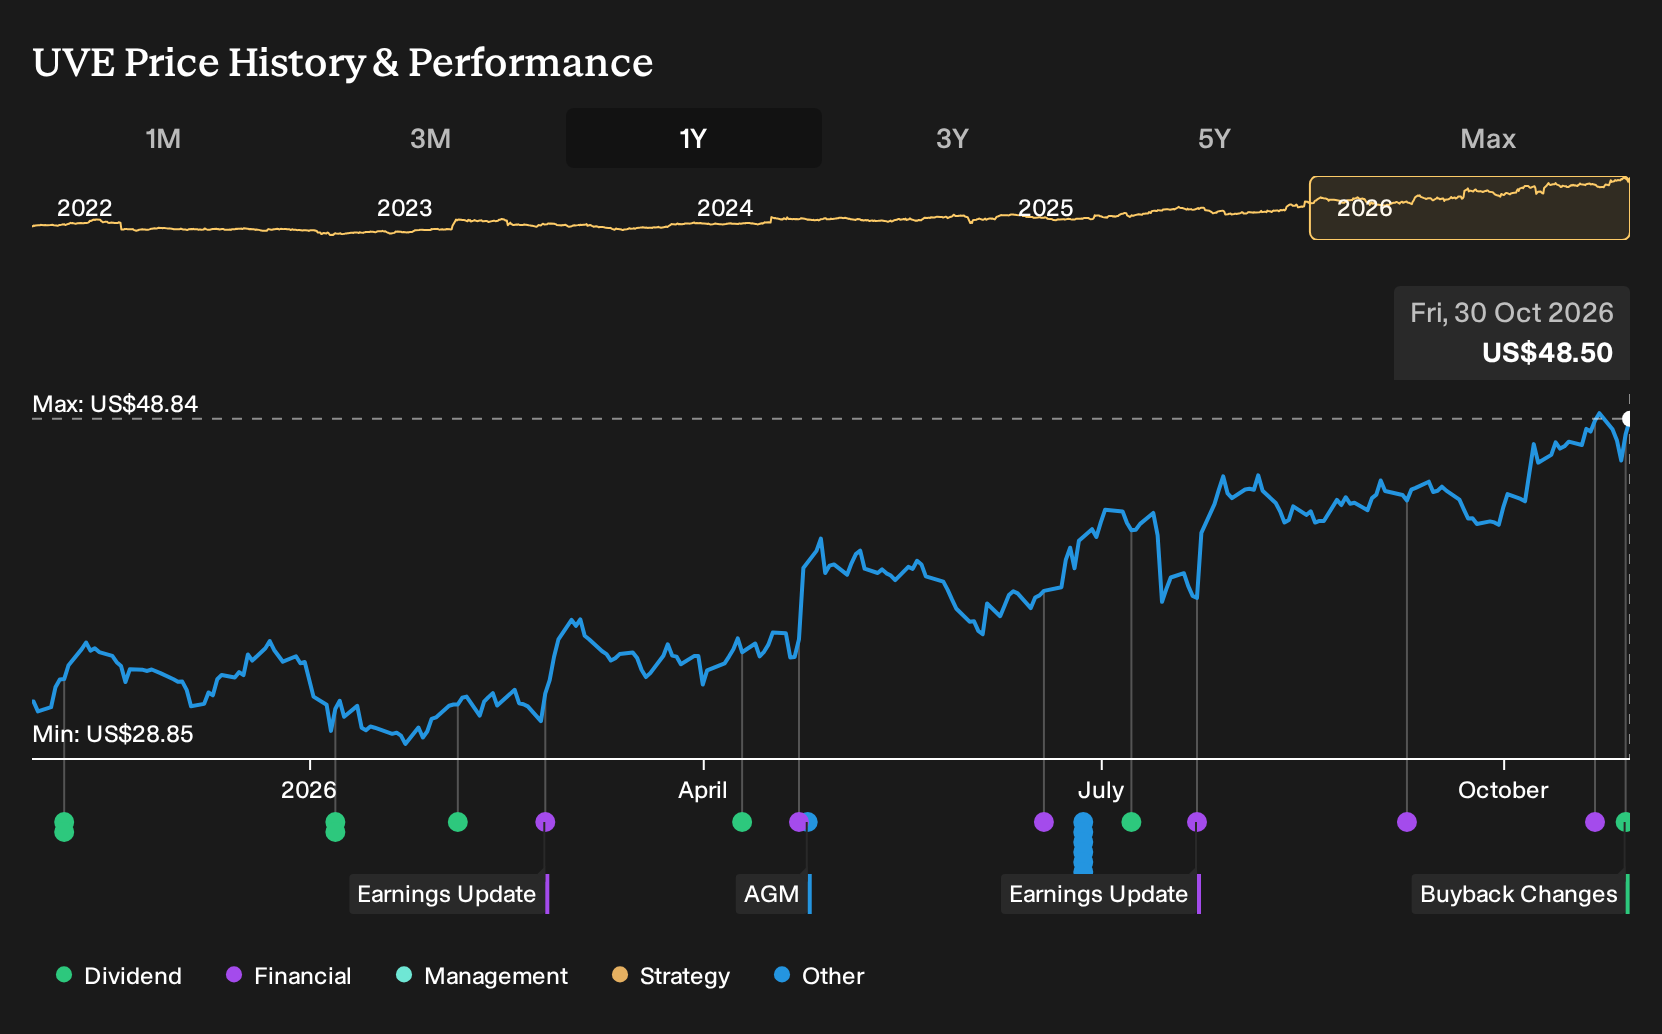
- Universal Insurance Holdings reported third quarter 2026 revenue of US$439.32 million and net income of US$52.51 million, alongside a completed repurchase of 499,170 shares for US$18.84 million under its January 2026 buyback plan.
- The board raised the equity repurchase authorization to US$40 million, which tightens the share count while the insurer is generating higher basic and diluted earnings per share across both the quarter and year to date.
- This article examines how Universal Insurance Holdings' recent earnings and expanded buyback program may influence the way investors view the company.
Compare Universal Insurance Holdings' capital return story with other insurers that are tightening share counts and supporting earnings power through buybacks by scanning our curated list of list of solid balance sheet and fundamentals (24 results)
Universal Insurance Holdings Investment Narrative Recap
For Universal Insurance Holdings, the core belief you would need is that the underwriting engine and reinsurance program stay disciplined enough to support current profitability while growth outside Florida gradually balances the concentration risk in that state. The latest quarterly results, with higher revenue and net income versus a year earlier, support that story in the near term but do not remove exposure to weather, regulation, or reinsurance costs.
The near term catalyst sits in how effectively Universal Insurance Holdings manages loss ratios and reinsurance renewals while competition in Florida increases. Elevated ceded premium costs, inflation in claims and reconstruction expenses, and any further softening in Florida premiums written remain the key risks that could pressure margins if conditions worsen from here.
The expanded US$40 million repurchase authorization is the announcement that ties closest to this update. Universal Insurance Holdings has already completed US$18.84 million of buybacks this year, retiring 1.79% of its shares. That shrinking share count sits on top of basic EPS of US$1.90 and diluted EPS of US$1.80 in the latest quarter from continuing operations.
For you as an investor, the operational question is whether earnings power can keep up with the capital return pace while headwinds like Florida competition, catastrophe exposure, and reinsurance dependence remain live. If underwriting discipline and geographic diversification hold, buybacks and current profitability could keep EPS supported, but any sustained hit to loss ratios or reinsurance costs would quickly test that thesis.
Universal Insurance Holdings' current earnings are US$232.6 million, with analysts forecasting US$147.3 million of earnings on US$1.6b of revenue by 2029. This implies a 1.6% yearly revenue decline and an earnings decrease of US$85.3 million from today.
Uncover why Universal Insurance Holdings' fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$51 and about US$60.87 per share, showing a tight but still varied view of Universal Insurance Holdings. When this is set against rising competition in Florida and reliance on affordable reinsurance, it leads to a broader discussion about how durable current earnings really are.
Explore another Universal Insurance Holdings fair value estimate, including one that suggests as much as 26% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Universal Insurance Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Universal Insurance Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate Universal Insurance Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Universal Insurance Holdings?
Once you have formed a view on Universal Insurance Holdings, it can help to compare that thesis with other businesses that match the type of balance sheet strength, income profile, or valuation you are aiming for in your portfolio.
- If capital preservation and steady operations matter most to you, start with a 29 resilient stocks with low risk scores that may better align with your comfort level.
- For investors who want potential value upside with fundamental support, scan a 19 high quality undiscovered gems that might not yet be widely followed.
- If you prize consistency in dividends and want ideas that skew toward income, narrow your search using a 5 dividend fortresses that matches your yield targets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com