


Apollo Global Management (APO) Could Be 28% Below Fair Value As UDR Deal Lands
How the UDR apartment venture frames Apollo’s latest move
Apollo Global Management (APO) is committing US$1.34b of equity to a new joint venture with UDR, backing a US$2.0b portfolio of 19 apartment communities with 7,059 homes.
The structure gives Apollo roughly a two thirds stake, while UDR keeps a one third interest and continues to operate the properties in return for an asset management fee.
Against that backdrop, Apollo Global Management’s stock has been under pressure, with the share price down 20.99% year to date and declining 10.49% over the past 90 days. However, the 3 year total shareholder return of 42.68% and 5 year total shareholder return of 65.86% still present a much stronger longer term picture of wealth creation.
The recent 2.67% 7 day share price return and 1.60% 30 day share price return suggest some short term momentum is rebuilding around announcements such as the UDR venture and the upcoming board refresh. At the same time, the 1 year total shareholder return of 5.27% in decline indicates that investors are still reassessing risk and earnings durability at around US$115.84 per share.
Spot 33 high quality undervalued stocks that, like Apollo Global Management, are deploying capital into real assets and could be setting up their own next phase of momentum.Bulls see Apollo Global Management using the UDR deal to lock in steady real estate income, while the share price reset creates room for upside. Bears focus on revenue volatility and recent share price weakness. Which side does the valuation evidence lean toward next?
Price-to-Earnings of 36.2x: Is it justified?
On simple earnings math, Apollo Global Management changes hands at a P/E of 36.2x, which sits below its peer group on one measure yet screens expensive against its broader industry and an estimated fair level for the business.
The P/E ratio compares the current share price to earnings per share and gives a shorthand for how much investors are paying for each dollar of profit. For a diversified financial group like Apollo Global Management, that multiple often reflects how durable investors think fee income and investment profits will be through the cycle.
Relative to a selected peer set where the average P/E runs at 49.5x, the stock looks cheap on this single comparison and suggests the market is assigning a lower earnings premium. Against the wider US Diversified Financial industry average of 16.2x, the same 36.2x looks materially richer and signals that investors are currently willing to pay more than double the sector level for Apollo Global Management's earnings. The estimated fair P/E of 21.7x also sits well below the current ratio, which implies a level the market could move toward if sentiment or growth expectations cool.
Explore the SWS fair ratio for Apollo Global Management.
Result: Price-to-Earnings of 36.2x (OVERVALUED)
Still, abrupt swings in Apollo Global Management’s revenue, which recently declined 71.09% year on year, or setbacks in real asset deals could quickly challenge the upbeat thesis.
Find out about the key risks to this Apollo Global Management narrative.
Another view on Apollo Global Management’s value
The first check using the P/E ratio presents Apollo Global Management as expensive relative to its sector, yet generous compared with a tight peer group. A second lens tells a different story. Our DCF model suggests the shares are trading below an estimated future cash flow value of $161.83, with the current price at $115.84.
This gap points to a stock that screens rich on earnings multiples but looks inexpensive on projected cash generation. Which signal should carry more weight for you: a higher than average P/E today, or a discount to future cash flows implied by our model?
Look into how the SWS DCF model arrives at its fair value.
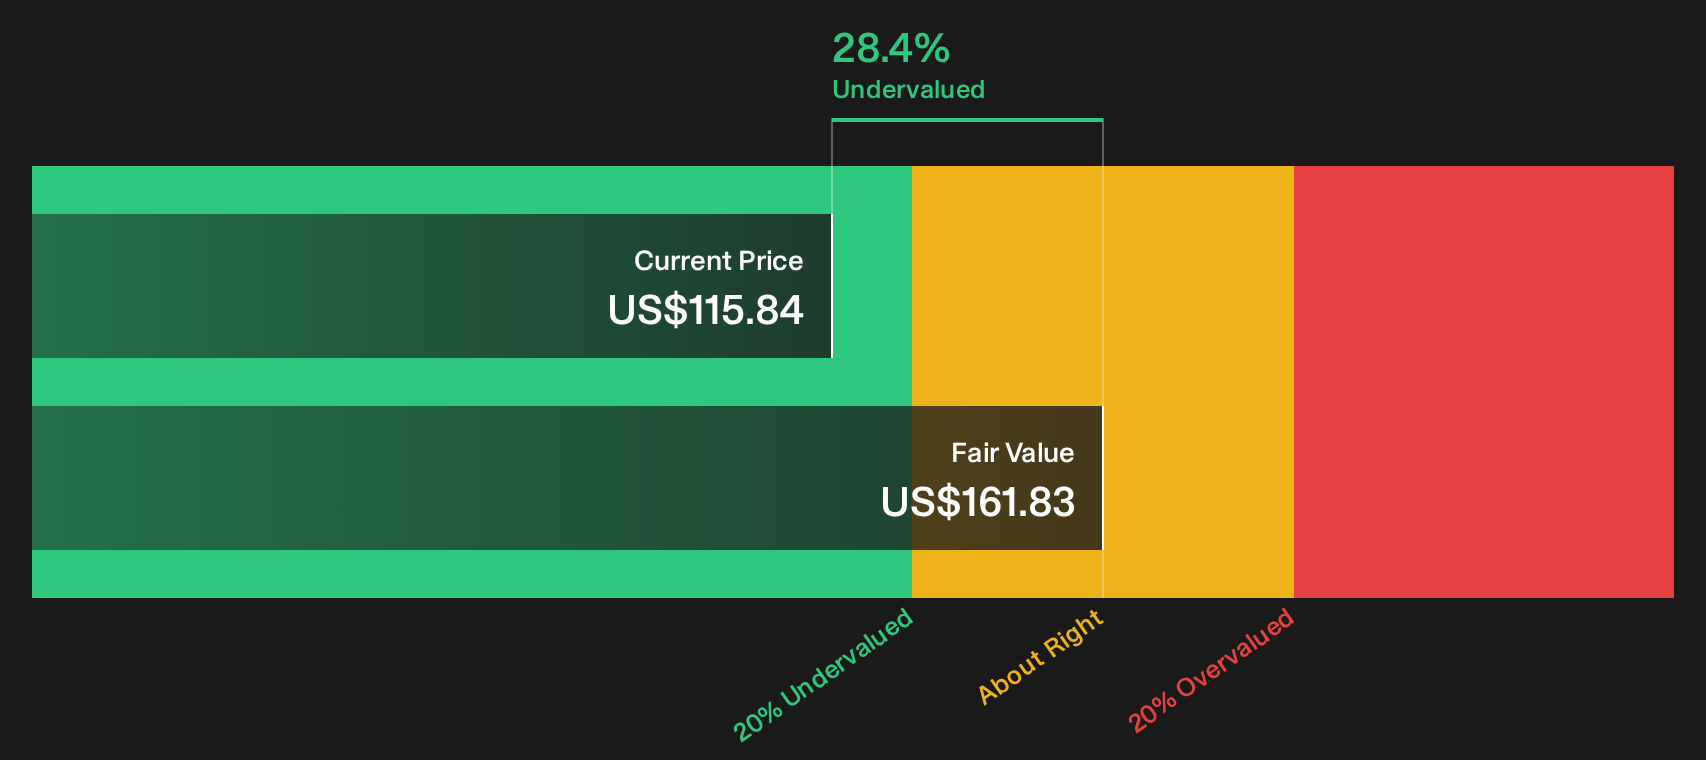
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Apollo Global Management for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted on Apollo Global Management after considering both the UDR deal and the valuation signals. Act while the data is fresh and compare the figures with your own expectations with 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Apollo Global Management?
Do not stop at Apollo Global Management. Use fresh data and focused filters to look for stocks that better match your goals before the market moves on without you.
- Target potential value opportunities early by scanning the market for 33 high quality undervalued stocks that may offer stronger fundamentals than the headline stories everyone is already watching.
- Strengthen your income playbook by lining up 5 dividend fortresses that could complement or balance what Apollo Global Management brings to your portfolio.
- Protect the downside first and build around resilience using a 29 resilient stocks with low risk scores so you are not caught off guard if conditions change quickly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com