


Republic Services (RSG) Could Be 18% Undervalued Following Strong Q3 Results And Buyback
Why Republic Services Stock Is Back On Investor Radars
Republic Services (RSG) has put fresh numbers on the table. Third quarter 2026 results, a larger buyback plan through 2029, and a reaffirmed dividend are giving investors new information to weigh.
Recent trading shows that momentum in Republic Services has picked up, with a 30-day share price return of 16.45% and a 90-day move of 16.42%. The 1-year total shareholder return of 18.60% and 5-year total shareholder return of 95.66% indicate a strong longer-term reward profile.
Scan beyond Republic Services and identify other waste and infrastructure plays showing similar momentum with our curated 29 resilient stocks with low risk scores, tuned for steadier balance sheets and lower risk scores.
Republic Services now trades close to analyst targets while still screening at a discount to some intrinsic estimates. After a double digit run, where does fair value actually sit within that range?
Price-to-Earnings of 33.4x: Is It Justified For Republic Services?
Republic Services now carries a premium P/E of 33.4x against a last close of $244.04, so the key question is whether that higher earnings multiple is earning its keep.
The P/E ratio compares the current share price to earnings per share. For a waste and environmental services operator with steady demand patterns, investors often focus on this measure to judge what they are paying for each dollar of profit. A richer multiple usually reflects expectations around durability of earnings, pricing power, or balance sheet resilience.
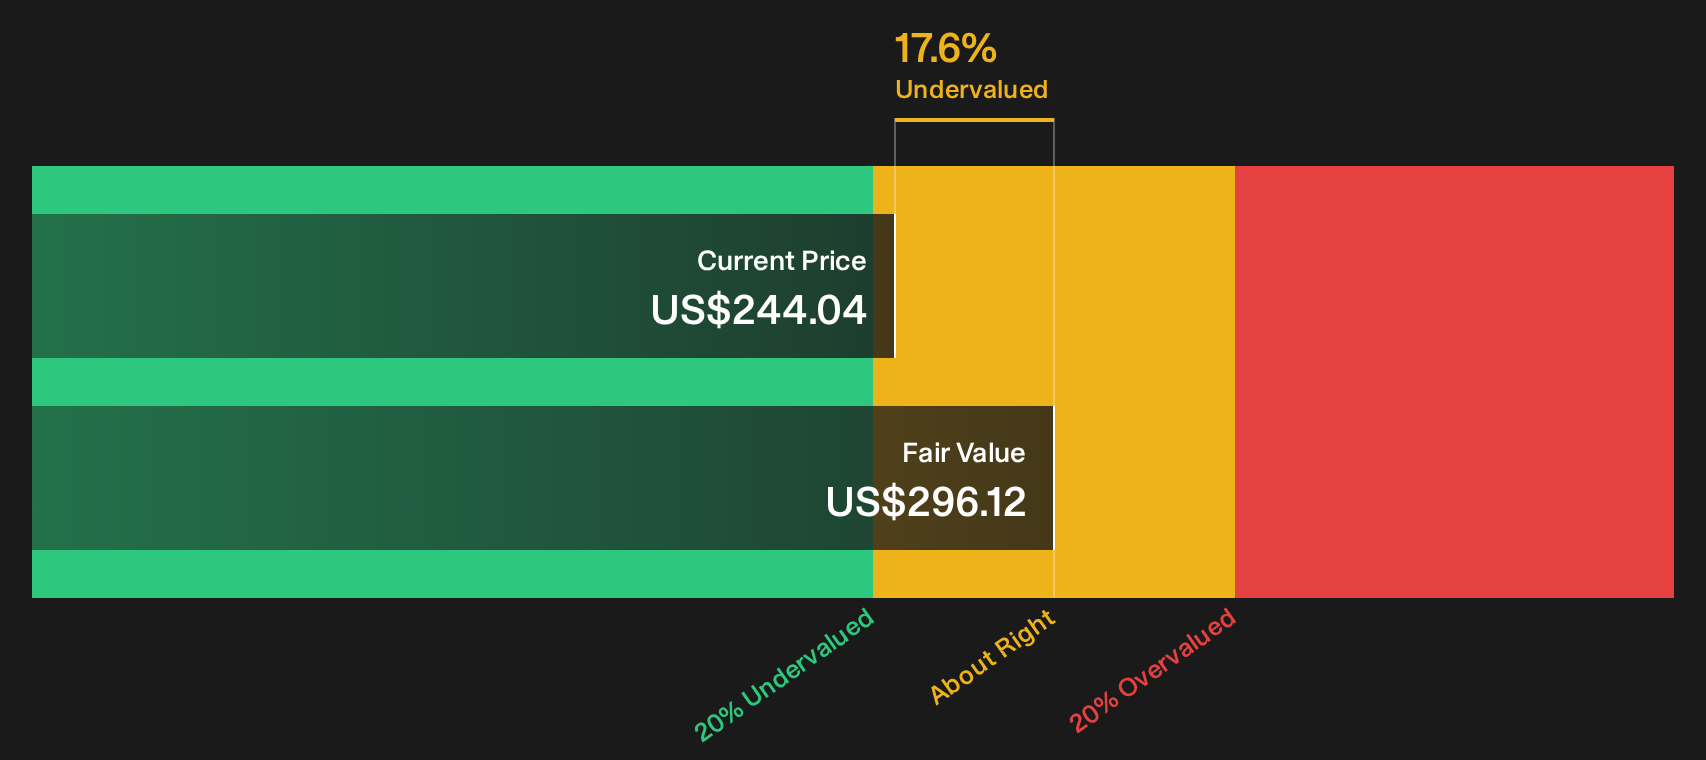
On the earnings side, Republic Services has an earnings growth forecast of 7.37% per year, with revenue expected to rise 4.8% per year. Earnings have grown 12.1% per year over the past 5 years, and the business is flagged as having high quality earnings. Net profit margins are described at 12.9% versus 12.8% last year, and return on equity sits at 18.2% today with projections pointing to 21.5% in three years. That mix of steady profitability and a seasoned management team can help explain why the SWS DCF model also flags the shares as trading 17.6% below an intrinsic value estimate of $296.12, even while the P/E looks stretched. The P/E of 33.4x is still expensive compared to the estimated fair P/E of 24.2x, which is a level the market could move toward if sentiment cools.
Against peers, the premium is clear. The 33.4x P/E is described as expensive versus the US Commercial Services industry average of 18.8x and also richer than the 32x peer group average. That means investors are paying a higher price for Republic Services earnings than for much of the sector, even though earnings growth over the past year of 5.7% did not exceed the wider Commercial Services industry figure of 15.7%.
Explore the SWS fair ratio for Republic Services.
Result: Price-to-Earnings of 33.4x (OVERVALUED)
Still, Republic Services could feel pressure if regulatory costs rise faster than pricing or if investor appetite cools for paying a 33.4x P/E premium.
Find out about the key risks to this Republic Services narrative.
Another View On Republic Services Valuation
The premium P/E story points one way, yet the SWS DCF model tells a different one. On that cash flow view, Republic Services at $244.04 screens about 17.6% below an estimated fair value of $296.12, which frames today’s premium multiple as a possible margin of safety instead of pure froth. Which lens do you trust more when pricing future cash flows?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Republic Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mix of premium valuation and discounted cash flow signals around Republic Services, or already leaning one way? Act while the data is fresh and pressure test your view against the 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Republic Services?
If Republic Services sharpened your focus on quality, do not stop here. Broader ideas today could be the difference between a solid portfolio and a standout one.
- Target potential mispricings by scanning a curated set of companies that combine strong fundamentals with attractive entry points through the 33 high quality undervalued stocks.
- Build a steadier income stream by reviewing businesses with higher yields and resilient cash coverage using the 5 dividend fortresses.
- Prioritise financial strength by filtering for companies with robust balance sheets and healthier fundamentals through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com