


Is Revolve Group (RVLV) Stock Too Expensive After Its Florida Store Push?
Revolve Group has seen its share price swing sharply over the past few years, and the stock now trades around US$22.43 as the business leans further into physical retail and menswear. With that backdrop, the key issue for investors is whether this price lines up with what the company is currently earning.
- Over the past 5 years the share price has fallen 72.5%, which puts the focus squarely on whether today's valuation is still anchored to Revolve Group's profit power.
- The new Aventura Mall store and the appointment of Dwyane Wade as Chief Performance Officer for menswear can shape expectations for future earnings by influencing brand reach, the mix of high margin categories, and the cost of expanding the retail footprint.
- Your read on Revolve Group is one view; the desks covering it have another. See what analysts think Revolve Group's shares could be worth.
The stock's next move may depend on whether its current earnings support the valuation that the market is placing on Revolve Group today.
If you want to stress test the same earnings question you are asking of Revolve Group across a broader set of ideas, take a look at 33 high quality undervalued stocks
Is Revolve Group Getting Expensive on Earnings?
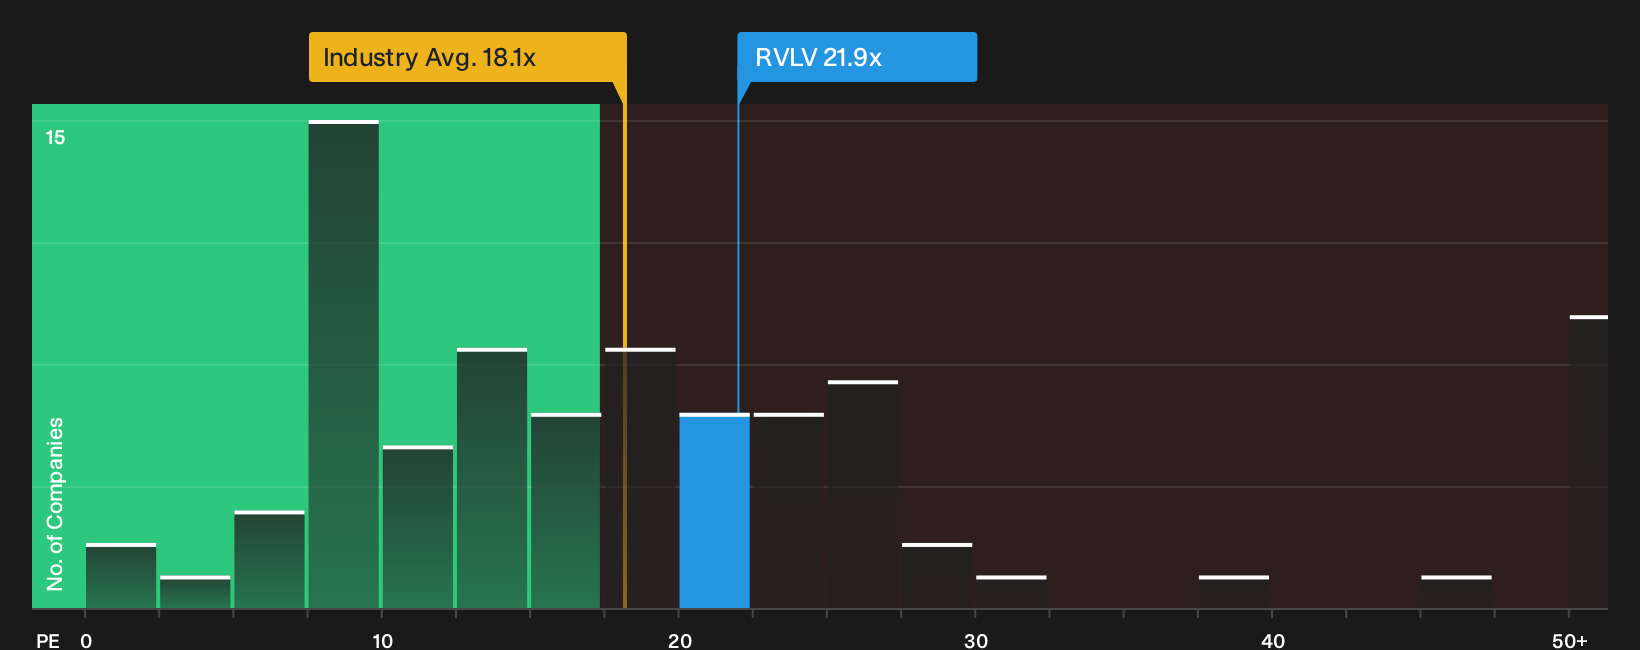
The P/E ratio fits Revolve Group because investors usually anchor fashion retail valuations to current earnings. Revolve Group trades on a P/E of 22.0x, compared with about 18.1x for the wider Specialty Retail industry and a peer average of 29.3x, so the stock sits between sector and direct-comparison reference points rather than hugging either extreme.
Despite the buzz around the new Aventura Mall store and Dwyane Wade's menswear role, the market is still pricing Revolve Group above the earnings multiple suggested by a tailored fair-value framework that weighs its margins, growth outlook, size and risk profile. That gap points to expectations that the business will justify a richer earnings tag than the model implies, and it leaves holders weighing whether the current P/E fully reflects those expansion efforts or already runs ahead of them. Explore the numbers behind Revolve Group's P/E valuation.
The Revolve Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E discussion for Revolve Group leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the shares to be worth materially more or less than they trade for today. Each one sets out Revolve Group's implied fair value as a thesis that can be revisited over time, so you can see how the reasoning behind it holds up, and they sit on Simply Wall St's Community page.
One of the top community narratives on Revolve Group: 27% undervalued
"Expanding Revolve Group’s international footprint, with international net sales growth of 16% year over year in Q2 2026 and a mix that reached 23% of total net sales, leaves substantial room for further revenue growth..."
Discover why this Narrative puts Revolve Group at 27% undervalued.
One more lens for Revolve Group before you stop at the P/E
Price comparisons only tell you what the market thinks today, while analysts have laid out where they expect Revolve Group’s earnings profile to land a few years from now. Explore where analysts expect Revolve Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com