


Cathay General Bancorp (CATY) Stock Looks About Right After Record Earnings
Cathay General Bancorp has delivered a strong multi year share price run, so the question now is whether the current valuation is still grounded in its earnings power. With the stock recently closing at US$64.40, investors are asking how much of the good news is already reflected in the P/E and related earnings multiples.
- The share price has returned 89.4% over the past 3 years, which puts real weight on whether the bank's earnings profile can carry that kind of re rating.
- Recent results highlighted record net interest income and wider net interest margins, which can support a higher level of sustainable earnings if credit costs and deposit competition remain under control.
- The analysts covering Cathay General Bancorp have run their own numbers. See what analysts think Cathay General Bancorp's shares could be worth.
The issue now is whether Cathay General Bancorp's current share price is justified by what its earnings already show and what they reasonably point to over time.
If you want to pressure test Cathay General Bancorp's earnings based valuation against a broader set of ideas, compare it with 33 high quality undervalued stocks.
Does Cathay General Bancorp Look Fairly Valued on Earnings?
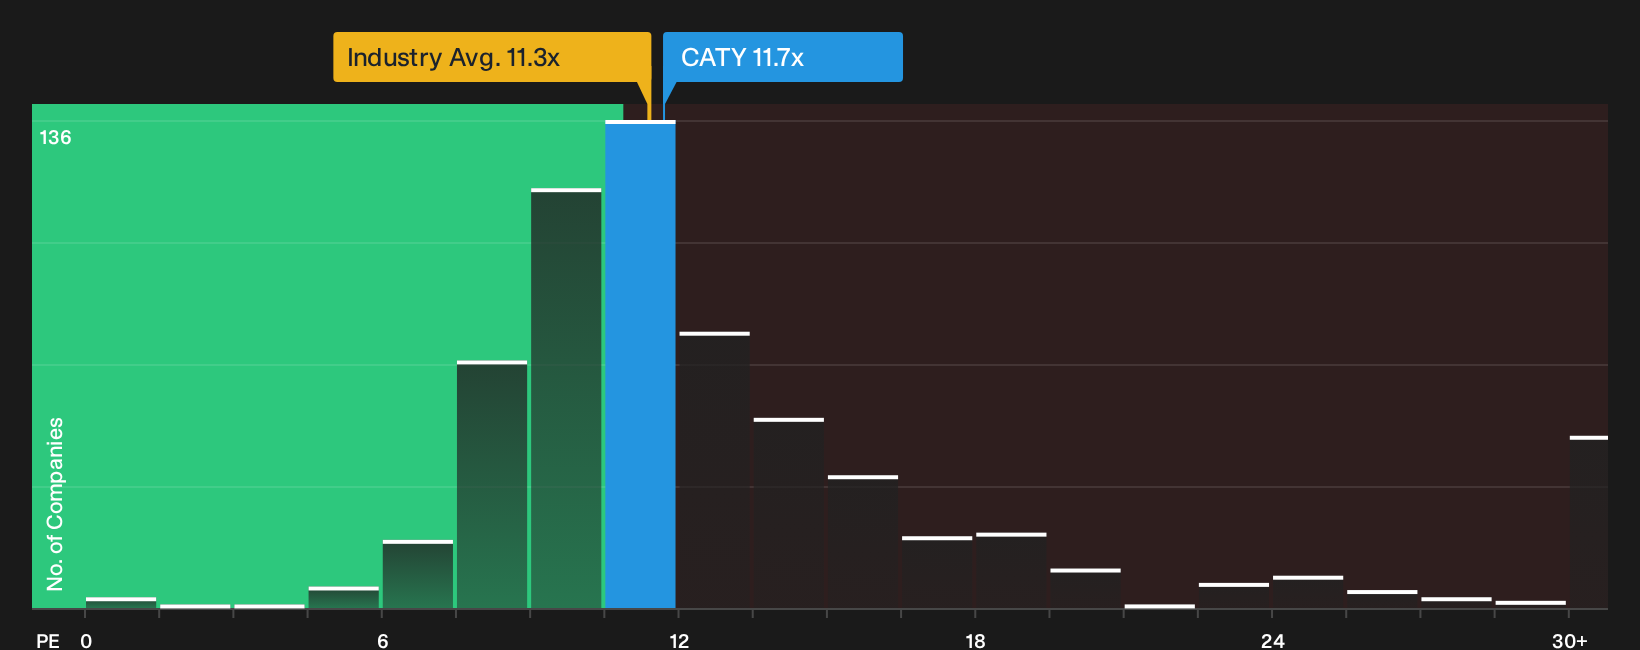
The P/E ratio works reasonably well for Cathay General Bancorp because earnings remain a primary driver of value for a traditional lender. On this measure, the stock trades at about 11.7x earnings, only slightly below the peer average of roughly 12.5x and close to the wider banks sector on about 11.3x. That cluster of numbers suggests investors are paying a broadly similar earnings multiple to what they pay for comparable institutions, rather than a clear premium or clear discount.
The tailored fair P/E multiple for Cathay General Bancorp sits very near the current ratio, so the market price is not leaning heavily toward either a stretch valuation or a clear bargain on this framework. Because the latest quarterly report showed record net interest income and firmer net interest margins, the fact that the P/E is only around sector and peer levels implies those earnings are not being given an obviously rich or cheap tag at today’s share price. To see how this picture looks next to cash flow and intrinsic value estimates, run Cathay General Bancorp through the fuller valuation tools. Explore the numbers behind Cathay General Bancorp's P/E valuation.
The Cathay General Bancorp Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Cathay General Bancorp pick up where the valuation debate leaves off and spell out which earnings, growth and margin paths would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Rather than leaning on a single multiple or model line, each framework sets out the key assumptions behind its fair value so you can test those against future results as they come through.
Community views on Cathay General Bancorp split between capital returns being underappreciated and funding costs already being fully reflected.
Bull case: 14% undervalued
"The current valuation implies that the market is assigning limited value to Cathay General Bancorp’s combination of above-target capital returns, expanding net interest margin, and guidance that points to higher earnings capacity than the share price reflects..."
Discover why this Narrative puts Cathay General Bancorp at 14% undervalued.
Bear case: 15% overvalued
"The numbers imply the share price already reflects strong capital generation, robust dividends and buybacks, and current profitability, leaving limited room for upside if growth and funding costs remain consistent with recent trends..."
Explore why this Narrative puts Cathay General Bancorp at 15% overvalued.
The share price is only one clue in the Cathay General Bancorp story
Price and current earnings tell you where Cathay General Bancorp stands today. However, professional expectations for the business a few years from now provide a different yardstick that can sharpen your decision. Explore where analysts expect Cathay General Bancorp to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com