


How Sartori Partnership Growth At Coupang (CPNG) Has Changed Its Investment Story
- On 22 October 2026, Sartori Cheese reported that its partnership with Coupang is accelerating its international expansion in South Korea, using Coupang’s Rocket Fresh logistics to deliver high value perishable products efficiently to Korean consumers.
- Coupang’s network helped generate more than US$5b of overseas sales for U.S. goods and services in 2025, highlighting how its logistics infrastructure can support American brands’ access to Asian demand at scale.
- We will now look at how Coupang's role in moving Sartori Cheese across Korea could influence the broader investment narrative.
Scan Coupang’s role as a cross border launchpad, then size up other logistics powered consumer plays using our hand picked 19 high quality undiscovered gems for ideas that may still be under the radar.
Coupang Investment Narrative Recap
Coupang rests on one core belief: its dense logistics network and WOW customer cohorts can eventually support healthier margins across Product Commerce and newer services. The Sartori Cheese partnership illustrates that thesis in practice. It shows the platform can handle high value perishables at scale, but on its own it does not change the near term story.
The key short term swing factor remains whether higher technology, AI, and infrastructure costs ease relative to revenue. Heavy spending in Developing Offerings, especially Taiwan, and past shocks in Korea keep execution risk elevated. If unit economics in newer markets take longer to improve, pressure on adjusted EBITDA and net income could persist.
The Sartori announcement is most relevant because it highlights Coupang’s role as a cross border launchpad. Management reported that its infrastructure supported more than US$5b of overseas sales for U.S. goods and services in 2025. That underscores that logistics density is not just a cost item. It can also be a magnet for brands that care about freshness and reach.
For you as a shareholder, the link to potential catalysts is straightforward. If more exporters treat Coupang similarly to Sartori, that can deepen Rocket Fresh usage and potentially lift revenue per active customer in Korea without entirely new categories. The operational test is whether that additional volume improves warehouse utilization and delivery efficiency faster than it adds fulfillment and marketing expense.
Coupang's narrative projects US$48.0b revenue and US$1.3b earnings by 2029. That profile lines up with analyst assumptions of 10.6% yearly revenue growth and an earnings swing of about US$2.1b from a loss of US$767.0m today to those forecast profits.
Discover why Coupang's fair value indicates a 64% potential upside to its current price, which could narrow quickly.
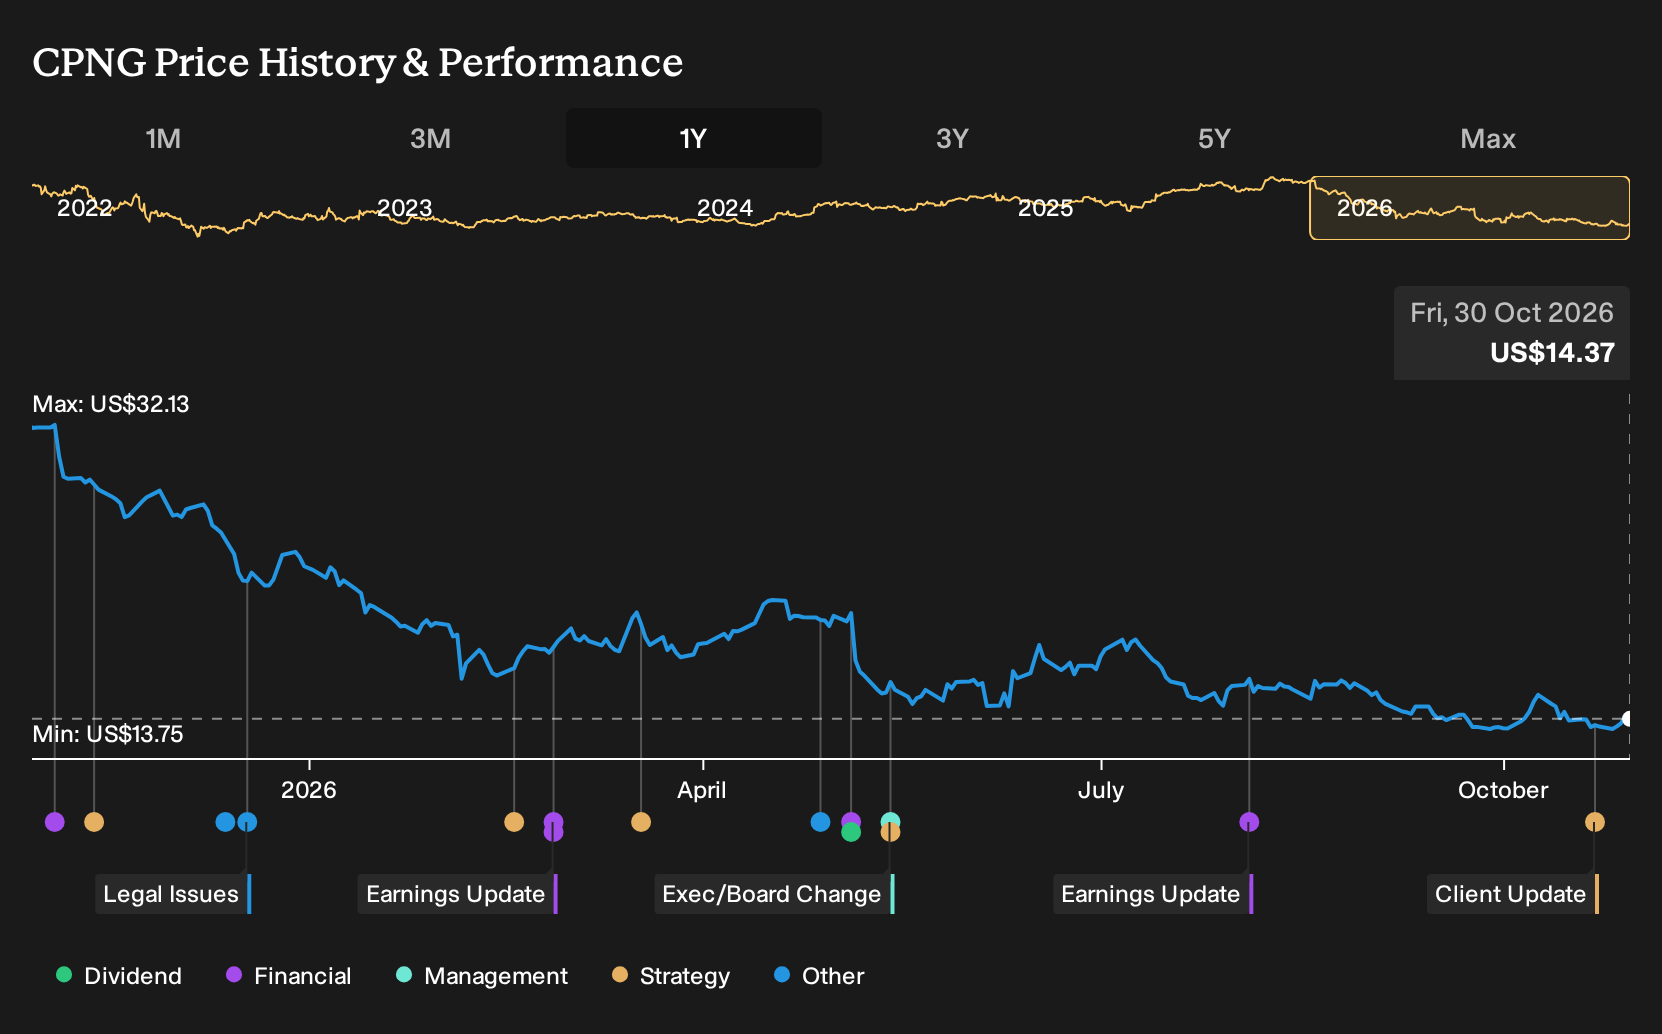
Exploring Other Perspectives
One alternate, more optimistic read on Coupang treats cross border demand as the real catalyst. The most bullish analysts were already penciling in revenue of about US$54.7b and earnings of US$2.4b by 2029 before this Sartori news, far above consensus. You can use this spread in views as a prompt to explore several potential scenarios for the company’s development.
Explore 5 other Coupang fair value estimates, including one that suggests potential upside of up to 109% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Coupang research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Coupang. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Coupang's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coupang?
Once you have a view on Coupang, it can help to widen the lens and compare it with other opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- If you want potential mispricing combined with solid fundamentals, consider scanning a curated 33 high quality undervalued stocks that could offer a different balance of quality and price than Coupang.
- For those who care most about capital preservation and steadier profiles, filter for 29 resilient stocks with low risk scores that might suit a more cautious approach.
- Income focused investors can aim straight at cash returns by checking out 5 dividend fortresses that prioritize yield alongside business resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com